FACING OLD AGE A STUDY OF OLD AGE DEPENDENCY IN THE UNITED STATES AND OLD AGE PENSIONS
Transcriber’s Note:
New original cover art included with this eBook is granted to the public domain.
FACING
OLD AGE
SOME RECENT BORZOI BOOKS
IN DAYS TO COME
By Walter Rathenau
EARLY CIVILIZATION:
AN INTRODUCTION TO ANTHROPOLOGY
By Alexander A. Goldenweiser
HUMAN NATURE IN POLITICS
By Graham Wallas
HOW ENGLAND IS GOVERNED
By Rt. Hon. C. F. G. Masterman
PRINCIPLES OF SOCIAL PSYCHOLOGY
By James Mickel Williams
THE HISTORY OF SOCIAL DEVELOPMENT
By Dr. F. Müller-Lyer
THE FOUNDATIONS OF SOCIAL SCIENCE
By James Mickel Williams
For sale at all bookshops
For further particulars address
ALFRED A. KNOPF, Publisher NEW YORK
BY
ABRAHAM EPSTEIN
Formerly Director Pennsylvania Commission to Investigate Old Age Pensions
NEW YORK ALFRED·A·KNOPF MCMXXII
COPYRIGHT, 1922, BY
ALFRED A. KNOPF, Inc.
Published, March, 1922
Set up and printed by the Vail-Ballou Co., Binghamton, N. Y.
Paper furnished by W. F. Etherington & Co., New York, N. Y.
Bound by the H. Wolff Estate, New York, N. Y.
MANUFACTURED IN THE UNITED STATES OF AMERICA
“The days of our years are three score years and ten; and if
by reason of strength they be four score years, yet is their
strength labour and sorrow; for it is soon cut off and we fly
away.”—90th Psalm.
This book is, frankly, an appeal for social action. It
attempts to set forth the need for a constructive policy with
regard to the aged. While the tide in social legislation seems
to have turned during the past few years, so that in many states
attempts are being made to repeal long sought for protective
measures, there is on the other hand evidence of an awakening
of many to the realization that the problem faced by the aged
cannot be ignored or postponed much longer. There is a
growing consciousness that social action is as inevitable for
the United States as it was in most countries abroad. Suffice
it to mention the many state commissions investigating the
problem recently, the great number of industrial concerns
grappling with it, and the numerous resolutions adopted by
many church bodies, fraternal orders and trade union organizations
endorsing government legislation with regard to the
aged. The fact that twenty-six foreign countries have already
adopted some form of social action for the relief of the aged is
indicative further that the problem is a matter for social rather
than for individual solution.
The writer did not approach the question of insurance with
any preconceived notions. Three years of first hand study
of the problems of the aged in one of our leading industrial
states—Pennsylvania—convinces him, however, that no other
way out is feasible. Our present methods, in dealing with the
aged are antiquated, inefficient, ineffective, costly and demoralizing.
Some constructive social policy must be inaugurated.
In discussing the plans suggested for adoption, an
earnest effort has been made to present the merits and demerits
of each proposed scheme of legislation impartially. The
xiiwriter may be accused, however, of a certain bias in connection
with this presentation, to which he pleads guilty. Absolute
impartiality in matters of social policy is only possible when
convictions and interests are slight. After everything has been
said and done it remains for the individual to determine what
he understands by “right” and “truth,” and he can only be
guided by his own conscience and convictions.
In describing the pension systems of foreign governments,
an attempt has been made to bring the facts up to date. This
was only partly successful. Since the beginning of the war,
European documents which were readily obtainable under normal
conditions, have been very meagre and limited, and some
reports have not been brought up to date.
The subject matter in the book beginning with Chapter Eight
has been drawn liberally from the report of the Pennsylvania
Commission on Old Age Pensions which was written by the
author in 1919. Everywhere, however, an attempt has been
made to collect and present the latest available data.
The writer wishes to record his debt of gratitude to the
Pennsylvania Commission on Old Age Pensions, which has so
generously extended to him the time and the office facilities
which were necessary in the preparation of this volume. The
keen interest of members in the problem has been a constant
encouragement and source of inspiration. He also wishes to
acknowledge his indebtedness for helpful suggestions in preparing
the manuscript to Professor Henry R. Seager of Columbia
University, Mr. George M. P. Baird, formerly of the
University of Pittsburgh, Miss Mary Bogue of the Mothers’
Assistance Fund of Pennsylvania, Miss Theresa Wolfson of the
Consumers’ League of New York State, and Mrs. Helen Glenn
Tyson, of the University of Pittsburgh.
A. E.
New York City
July 5, 1921
INTRODUCTION
xiii
During the past dozen years, America has made her greatest
progress in manifesting public concern for her large numbers
of bread-winners who are annually rendered incapable of self-support
by accident, sickness, unemployment and old age.
These four great contingencies in the life of the wage-earner—long
recognized as social problems of pressing importance in
countries of earlier industrial development—now claim our increasing
attention.
The free access to tillable land, which long offered “another
chance” to the dissatisfied industrial employee, has become to
millions of American city dwellers nothing more than a dream.
Meanwhile, as our country has become increasingly industrialized
we have invited to our shores millions upon millions of immigrants
whose course of thinking has not been influenced by
American social and economic opportunities of the past. We
have a diverse population that yearly becomes more and more
like the populations of those older countries, and still less akin
to our earlier sturdy sons of immigrants who half a century
ago could and did sing “Uncle Sam is rich enough to give us all
a farm!”
With the ever-increasing demand for essential workers in our
industries has come a condition where matter-of-fact statisticians
report 3,000,000 disabling accidents yearly causing
50,000,000 days lost time; and 250,000,000 days lost annually
on account of sickness; while “four times in a single generation
the numbers of the unemployed in the United States have been
counted by millions and the idle capital of the country has been
xivcounted by the billions of dollars.” All of this has its effect
upon savings for old age.
The United States, a younger nation, and with traditions
of individualism based on earlier opportunities, has been slower
to face these industrial problems, but recently there have been
signs of an awakening sense of responsibility. Voluntary
efforts of trade unions and humanitarian experiments of the
more thoughtful employers have blazed the way towards social
action. Half-a-hundred official investigating commissions
have collected, classified and disseminated information—resulting
in most instances in recommendations for American
legislation.
The industrial accident problem has been attacked in America
by an intelligent method of social insurance, and although
fully adequate benefits are not yet offered, within twelve years
no less than forty-seven workmen’s compensation laws have been
adopted. Naturally enough, the equally important problem
of wage-earners’ sickness is now under constant investigation
and the public is learning to look upon it as a subject which will
in future claim far more sweeping legislative attention. Unemployment,
the most complex of all industrial questions,
periodically forces its way to the front pages of our newspapers,
and in 1921 the Senate Judiciary Committee in one
state legislature, by unanimous vote, recommended the adoption
of compulsory unemployment compensation. The rapid spread
of American social legislation, when once initiated, is strikingly
illustrated by the adoption of Mothers’ Pension Laws in forty-one
states and territories during the nine years 1911 to 1919.
Old age dependency has been less talked about, partly no
doubt because this evil presents itself less dramatically—its
saddest victims usually being hidden from the public eye—partly
also, because fewer people realize its connection with our
modern industrial methods. Men have always grown old, it is
true, but now when they must seek work in a system whose
xvdemands for intense application or speed are often merciless,
they are rejected as unemployable and find themselves without
means of support at an earlier age. In exceptionally fatiguing
or dangerous trades the “human scrap-heap” age is distressingly
low. A system which in the past has paid wages far too low
to permit the average workmen to prepare for old age by saving,
is annually refusing jobs to thousands who are “too old”
to do its work.
The haphazard attempts to meet this problem through public
or private charity, employers’ pension systems and trade union
or fraternal society benefits, have proved to be not only inadequate
and inhumane, but also both costly and wasteful. Recently
great progress has been made toward scientific handling
of the problem as it affects public employees, especially
teachers.
The United States Government and many states and cities
have organized successful pension systems for their public
servants. A valuable record of a large scale American experiment
is furnished in the report of the first year’s experience of
the federal government with its pension plan covering nearly
one-third of a million civilian employees in the classified service.
But the problem of old age dependency for private employments,
has not been adequately met in any part of the United
States. Fortunately, signs of intelligent interest are becoming
more and more evident. Half a dozen states have appointed
commissions to study the subject, valuable material has been
gathered, and bills drafted. Unofficial but equally interesting
investigations have been carried on by labor organizations and
fraternal orders. Americans are recognizing the urgency of
this problem and are seeking authoritative information.
Not since the publication in 1912 of Mr. Squier’s “Old Age
Dependency in the United States,” have we had a new and comprehensive
book treating this problem. Appearing now when
there is both need and demand for such information, Mr. Epstein’s
xvivolume is especially timely and valuable. His experience
as Director of the Pennsylvania Commission on Old Age Pensions
has given him an exceptional opportunity for intensive
study of the field, and the book contains a wealth of modern,
well organized material presented from the modern American
point of view. It is decidedly the most convenient compilation
of up-to-date information on this very important subject.
John B. Andrews.
24 Gramercy Park, New York City.
January, 1922.
PART I ACTUAL CONDITIONS OF THE AGED — CHAPTER I AFTER SIXTY—WHAT? — CHAPTER II THE INDUSTRIAL SCRAP-HEAP — CHAPTER III PASSING BEYOND THE HALF CENTURY MARK — AGE — SEX — FAMILY CONNECTIONS — PHYSICAL CONDITION — CLASSES FROM WHICH RECRUITED — HOME OWNERSHIP, PROPERTY, AND INCOMES — CHAPTER IV THE COST OF FOLLOWING THE OSTRICH POLICY
1
The progress of a nation may be marked by the care which
it provides for its aged. The nineteenth-century doctrine of
laissez-faire, as applied to aged and superannuated wage-earners,
has been practically discarded by most civilized nations,
including every English-speaking country in the world
except the United States. Instead, a definite policy of social
legislation has superseded the chaotic and degrading practices
of alms-giving and poor relief. The enemies of social legislation
in this country, however, still contend that the millions of
workers in our industries “are working for themselves; that they
have unrestricted control over the expenditures of their incomes,
and that they have their future fate in their own hands.”[1]
As a nation, we are still frightened at the thought of becoming
“our brother’s keeper.” In spite of superior wealth and accumulation
of goods, our national conscience is not in the
least disturbed when the former creators of our wealth are
forced to drag out their final days, physically exhausted,
friendless and destitute, in the wretched confines of a poorhouse,
or to receive some other degrading and humiliating form
of pauper relief.
To protect the wage-earners in their old age is merely to
recognize the changes wrought in our industrial system. Old
age was not universally dreaded before the industrial revolution
or the advent of the modern factory system. On the contrary,
it was even looked forward to with a certain feeling of satisfaction
and accomplishment. In the patriarchal state, old age
2was revered and the aged person in tribal economy was considered
the embodiment of wisdom and authority.[2] In an earlier
system where the tribe or clan was a unit, the old remained
supreme and their superiority continued beyond their productive
years. Under the feudal system the lord was obliged to
take care of his workers in case of sickness, accident, and old
age. The artisan or labourer in mediaeval times ordinarily continued
to work as long as he could produce something. In the
early state of the factory system also the economic relations
between men were more inter-dependent and of a more permanent
character. The labour contract was usually lifelong,
and the employer took a personal interest in the welfare of his
workers. Again, in an agricultural society men and women
are still useful in their old age, and their activities rarely cease
before actual senility has set in. Under these conditions, men
and women did not look with dread upon approaching economic
old age, and there was little necessity for individual provision
against it.
Our modern wage system presents an entirely different spectacle.
Today, most men and women are dependent upon their
daily toil for their daily bread. The pace of the present industrial
system tends to wear workmen out rapidly. Fatigue
produced by over speeding as well as the hazards characteristic
of modern industry have shortened the period of effective
3production of industrial workers. Increased industrial efficiency,
“scientific management,” the “bonus system” and specialized
and standardized production are forces which are increasingly
using up human energy at greater speed and in a
briefer period of life. Often, at the age when the worker in
agricultural pursuits is considered to be in his prime, the industrial
worker is found to have become worn out and old. And,
in industry, once the approach of old age becomes apparent, the
worker is thrown upon his own resources.
Unlike the gradual physical decline in old age characteristic
of agricultural and less developed industrial countries,
economic superannuation, which takes place abruptly and
earlier in life, stands like a spectre before industrial workers.
Few industrial wage-earners may expect to continue at their
accustomed work until the end of their days. Because of the
developed efficiency standards, so essential to successful business,
the wage-earner finds the problem of old age principally
one either of increasing inability to find employment or at best
of employment at low compensation. After a certain age has
been attained, although the worker may still be able to do fair
work, if he is no longer able to maintain his former speed, he is
likely to be eliminated from industry. The old man finds it difficult
to secure work even at low wages. Rowntree and Lasker, in
a study of unemployment in Great Britain, found old age the
primary causal factor in 23.3 per cent. of the cases studied.
These investigators assert that: “It is unfortunately indisputable
that when a skilled worker gets past 40, he finds it
very difficult to meet with an employer who is willing to give him
regular work.”[3] What is true in England in this respect is
equally true in the United States.
Contrary to the conditions existing in the professions, in
business, or in politics, where men often do their best work at
about the age of 60, and where experience and long standing
4count a great deal, the industrial worker finds himself not infrequently
eliminated from productive industry after passing
his fiftieth birthday. With the continuous introduction of new
machinery and newer processes of work, age and experience are
of little value. The labor contract in the factory system is
made only for a temporary period, and the employer ordinarily
does not feel under obligation to support his workers during
their declining years of inactivity. Thus it is not uncommon
today to find aged and decrepit workers relegated to the industrial
scrap-heap as useless and of no economic value. Says
Prof. E. T. Devine:
“It is notorious that the insatiable factory wears out its workers
with great rapidity. As it scraps machinery so it scraps human
beings. The young, the vigorous, the adaptable, the supple of
limb, the alert of mind, are in demand. In business and in the
professions maturity of judgment and ripened experience offset, to
some extent, the disadvantage of old age; but in the factory and on
the railway, with spade and pick, at the spindle, at the steel converters
there are no offsets. Middle age is old age, and the worn-out
worker, if he has no children and if he has no savings, becomes an
item in the aggregate of the unemployed. The veteran of industry
who is crowded out by changes in processes and the use of new
machinery is obviously an instance of maladjustment.”[4]
It will become evident in the discussions that follow, that the
problem facing the aged today is largely the creation of the
modern machine industry with its components of specialization,
speed, and strain. It is a result of the elimination of large
numbers of workers as soon as they are unable to keep up fully
with the demands of modern methods of production. The introduction
of new inventions and more specialized machinery,
inevitable in the evolutionary process, while resulting in an
ultimate good, always involves the replacing of men, which in
the case of the aged, has an absolutely harmful effect, as it
5leaves them destitute. For, in addition to preventing their continuity
in their regular work, it precludes also their adaptability
to newer processes of work. The lot of the aged and
superannuated worker is thus adversely affected by practically
every step of industrial progress; and little or no benefit is
derived by old wage-earners from industrial improvements.
Not infrequently when the difficulties facing the aged wage-earners
are set forth, the smug and complacent citizen replies:
“As one makes his bed, so he lies.” Poverty in old age, it is
asserted, is chiefly the result of improvidence, intemperance,
extravagance, thriftlessness, or similar vices. As a result of
this convenient philosophy, we have made practically no attempt
at the amelioration of the adverse conditions facing old age.
More and more, however, it is coming to be recognized by all
students of social and economic conditions that with the cost
of living soaring continuously the great masses of wage-earners
cannot lay aside from current wages sufficient to provide for
possible emergencies. This has become especially patent as
careful data on wages and incomes have been gathered by such
students and responsible organizations as, Chapin, Ryan,
Streightoff, Nearing, the United States Census, the Bureau of
Labor Statistics in the United States Department of Labor,
the National Industrial Conference Board, and many of the
state bureaus. This entire problem will be discussed at length
in Chapter VI. It is sufficient to state here, that under present
economic conditions and those of the past decade, the average
wage-earning family must indeed be possessed of great resourcefulness
even to make both ends meet, to say nothing of being
able to save. In this connection it must also be pointed out
that saving for old age is especially difficult because the need is
remote and current demands press. The dangers of poverty in
old age hardly impress the minds of the young. Most people
have a working belief that things will be different thirty or
forty years hence, a time which, indeed, seems unreal and distant.
As Professor Seager aptly points out:
6“The conditions of modern industry have failed to supply motives
for saving sufficiently strong to take the place of those that are gone.
It is true that saving is still necessary to provide for the rainy day,
for loss of earning power due to illness or accident or old age, but
against these needs is the insistent demand of the present for better
food, for better living conditions, for educational opportunities for
children. This demand is not fixed and stationary. It is always
expanding.... One consequence of our living together in cities and
daily observing the habits of those better off than we are is that we
are under constant pressure to advance our standards. This pressure
affects the wage-earner quite as much as it does the college
professor. Both, when confronted with the problem of supporting
a family in a modern city, find the cost of living as Mark Twain
has said “a little more than you’ve got.””[5]
The problem to be faced in old age by wage-earners may thus
be summarized as being two-fold in character. First, the wage-earner
is confronted with the fact of being compelled to discontinue
work much earlier in life than should be necessary, not
because he is completely worn out, but because he is unable
to maintain the pace necessary in modern production; and
secondly, he faces the inability to provide individual savings to
support himself in old age.
In addition, the above conditions of impotence in old age
are augmented still further by the break-up of the family unit
in modern society. With increasing rapidity home ties and
family solidarity are being weakened and broken by the mobility
so essential to modern industrial development. This is
especially true in the United States and among wage-earners.
The migratory and immigrant labourers move from lumber-camps
to harvesting fields, railway construction, and public
works as the change of employment offers. Thousands of
aged workers find themselves in a strange country without
friends or relatives. Many of these have never had children, or
if they are parents, their children are unable to assist them.
7Ordinarily, the children are either unattached migrants
or are married and have children of their own who must
be supported and educated. No one contends that it is
good social policy to have children undernourished and set to
work early in life in order that they may help support the
passing generation. And as a result one finds that the only
source which secured sustenance and bare comfort to old age,
in an earlier society, has disappeared for a great many. We,
therefore, send these unfortunates, in our laissez-faire fashion,
to the unfriendly poorhouses to secure the care and comforts
available. Do they secure it? Says Professor Devine:
“Suicide, friendless old age, unemployment under ordinary industrial
conditions, some forms of insanity and other disabling
disease, immorality and crime, owe a part of their prevalence and
their virulence to the absence of the capacity or opportunity for
personal friendship, to the absence of those social props and safeguards
which our friends naturally supply. The almshouse is the
final apotheosis of friendlessness.”[6]
Indeed, once the difficulties faced in old age by the great
majority of workers are realized, one cannot but wonder
whether the fact that the aged population in the United States
has increased from 3.5 per cent. for those 65 years of age and
upward in 1880 to 4.3 per cent. in 1910, and that the expectation
of life has improved, has been a desirable thing and is
to be considered much of a blessing by the aged poor. Faced
with conditions such as described above, and with the almshouse
as the final destination of a life of destitution and drudgery,
do they not look upon modern industrial development,
as well as the advances made in medical progress and health as
the creations of an evil spirit, which have, on the one hand,
curtailed their period of production, and, on the other hand,
prolonged their years of misery by the increased duration of
life?
8
The prospects of living to old age are becoming increasingly
better as methods of sanitation and public health are
improved. According to the United States Life Tables, the
American vital statistics in 1910 showed that out of every
100 persons at the age of 20, 64 will reach the age of 60;
54, the age of 65; and 42, the age of 70. Of 100 persons
alive at the age of 30, 53 will reach the age of 65, and 48
will not die before 70. In other words, of all men alive
at the age of 30, more than one-half will reach 65. A
person who has reached the age of 65 may still expect to live
11 more years, and the person who has reached the age of 70
may still hope to have nine more years of life. In 1880,
according to the U. S. Census, the number of persons 65 years
of age and over in the entire population constituted 3.5 per
cent. This aged population increased to 3.9 per cent. in 1890,
to 4.2 per cent. in 1900, and to 4.3 per cent. in 1910. Of males
15 years of age and over, the number of those 65 and over
increased from 54 per thousand in 1880 to 60 in 1890 and 63
in 1910. It is thus clear that the proportion of older persons
in the United States has been constantly increasing.
In 1900 there were in the United States 3,083,995 persons
65 years of age and over, constituting 4.2 per cent. of the
total population. In 1910 this number increased to 3,949,524
and constituted 4.3 per cent. of the population. Of the nearly
four million persons 65 and over in 1910, 1,679,503, or 42.5
per cent., were between the ages of 65 and 69. The magnitude
of the old age problem is more easily appreciated when one
9reflects that this aged group outnumbers the entire population
of the United States during the time of the Revolution—the
first Census of 1790 giving the total population of the United
States as 3,929,214. No State in the Union, save the States
of New York, Pennsylvania, Illinois, and Ohio, has a greater
population; and the aged population in 1910 was greater than
the combined populations of the states of Arizona, Delaware,
Idaho, Montana, Nevada, New Hampshire, New Mexico, North
Dakota, Utah, Vermont, Wyoming, the District of Columbia,
and Alaska.
According to the United States Census of 1910 there were in
the United States at that time 38,167,336 persons 10 years of
age and over engaged in gainful occupations. These constituted
53.5 per cent. of the entire population of that age, an
increase of 3.1 per cent. over those reported gainfully employed
for the same ages in 1900, and an increase of 6 per cent. in
the population of the same age as compared with the proportion
gainfully employed in 1880. In the case of the male population
10 years of age and over, 81.3 per cent. were recorded as
gainfully employed in the United States in 1910 as compared
with 80.0 per cent. reported in 1900, and 78.7 in 1880. Of
the female population 23.4 per cent. of those 10 years of age
and over were reported gainfully employed in 1910 as compared
with 18.8 per cent. employed in 1900, and 14.7 per cent. in
1880.
That few wage-earners are able to continue at work until
the end of their lives is known to all. While the percentage of
the entire population which must secure its livelihood through
gainful work has steadily increased in the United States, it
is significant to note that the same Census figures show that
after middle age the percentages of those engaged in industry
and trades have been continuously diminishing. Out of every
100 males in gainful occupations in the United States in 1890,
thirteen and one-half were between the ages of 45 and 54; eight
between the ages of 55 and 64, and five and three-tenths were
1065 years of age and over. In the same year, ninety-six and
six-tenths out of every 100 males between the ages of 45 and 54
were found gainfully employed. Of those between the ages of
55 to 64, 92.9 per cent. were still found occupied, while of
those 65 years of age and over, 73.8 were still recorded as
engaged in gainful occupations. Ten years later, in 1900,
the percentage of males employed between the ages of 45 and
54 was 95.5; of those between 55 and 64, 90 per cent., and the
percentage of those over 65 who were still occupied dropped to
68.4, a decrease of 5.4 per cent. in 10 years. The 1900 Census
figures also show that of all the males 55 years of age and over,
85 per cent. were found gainfully employed in 1890, but only
80.7 of the same were employed in 1900, a decline of 4.3 per
cent. in 10 years.
The 1910 Census gives no age classification over 45. The
information available shows, however, that while in 1900, 87.9
per cent. of all males over 45 were gainfully employed, the percentage
declined to 85.9 in 1910. Assuming that the same rate
of decrease of the gainfully employed males 55 years of age
and over held true in the period between 1900 and 1910 as
that which took place between the decade of 1890 and 1900,
there would be only 76.8 per cent. of males 55 and over, in the
United States employed in 1910, as compared with 80.7 in
1900, and 85 in 1890. Similarly, in regard to those 65 and
over, 63 per cent. of the males in the United States would have
been employed in 1910 as compared with 68.4 in 1900 and
73.8 in 1890. Thus it may be assumed that of the 4,660,379
males 55 years of age and over in 1910, 1,081,208 were already
eliminated from the gainfully employed class.
DECLINE OF GAINFULLY OCCUPIED MIDDLE-AGED MALES
Percentage of Gainfully Occupied
Ages
1890
1900
1910
45–54
96.6
95.5
55–64
92.9
90.0
65 and over
73.8
68.4
63 (estimate)
55 and over
85.0
80.7
76.8 (estimate)
45 and over
87.9
85.9
11The steady reduction in the percentages of those gainfully
employed in the later years of life, as shown by the United
States Census reports, is largely due to the decrease in the
population of those ages engaged in industrial and manufacturing
pursuits rather than agricultural and professions. This
is obvious from the following: Of the total 38,167,336 gainfully
employed persons in the United States in 1910, 12,567,925,
or 32.8 per cent., were engaged in agricultural pursuits;
10,807,521, or 28.4 per cent., were engaged in manufacturing
and mechanical occupations; 7,605,730, or 20 per cent., in
trade and transportation; 5,361,033, or 14 per cent., were
found employed in domestic and personal services, and 1,825,127,
or 4.8 per cent., were engaged in various professional
vocations. The tremendous expansion in the manufacturing
and mechanical pursuits is apparent from the fact that the
population engaged in these occupations in 1900 was only
7,085,309. There was an increase of more than three and
one-half millions in 10 years. On the other hand, of the
1,065,000 men 65 years of age and over reported gainfully
employed in 1900, approximately 50 per cent. were engaged
in agriculture, a considerable number were engaged in the professions
and business, and only about one-third of the number
were employed as wage-earners. In 1900 the persons 55 years
of age and over constituted 12.3 per cent. in all occupations.
When this group is classified in accordance with the nature
of its work, it is found that 15.1 per cent. of this group were
engaged in agricultural pursuits; 15 per cent. in professional
vocations; 10.5 per cent. in domestic and personal services;
10.5 per cent. in manufacturing and mechanical pursuits, and
9.5 per cent. in trade and transportation. Thus while the
aged group of 55 and over constituted 12.3 per cent. in all
occupations it is much higher than this average in the case of
agricultural and professional pursuits, but is much below the
average in the case of manufacturing and transportation
occupations. This is practically the reverse of the proportions
12found among those gainfully employed in the various industries
in the earlier age groups.
Further light upon this phase may be gleaned from the
Twelfth Census. According to the 1900 Census enumeration,
the percentage of the total number of workers in all occupations
between the ages of 45 and 54 formed 25.8 per cent. of workers
of all ages employed in all occupations. The percentage of
those employed between 55 and 64 was 12.3, and that of those
64 and over, 4.4 per cent. These figures were obtained after
the elimination of certain occupations which have a large proportion
of boys as well as those in which the majority of
workers were women. A comparison of the percentages for all
occupations with the percentages of those engaged in the industries
given in the table below reveals the fact that, while
in the outdoor industries the percentage of those employed
between 45 and 54 holds approximately true, it is considerably
below in the case of the heavier industries, and much below the
general proportion after the 55th birthday has been reached.
NUMBER AND PER CENT OF EMPLOYEES 45 AND OVER IN SELECTED INDUSTRIES IN THE UNITED STATES, 1900[7]
45 to 54
55 to 64
65 and over
Occupation
No.
Percent
No.
Percent
No.
Percent
All Occupations
6,187,927
25.8
2,925,122
12.2
1,065,275
4.4
Marble & Stone Cutters
14,339
26.3
5,264
9.6
1,498
2.7
Painters, Glaziers,
Varnishers
69,681
25.2
28,406
9.9
7,759
2.8
Brewers and Maltsters
5,204
25.1
1,686
8.1
419
2.0
Steam Boilermakers
5,938
17.0
2,103
6.3
527
1.5
Iron and Steel Workers
47,042
16.3
15,789
5.4
3,783
1.3
Brass Workers
3,822
14.7
7,394
5.3
360
1.3
Potters
1,950
14.7
691
5.2
208
1.5
Glass Makers
5,575
11.7
1,737
3.6
392
0.8
The Thirteenth Census does not give the age classifications
which would make a similar comparison possible. However,
the Massachusetts Commission on Old Age Pensions, Annuities,
and Insurance, found in 1910, in a study of 870 aged persons,
that the average age at which the wage-earning power was completely
lost was 68 years. The average age at which the
13earning power was partially impaired, in a study of 872 partially
incapacitated persons, was 64. In 1918, the Ohio Commission
on Health Insurance and Old Age Pensions found in
six foundries employing 500 moulders only three men over 50
years of age engaged in heavy floor moulding. Ten men over
60 were engaged in light bench moulding.
The table below shows succinctly that the strain of modern
machine industry permits only a few wage-earners to remain
at work after they have passed three score and five. It is
further proof of the above figures pointing to the constant reduction
of those 65 years of age and over engaged in mechanical
and manufacturing pursuits. An examination of the
table compiled in 1920, regarding the ages when actually
pensioned as compared with the ages required by these large
concerns for obtaining a pension, reveals the fact that in spite
of the strict regulations provided, a number of these have
actually been pensioned before the specified age. Thus more
than one-half of those on the pension list of the United States
Steel and Carnegie Pension Fund have retired before the age of
65, although the age for voluntary retirement is set at 65.
In the case of the pensioners of the Pennsylvania Railroad
Company, while the compulsory age of retirement is set at
70, 44 per cent. had been placed on the pension list before they
had reached the compulsory retirement age. Similar proportions
are found in the case of most of the other industrial
pensioners.
14
PENSIONABLE AGES PROVIDED AND AGES WHEN ACTUALLY PENSIONED BY LEADING INDUSTRIAL CONCERNS
Name of Company
Pensionable Age Provided
Actual Ages When Pensioned
Under 50
50 to 60
60 to 65
65 to 70
70 and over
No.
Percent
No.
Percent
No.
Percent
No.
Percent
No.
Percent
U. S. Steel & Carnegie Pension Fund.
Any age if permanently incapacitated; 65 at request.
128
3.5
420
11.6
1,487
40.5
927
25.4
695
19.0
Penna. R. R.
70 compulsory, 65 to 69 at approval of Board.
1,209
13.0
2,796
31.0
5,124
56.0
Philadelphia and Reading R. R.
70 compulsory; 65 to 69 if incapacitated.
20
2.0
15
1.5
24
2.5
201
20.5
716
73.5
N. Y. Central Railroad
70 compulsory; any age if unfit for duty.
1,606
36.3
2,828
63.7
Philadelphia Electric
No compulsory age; voluntary retirement, male 65, female 60.
13
6.5
35
16.5
54
25.5
87
41.5
21
10.0
Pittsburgh Coal Co.
No compulsory age; any age if incapacitated after 10 years of service.
8
4.0
42
21.0
55
28.0
50
25.0
44
22.0
Westinghouse Air Brake
70 compulsory; by order of Board.
3
3.0
8
7.5
8
7.5
16
15.5
69
66.5
National Transit Co.
Compulsory, male 65, female 55; voluntary, male 55, female 50.
4
6.1
23
35.5
21
32.2
17
26.2
Pittsburgh and Lake Erie R. R.
70 compulsory; any age if unfit for duty.
2
3.7
1
2.0
4
7.3
6
11.0
41
76.0
The extent of disability of wage-earners as they are affected
by both age and occupations has been brought out in a comprehensive
manner by Dr. Boris Emmet from studies recently made
of the Workmen’s Sick and Death Benefit Fund of the United
States, for the United States Bureau of Labour Statistics.[8]
These investigations show conclusively that age and occupation
15are the two most important factors in determining the duration
and extent of disability. The average number of days of disability
per member was found to be 6.6 per annum. An examination
of the age groups shows that up to the age of 45 the
disabilities’ duration is below the average, but from that age
on, it increases steadily until it averages 15.2 in the case of
those who are 70 years of age and over. By the different age
groups the percentages above (+) or below (−) the average
are as follows:
Age Group
Average No. of Disability Days
Per Cent of Deviation from Average
Under 20 years
5.2
−21.2
22 to 24 years
4.8.
−27.3
25 to 29 years
5.0
−24.2
30 to 34 years
4.9
−25.8
35 to 39 years
5.6.
−15.1
40 to 44 years
6.4
−3.0
45 to 49 years
Same as average
50 to 54 years
7.4
+12.1
55 to 59 years
9.0
+36.4
60 to 64 years
12.0
+81.8
65 to 69 years
13.8
+109.1
70 years and over
15.2
+130.3
All age groups
6.6
None
The occupational hazards of certain of our large industries
are presented so clearly in the table below that no comment at
length is necessary. While in the professions the average number
of days of disability per year is 2.6, it progresses continuously
until in the case of miners it reaches 9.7, almost four
times as great.
ANNUAL DISABILITY DAYS FOR EACH OCCUPATION
Occupation
Average Annual Disability Days per Year
Professional
2.6
Jewelers
3.6
Clothing Mfr. Employees
4.4
Textile Mfr. Employees
4.5
Trade and Clerical
4.7
Electrical Workers
4.8
Other Manufacturing Employees
5.1
Farmers, Gardeners, and Florists
5.3
Sheet Metal Workers
5.6
16Plumbers
5.6
Plasterers
5.6
Unspecified Occupations
5.7
Molders
5.8
Leather Workers
5.8
Tanners
5.8
Auto, Carriage and Wagon Mfg. emp.
5.9
Barbers
5.9
Engineers and Firemen
6.0
Bartenders
6.0
Woodworkers
6.1
Printers and Engravers
6.1
Machinists
6.1
Food Employees
6.2
Cooks and Waiters
6.2
Dyers
6.4
Painters
6.4
Clay Products Mfg. emp.
6.6
Other Building Construction emp.
6.0
Carpenters
6.7
Tobacco and Cigars
6.8
Slaughtering and Meat Packing emp.
6.9
Blacksmiths
6.9
Labourers, not specified
6.9
Glass Workers
7.1
Bricklayers
7.1
Stone and Granite
7.5
Liquor Manufacturing emp.
7.9
Railway Employees
8.4
Drivers
8.6
Freight Handlers
9.6
Miners
9.7
Average of all Occupations
6.4
A valuable investigation in regard to this phase of the
problem was made by the Pennsylvania Commission on Old
Age Pensions, during 1918–19. This Commission interviewed
over 4,500 people, 50 years of age and over in a house-to-house
canvass in the cities of Philadelphia, Pittsburgh, and Reading.
It also made a study of the ages of partial and total impairment
of workers in several industries. A case of partial impairment
was assumed when the individual sustained a reduction in
wages, either because of displacement or change in job as a
result of sickness or old age. The Commission states that
its studies revealed the following:[9]
17(a) The earning power of many workers in Pennsylvania is impaired
before they reach the age of 40. The percentages of partial
impairment at the age of 40 were found to vary from 2.6 per
cent. among indoor and sedentary trades, to 16.4 in the steel industry,
and 57 per cent. in the case of railroad workers. Only in the
steel industry, however, were there many who were totally incapacitated
before the age of 50. In the building trades, 12.6 per cent.
were partially impaired before the age of 50; while 6.3 per cent.
were totally incapacitated before reaching the same age. On reaching
the above age it was found that 55.3 per cent. were partially
and 14.1 per cent. were totally impaired in the case of steel workers.
Of those engaged in casual occupations 26.7 per cent. have had
their earning power partly, and 8.4 per cent. wholly reduced before
attaining 50 years of age. Of indoor and sedentary trades the
percentage of partially impaired workers before the 50th birthday
was 15.2, while 8.3 were wholly disqualified for service at that age.
Nearly 27 per cent. among glass blowers had had their earning
power reduced before reaching 50 years of age, and 20 per cent.
were permanently incapacitated at the same age. Of skilled workmen
in the various trades, 29 per cent. were impaired partially and
less than three per cent. entirely, before attaining their 50th birthday.
Among railroad workers, those whose incomes were affected
before the age of 50, the percentages were 64.3 to a partial extent,
and 6.2 entirely.
(b) At the age of 60, the proportion of workers, whose earning
power had not yet been affected, according to the various trades,
were as follows: In the building trades, 55.1 per cent. suffered
no loss of income before reaching the age of 60. In the steel industry
only 13.2 per cent. were earning the same amounts as in
their earlier days at the above age. Thirty-six per cent. of workers,
at 60 years of age, were still found to be engaged in casual occupations.
Among workers in indoor and sedentary trades, 46.4 per
cent. were found without reduction in their earning power at the
age of 60. Only 26.9 per cent. of glass blowers were in their
full capacity at the age of 70. The percentage of skilled mechanics
found in good health at 60 was 25.5, while 28.2 per cent. of railroad
workers were found to be in unimpaired health at the age of 60.
The Commission concludes: “An examination of the total number
18of aged persons in all the three cities from whom the previous
and present occupations were ascertained, shows that men past a
certain age must quit even the skilled trades in which they have
been engaged the greater part of their lives. Modern industry,
apparently, has little use for the superannuated worker. A few
men can continue working at the same occupation after they have
reached a certain age. While 36 per cent. stated that they were
skilled or semi-skilled mechanics in their earlier days, only 23.8
per cent. of men past 50 years of age were still engaged in the
same occupation. The percentage of those doing unskilled or common
labour or clerical labour, on the other hand, remained stable.
It is also to be noticed that in their earlier days less than two per
cent. were not working because of incapacity, but 26.6 per cent.
were found not to be working among those 50 years of age and over.
The fluctuations of the minor occupations are inconsiderable.”[10]
Similar studies of several hundred bituminous miners scattered
through a dozen mining districts in Pennsylvania and
of about two hundred steel workers were recently completed
by the writer for the above Commission. The investigations
disclose that of 368 miners, 50 years of age and over, 177
were still in fair or good health, while 191 or somewhat more
than 50 per cent. of those investigated, were found to be either
partially or totally incapacitated. Of the 112 reported as
partially incapacitated, 79, or 70.5 per cent., became so before
the age of 60; of the 79 reported as totally incapacitated
38, or 50 per cent., were thus disabled before the same age.
While most of those reported as partially incapacitated
were still engaged in some form of work or other, this was
irregular and uncertain, as most of these persons were suffering
either from chronic sickness or the consequences of serious
accident.
In the case of 146 steel workers, 50 years of age and over,
investigated in Homestead and Steelton, 90, or 62 per cent.,
were found to be either in part or completely impaired in respect
19to their health and earning power, the great majority of
these becoming incapacitated before the age of 60. The causes
of impairment assigned in more than three-fourths of the cases
of both classes of labour were either sickness or accident. Old
age, as such, was given only in a few instances as a direct
cause of incapacity.
AGES OF INCAPACITY OF MINERS AND STEEL WORKERS
Miners
Steel Workers
Ages of Incapacity
Partial
Total
Partial
Total
Under 50
29
15
8
4
50 to 60
50
23
25
5
60 to 65
18
15
11
6
65 to 70
14
20
4
5
70 and over
1
6
12
10
Total Incapacitated
112
79
60
30
The reports of the different State Industrial Accident Commissions
and Compensation Bureaus corroborate further the
evidence at hand that there are fewer persons past middle age
engaged in industry than the proportion of the same group
in the entire population. The Industrial Commission of Wisconsin
reported in 1915 that of all persons injured at work
in that state, 53 per cent. were under 30 years of age; 67 per
cent. were under 40; 5 per cent. between 50 to 55, and only 5
per cent. more above that age. For the population 15
years of age and over as a whole, 7 per cent. were 50 to 55,
and 16 per cent. were 55 and over.[11] The California Industrial
Accident Commission reports that in 1918, of 2,100 permanent
injury cases, 1,729, or 82.3 per cent., were under the
age of 50; 257 were between 50 and 60, and 114 above that
age.[12] Of 2,569 fatal accident cases which occurred in Pennsylvania
in 1919, 1,932 or 75.2 per cent., were under 50 years
of age; 262, or 10.2 per cent., were between the ages of 50
and 60, and only 136, or 5.2 per cent., were above that age.
The ages of the rest were not ascertained.
20Even more significant in this respect are the disclosures of
an investigation of several trade union locals recently made
by the writer. Printers are known to work much longer in
life than do workers in many other crafts. In spite of this
fact, it was found that of a membership of approximately 1,500,
the Philadelphia Typographical Union No. 2 had on its lists
only 145 persons, approximately 10 per cent., who were 60
years of age and over; and 47 of these were already on the
pension roll of the International Typographical Union. Local
No. 98, Philadelphia, of the International Brotherhood of
Electrical Workers had no one 60 years of age or over on its
membership roll of approximately 1,250. Workers in the
building trades, it is frequently asserted, work until very
late in life. An examination of the ages of 450 members of
Carpenters’ Local No. 287 in Harrisburg showed only 25
persons 60 years of age and over. Bricklayers’ Local No.
71, in the same city, had only 14 members between the ages
of 50 to 60 and a similar number 60 and over among 152
members. Carpenters’ Local No. 1073, Philadelphia, has been
in existence since 1902 and has a membership of over 1,400.
There were in this local only 60 men who were 50 years of age
and over, and only seven of these were above 60. A canvass
of over 600 miners’ locals with a membership of over 120,000
persons, made a few years ago by a Committee of the United
Mine Workers of America, showed that there were in these
locals a total of 6,283 persons 60 years of age and over, of
whom only 2,084 were 65 years and upwards.
From the foregoing evidence it seems obvious that modern
industry finds little use for the worn-out workers. It replaces
and discards these aged wage-earners as it is in the habit of
replacing and discarding the worn-out and inefficient machinery.
Once economic old age has set in, the road to dependence
is short. Says Mr. L. W. Squier: “After the age of sixty
has been reached, the transition from non-dependence to dependence
is an easy stage—property gone, friends passed away
21or removed, relatives become few, ambition collapsed, only a few
short years left to live, with death a final and welcome end
to it all—such conclusions inevitably sweep the wage-earners
from the class of hopeful independent citizens into that of the
helpless poor.”[13]
22
The aged, for the purposes of our discussion, may be classified
into three distinct groups. First, the small group of
wealthy and independent persons whose economic and social
security is assured. This group presents no problem such as
those which are discussed in the pages that follow, and may
be dismissed. Secondly, the great mass of the aged wage-earners
who are presumably non-dependent because, in order
to avoid the stigma of pauperism, they do not, as a rule, seek
aid from charitable and philanthropic sources. These will
prefer to make all sorts of sacrifices rather than seek asylum for
their last days in either county poorhouse or benevolent home.
Many of this group, therefore, while nominally non-dependent,
may nevertheless be below the poverty line, and very often,
although they find themselves in want through no fault of
their own, will prefer to endure hardship rather than accept
charity. From any point of view this group, which represents
the great majority of wage-earners, has the greatest claim to
protection and relief in old age. Their problems must not
merely attract attention but must be studied thoroughly and
met squarely with a constructive social policy. The third
group, which is considerably smaller, is composed of the institutional
and pauper classes and includes the inmates of the State,
county and private charitable institutions, as well as the
recipients of public or private relief from local poor boards,
philanthropic organizations, churches and similar institutions.
Knowledge of the actual conditions which compelled this unfortunate
23group to seek relief; an examination of the effects and
consequences of our present methods of relief distribution;
and a revaluation of these methods in terms of social justice,
are essential in a study of this aged pauper group.
The proportion of the presumably “non-dependent” aged
persons in the United States who are actually living in want
and are in need of systematic relief is difficult to estimate accurately.
The Census reports supply very meagre data for the
determination of the extent of old-age dependency in the United
States; especially is this true with regard to the non-institutional
aged. However, a number of studies have been made
recently which may be considered fairly indicative of the magnitude
of the problem. The first study of dependency of the
aged was made in 1908–9 by the Massachusetts Commission
on Old Age Pensions, Annuities and Insurance. This Commission
estimated the number of persons 65 years of age and
over in Massachusetts to be 177,000 in 1910. Of this number
41,212, or 24 per cent., were found either to be residing in correctional
institutions and public or private pauper and benevolent
homes, or were the recipients of public or private outdoor
relief, or United States pensions. One hundred and
thirty-five thousand, seven hundred and eighty-eight, or 76
per cent., of these aged in Massachusetts were “non-dependent,”
as far as could be ascertained. Basing his calculations
upon the Massachusetts figures, L. W. Squier estimated
that approximately 1,250,000 of those 65 years of age and
over in the United States are dependent upon public and private
charity.
This estimate was admittedly conservative, as Mr. Squier’s
calculations were based upon cases of relief granted by the organized
charitable agencies; and even the recipients of this form
of relief could not have been, in the nature of such studies,
completely gathered by the Massachusetts Commission. No
account was taken of the unofficial and less known relief agencies,
and it goes without saying that neither the Massachusetts
24Commission nor Mr. Squier could determine the amount of
private charity extended. That Mr. Squier has under-estimated
rather than over-estimated the total number of aged dependents,
is shown by the 1915 decennial census of Massachusetts.
In this state-wide enumeration there were found 189,047
persons 65 years of age and over, of whom 34,496, or 18.2
per cent. of the total population of that age, were receiving
aid from one source or another. However, this number did
not include those aged who were receiving pensions from the
United States government. The number of this group was
estimated at 29,150, or 14.8 per cent. The aggregate number
of dependents thus constituted 33 per cent. While many of the
latter did not need such assistance, their number doubtless
increased the total dependents, and if used as a basis for the
entire United States would have increased Mr. Squier’s estimate
considerably.
Statistics dealing with those aged persons in the United States
who are definitely dependent upon public or private relief are
scanty and incomplete. The various groups of dependents
are classified according to age in only a few instances by the
United States Census. The 1910 Census reports that of a
total of 84,198 paupers in almshouses in the United States,
35,943 or 42.7 per cent. were 65 years of age and over. In
the same year there were 187,791 known insane and feeble-minded
persons in the United States, 21,881 or 11.8 per cent.
of whom were 65 and over. Of a total of 19,153 deaf and
dumb persons in 1910, only 797, or 4.1 per cent., were 65
and over. The number of prisoners 65 and over is not given
by the Census, but of the number committed to penal institutions
during the year 1910, only 1.6 per cent. were 65 years
of age and over. There were in 1910 also 98,846 adult inmates
over 21 years of age in benevolent institutions, the large majority
of whom were obviously of advanced age. Of the total
57,272 blind persons in the United States, 23,746 or 41.4 per
cent. were past threescore and five years. There were in addition
25in that year 72,948 dependent adult inmates in hospitals
and sanitoriums. No data are available to show the number
of aged persons in receipt of either public or private relief.
The recipients of this form of charity, however, generally
constitute the large majority of dependents, and as shown by
the different State Commissions, exceed the aggregate number
of dependents of all other classes. Neither do the classes
enumerated above include the great number who are in receipt
of State and Federal pensions, as well as those receiving pensions
from industrial establishments. It is, of course, impossible
even to estimate the number of those receiving partial or
entire support from individuals.
The Census figures seem to indicate also either a steady
increase in aged dependency in the case of most pauper classes,
or an increase in the longevity of most aged dependents. Thus,
the blind 60 years of age and over increased from 36 per cent.
of the total blind population in 1860, to 41.4 in 1910. The
deaf and dumb of the same age group constituted 4.9 in 1860
and increased to 6.7 per cent. in 1910. In the case of almshouse
paupers the percentage of the aged increased from 25.6
in 1880 to 42.7 in 1910.
Recently a number of special State Commissions on Old
Age Pensions have added further light upon the extent of
dependency in old age. The Wisconsin Industrial Commission
in its report on old-age relief in 1915, states:
“The number of persons 60 years of age and upwards in Wisconsin
may be estimated at 185,000. Of this number, probably
two per cent. are recipients of public or private relief. Even including
United States pensioners, the proportion scarcely exceeds
12 per cent. But that very much unrelieved distress exists no one
can doubt who is familiar with the statistics of other countries.
The inauguration of systematic old age relief invariably brings to
light a vast mass of unsuspected poverty among the aged. Thousands
of old people contrive to escape the clutches of the poor laws
who nevertheless endure a pitiful struggle for existence. They
26work beyond their strength, they deny themselves proper food and
clothing, they are aided by friends and neighbours, or they are
supported by their children, too often at the expense of growing
families.”[14]
The Ohio Commission on Health Insurance and Old Age
Pensions states:
“The number of aged persons aided by private families or by
relatives and friends is unknown and cannot be estimated. The
Hamilton and Cincinnati surveys indicate that 15 to 25 per cent.
of people over 50 were dependent upon relatives or friends. Nor
can the number who are living an independent but precarious
existence be accurately estimated.”[15]
The Pennsylvania Commission concludes that:
“Aside from the aged dependents found in almshouses, benevolent
or fraternal homes, and those receiving public or private relief,
there is a considerable proportion (43 per cent.) of the aged population,
50 years of age and over in the State, who, when reaching
old age have no other means of support, except their own earnings.”[16]
As the studies made by the Pennsylvania Commission in
regard to this phase of the problem of the aged, go into greater
detail than those of the other State Commissions, its conclusions
may perhaps be considered as fairly indicative of the extent
of destitution in old age among the industrial population of
this country. Based on the percentage found in Pennsylvania,
it may be said that in 1910 there were approximately
1,700,000 persons in the United States who had passed beyond
the half century mark and who had had no other means of
support in their old age except what they could earn themselves.
While it may be conceded that this proportion may
27be smaller in the less industrial States, the above estimate may
nevertheless be fairly accurate for the entire United States,
as the districts studied by the Pennsylvania Commission were
largely inhabited by better paid American-born workers as
contrasted with the more thickly populated foreign sections.
Of course, it must not be presumed that all of these will apply
for relief, either public or private, but it is obvious that the
great majority of these will have to face a pitiful struggle for
subsistence. Ultimately the majority of this number will become
dependent, if not upon public charity, then upon children
or relatives at the expense of self-respect, and in many cases
also to the great detriment of the growing generation.
In the discussions that follow, the individual and social
forces, as well as the moral factor that go to make for dependency
and pauperism will be dwelt upon at length. At this
juncture it is important first to examine and endeavour to
understand sympathetically the immediate conditions confronting
multitudes of superannuated workers which compel many to
become paupers in their old age. Indeed, a comparison of the
circumstances of the dependent aged, as disclosed by the different
State Commissions’ reports, with those of the so-called
non-dependent, discussed in the preceding pages, sheds much
light upon the frequently repeated question: “Why is it that
some workers succeed in remaining away from the pauper
homes, while others, apparently of the same class, become dependent
upon public charity?”
The age relativity among the different classes is significant.
In the total population of 1910 the group between 65 and over
constituted 4.3 per cent. of the population, and contained 4.2
per cent. of the males and 4.4 of the females of all ages. This
percentage held true for the native whites of native parentage.
Among the native whites of foreign or mixed parentage the
aged constituted only 1.4 per cent., while of the foreign born
28whites, the same age group contained 8.9 per cent., and among
Negroes 3.0 per cent. The proportion of the aged varies also
considerably in the different sections. According to the 1910
Census, the percentage of those 65 and over to the total population
was highest in the New England States, with 5.9 per
cent., and lowest in the West South Central States with 2.8
per cent. The Middle Atlantic States gave 4.4 per cent.; East
North Central, 5.1 per cent.; West Central, 4.6; South Atlantic,
3.6; East South Central, 3.5; Mountain, 3.0, and Pacific, 4.5
per cent.
The dependent classes, as is to be expected, are largely made
up of those of advanced ages. The relation of dependence to
old age is so clearly indicated in the following reports that no
additional comment is necessary. The Massachusetts Commission
in 1910 found that:
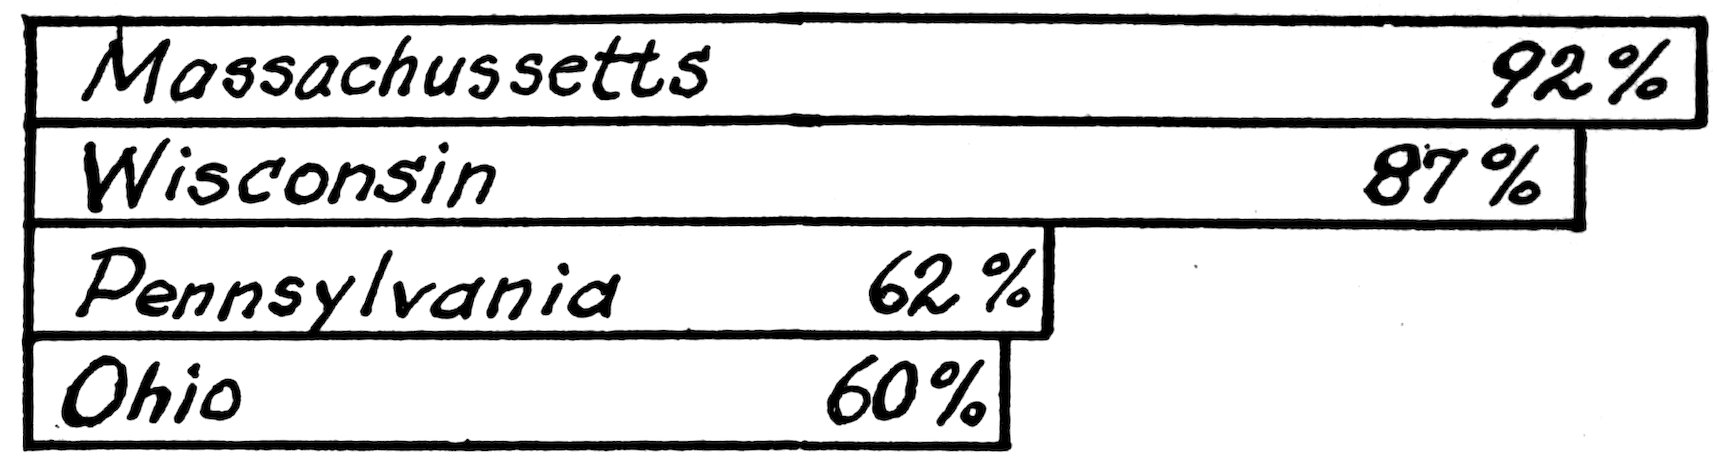
“Less than one per cent. of those for whom the age at entrance
was stated in the returns became inmates before the age of 40;
only eight per cent. entered before the age of 60; thus 92 per cent.
had passed the sixtieth year before they took up residence in the
almshouse.”[17]
Commenting on this, the Commission adds:
“The strikingly high proportion of persons entering pauper institutions
late in life points to the close connections between old
age and institutional pauperism. It is clear that such pauperism
is in most cases the result of the infirmity of advancing years,
rather than of the misfortunes of earlier years.”[18]
The Wisconsin Commission reports regarding the almshouse
population of that State, as follows:
“A very large proportion are of advanced age—only 17 per
cent. are under 65, 40 per cent. are 75 and over and nearly 25 per
cent. are 80 or above. In the population of the state at large, one-third
of all persons over 59 fall in the age group 60 to 65 and
29only one-fourth are above 74. This fact, taken in connection with
the great proportion of the entire almshouse population who are
60 and over, indicates a close co-relation between destitution and
old age.”[19]
The Ohio Commission states:
“In regard to age distribution, the records of the Ohio Board
of State Charities show that 4,772, or 60 per cent. of the regular infirmary
inmates were over 60 years of age, 2,926 or 37.1 per
cent. between 16 and 60 and 219, or 2.78 per cent. under 16 years
of age.”[20]
The Pennsylvania Commission concludes that:
“It appears that only about 13 per cent. were admitted under
50 years of age; 24.87 per cent. were admitted between the ages
of 50 and 60; 31.9 per cent. between 60 and 70, while over
24.78 per cent. were admitted after they had reached their seventieth
year. A comparison between our figures and those obtained
by the Massachusetts Commission on Old Age Pensions in 1908 is of
interest. In the New England State only eight per cent. of those
investigated entered the almshouses before the age of 60, and 92
per cent. had passed their sixtieth year before they took up residence
in the almshouse. The higher rate of those entering almshouses
below the sixtieth year in Pennsylvania may be explained by the
highly developed industries peculiar to this Commonwealth, which,
requiring greater physical strain, wear out and incapacitate men
at an earlier age. For those admitted during the year 1910 to
the almshouses of the entire country, the percentages were 17.7
between 50 to 59; 18 from 60 to 69 and 15.3 per cent. over 70
years.
“It is obvious, that the great majority of the aged inmates enter
the institution late in life. This would indicate a close relationship
between institutional pauperism and old age. The combination of
advanced years and infirmity, when coupled with the fact, that
in most cases these people have no one to depend or fall back
upon is—as will be seen later—the chief cause compelling an
30aged person to go to the poorhouse. Most men will stay out
of an almshouse as long as they can. When they are compelled to
take up residence there, it is usually not due to personal or other
misfortunes in earlier years, but in most cases, is the result of
feebleness and lack of assistance from other sources.”[21]
PERCENTAGE OF PERSONS IN STATE PAUPER INSTITUTIONS WHO ARE 65 YEARS OF AGE AND OVER.
Of the 3,949,524 persons 65 years of age and over in 1910,
1,985,976, or 50.5 per cent., were males, and 1,963,548, or 49.5
per cent., were females. This group was, in addition, divided
as follows in 1910: 1,693,010, or 42.8 per cent., urban, and
2,256,415, or 57.2 per cent. rural, while 1,183,349, or 29.9
per cent. were of foreign birth.
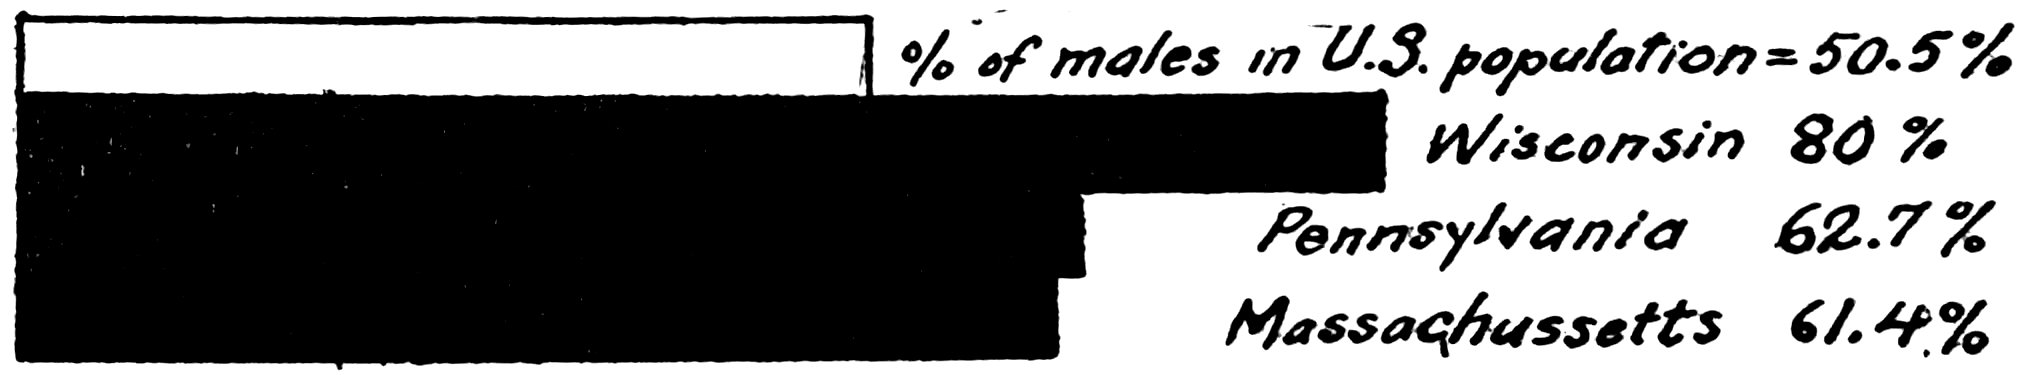
The 1910 Massachusetts Commission found the proportion
of males and females in the almshouses of that State to be
61.4 per cent. and 38.6 per cent. respectively. In this respect,
the Commission declares:
“The figures for the aged poor present a contrast to those for
the general population of the State, which is divided between the
sexes very evenly, with 48.7 per cent. males and 51.3 per cent.
females. The lack of any uniformity in the division between the
sexes in the case of the various classes is also striking. In the
classes of almshouse inmates, recipients of State and military
aid and non-dependent poor, the males preponderate; in the classes
of inmates of benevolent homes and recipients of public and private
outdoor relief, the males are greatly outnumbered. It appears
that relief in charitable institutions and in the homes through
31public or private agencies is given more largely to women than
to men.”[22]
In Wisconsin, the proportion of women in almshouses, the
Commission finds,
“Is very small—only 20 per cent. as against 47 per cent. of
the State’s population of 60 and over. This showing is the more
remarkable because the Commission’s sample census indicates
(what is true in other countries) that the number of aged widows
and single women exceeds the number of aged widowers and single
men. The explanation is that an elderly woman is better able
than an old man to maintain a home of her own or to fill a useful
niche in the household of a relative.”[23]
The Pennsylvania Commission found the almshouse population
to be composed of 62.7 per cent. males and 37.3 females.
It comments as follows:
“It is interesting to remark that the above percentages found
by the Commission are in exact agreement with the percentages
found by the Massachusetts Commission on Old Age Pensions
in its study in 1908. The comparative difference between the
sexes in the almshouses and that prevailing in the entire State
population is significant. According to the Thirteenth United
States Census, the percentage of males in the entire State population
was 51.4 per cent. and that of females 48.6 per cent. The
reasons for the disproportionate number of male paupers in institutions
over female paupers may be explained in several ways.
Children or relatives will make greater sacrifices in order to keep
an old mother at home and prevent her going to a poorhouse, than
they would for an aged father or other male relative. Aside from
the sentimental reasons involved, the presence of an old woman
around the home—unless she is absolutely invalided—entails little
burden, as she can be made useful in numerous ways. This, however,
is not the case with an aged man. Aged women are also
more generously provided for by private charity than are aged
men. The percentages of aged men and women who are inmates
32of benevolent and private Homes for the Aged, are 23.54 and
76.46 per cent. respectively. The relationship here is thus radically
reversed from that of the almshouse population.”[24]
PERCENTAGE OF MALES IN ENTIRE U. S. POPULATION, AND IN PAUPER INSTITUTIONS.
The number of old persons applying for charity in no way
indicates the degree of destitution in old age. Much of this
suffering is kept concealed from the public eye by timid and
sensitive children or relatives. This is borne out by the available
data on the family connections of aged persons. Indeed, the
investigations seem to disclose that pauperism among the aged
is in inverse ratio to the number of family relations and is largely
a result of the lack of family connections. The data below indicate
that, in most instances, children or relatives will endeavour
to support their aged dependents, regardless of the
sacrifices thereby required of themselves or of their children.
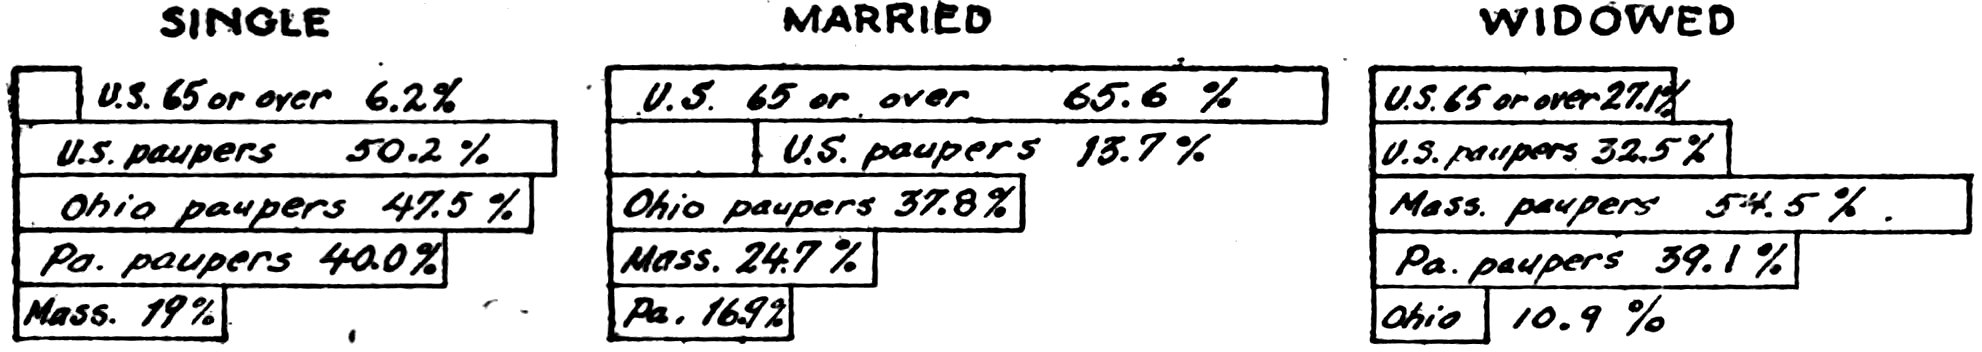
The Thirteenth United States Census gives the marital relationship
of the aged as follows:—males, 6.2 per cent. single,
65.6 per cent. married, 27.1 per cent. widowed, and 0.7 per cent.
divorced; females, 6.3 per cent. single, 35 per cent. married,
58.1 per cent. widowed, and 0.4 per cent. divorced. The Massachusetts
Commission found that 6.2 per cent. of the aged
persons investigated were single; 53.8 married; and 39.7 widowed.
In Wisconsin, in 1915, in a sample census of 1,395
persons, 60 years of age and over, there were 35, or 2.5 per
cent. single; 885, or 63.4 per cent. married; and 456, or 32.5
per cent. widowed. Of these, 76, or 5 per cent., lived alone; 885,
33or 63.4 per cent. lived with a spouse; 168, or 11 per cent. had
unmarried children; and 206, or 14 per cent., had married children.
The Wisconsin Commission concludes:
“It will be seen that substantially one-half of the women enumerated
are widowed, divorced, separated or single, whereas nearly
80 per cent. of the men are married. The explanation is partly that
women on the average live longer than men and partly that husbands
very generally are older than their wives. The result is
that a vast number of aged women are left without homes of their
own.”[25]
MARITAL RELATIONS OF PERSONS 65 YEARS OF AGE AND OVER IN THE ENTIRE POPULATION IN THE CENSUS OF PAUPERS AND IN PAUPER INSTITUTIONS.
The preponderately greater number of elderly widows is
also shown in a study of 100 aged persons in Greenwich Village,
made by Miss Nassau in 1915.[26] Of 65 women investigated,
Miss Nassau found 54 widowed, nine single, and two separated,
while of the 35 men interviewed, 21 were still married, three
were single, and two separated or divorced.
The Ohio Commission, in discussing this subject, states:
“In old age, marital condition, especially as regards women,
is very important. The woman who becomes a widow after 50 is
ill prepared to make her own living. She must, therefore, depend
on her children or on the property left her by her husband. If
her husband was a wage-earner, the most she can expect to inherit
is a little home. One hundred and sixty-six or 50.8 per cent. of
the 329 widows in the Hamilton survey owned their own homes.
While the children remain unmarried, they contribute to the maintenance
34of their mother, but after marriage she can no longer depend
upon them with any feeling of security. The single woman
who has had to make her own living is also insecure in her old
age. After 50 she finds it difficult to obtain steady employment
and her wages, as a rule, have not been such as to permit much
saving for old age. Only 37 of the 114 single women over 50 had
any savings.”[27]
“When aged persons who have been unable to save lose their
economic usefulness, they must depend on their children or relatives
or on public charity. Three hundred and fifty-four, old, or
invalided persons in Hamilton were dependent on children or relatives.
One hundred and fifty of these were dependent on married
children, all with families of their own; 144, on unmarried children,
and the remaining 60, on relatives. Forty-eight of the
416 aged persons studied in Cincinnati were dependent on their
children and 13 on other persons.”[28]
The Pennsylvania Commission found the marital conditions
of 3,477 non-dependent persons 50 years of age and over, as
follows: 5.4 per cent. single; 55.5 married; and 38.3 widowed.
It also found 37.8 per cent. who have no one depending upon
them; 31.5 having their wives to support, while the rest had one
or more children in addition to support. It concludes that:
“It is evident that the possession of children in old age is a
great protection against dependency. Thirty-one per cent. had one
or two children living; forty-five per cent. had from three to six
children living; while 12.7 per cent. had more than six children
living. Of those children, only 3.3 per cent. were still under 16
years of age; 16 per cent. of the adult children were married, while
80.7 per cent. were still single.”[29]
The marital condition of paupers is given by the 1910
Census as follows: 50.2 per cent. single; 32.5 per cent. widowed,
and 13.7 per cent. married. The 1915 Massachusetts Decennial
Census found the percentages of the marital dependents to be:
35single 19.0; married 24.7; widowed 54.4. In Ohio, 47.5 were
single; 37.8 married, and 10.9 widowed. In Pennsylvania 40
per cent. were single; 16.9 married; and 39.14 widowed. The
report of the last named Commission goes on to point out that
the single and widowed in the almshouses of the State constitute
nearly eighty per cent. of the total number of inmates. However,
the marital conditions of people over forty-five years
of age in the entire State, as given in the United States Census
for 1910, was: for males, single, 9.1 per cent.; married, 77.7
per cent., and widowed, 12.6 per cent.; and for women the
percentage for those over 45 years of age was, single, 10 per
cent.; married, 60.3 per cent., and widowed, 29.2 per cent.
The Commission adds:
“Some light may be shed on the problem of aged pauperism by
comparing the preceding figures with those obtained from the
house-to-house studies conducted by the Commission. In the latter
group the respective percentages are: Single 5.4 per cent.; married
55.5 per cent., and widowed, 38.3 per cent. These figures
would seem to indicate that the prime reason why the aged poor
cannot remain in their own homes, or in those of their parents or
close relatives is because, as a rule, most of these institutional
paupers have no one to fall back upon in their declining days.
Having no children of their own, their parents dead, and in many
cases, with few relatives, to be relied upon, these paupers seek
the institution as the last resort for shelter and nourishment. The
wide difference between the populations of single people in the
almshouses and those living at home, doubtless, explains why the
former are inmates of pauper institutions and the latter are classed
as non-dependent.”[30]
In Massachusetts in 1910, the proportion of inmates of
almshouses and of benevolent homes who had adult children
living at the time of entrance, was found to be nearly the same,
being 43.7 per cent. for the former and 39.4 per cent. for the
latter. On the other hand, the percentage of non-institutional
36poor, both public and private, who had adult children living
at that time, was higher, standing at approximately 60.
The Commission further states in its report:
“The number of almshouse and benevolent home inmates having
adult children or near relatives who are able to aid them at
present is, as one would infer, very small, namely, 7.7 per cent.
for the almshouse class and 13.2 per cent. for the benevolent
homes. Here the percentages are much higher for the non-institutional
poor, being 46.4 for the recipients of public relief, and
57.5 for recipients of private relief.”[31]
In 1918 in Ohio, Dr. John O’Grady states in the report of
the Ohio Commission:
“A study of the domestic relations of 2,260 infirmary patients
showed that 1,023 or 45.6 per cent. were never married. Those,
as a rule had no one on whom they could depend. Their parents
were dead, and brothers and sisters, even when in good circumstances,
cannot be relied upon to maintain a disabled brother or
sister. Of the 822 inmates who had been married, 605, or more
than half, had one or more children living; of these 232 had children
able to support them. The children of the remaining 373
were generally ordinary unskilled workingmen with large families
of their own. These could scarcely maintain their parents without
depriving themselves or their children of some of the necessaries
of life.
“About seven per cent. of the inmates studied were in the infirmaries
because their children, although in fairly good circumstances,
were unwilling to maintain them. In comparison with the total
infirmary population, this number may seem very small, but of
232 inmates with children able to support them only 88, or 37.9
per cent. had children able and willing to support them.”[32]
Also, in Pennsylvania, the Commission found further substantiation
of the isolation of the majority of the inmates who
37must avail themselves of the comforts of the almshouse.
“Sixty-three and fifty-one hundredths per cent. of those investigated
have no children living; 13.5 per cent. have but one child
living, while only 23 per cent. have two or more children living.
A comparison at this point with the same aged group studied in
the house-to-house canvasses is significant. In the latter group,
only 10.63 per cent. had no children living; 15.8 per cent. had
only one child, while nearly 70 per cent. had two or more children
alive.
“The data obtained with regard to the ages of the children
living shows that more than 13 per cent. of them are adult, indicating
that this aged group has few dependents. On the other hand,
89.93 per cent. of these children are reported as unable to support
their parents. The majority of these children are burdened with
large families of their own. Most of them also belong to the ranks
of the unskilled workers and earn wages which are hardly sufficient
to maintain their own families in comfort. Only a very small
percentage, namely 4.15, have children believed to be fully able
to support their parents, while an additional 6.86 per cent. are
able to help support the parents if ready to make the required
sacrifices.
“Nearly 95 per cent. of the aged inmates investigated, have no
other relatives able to help support them.”[33]
The degree of physical welfare and the capacity of maintaining
one’s grip upon life in old age, under our present industrial
conditions, may be gleaned from the following: Of the
non-dependent persons, just above the poverty line, 65 years
of age and over, investigated by the Massachusetts Commission
in 1910, 40.3 per cent. were found physically defective. In
Wisconsin in 1915, out of a total of 1,395 persons 60 years
of age and over, 489, or 35 per cent., were “able to follow gainful
occupation”; 493 others could do light work; 245 were
“able to take care of their own person;” and 42 required attendance.
38In Pennsylvania, in 1918, 36 per cent. of the aged 50
and over in the cities investigated were found to be physically
defective. Sixty-four per cent. of these were found to be still
in fair or sound health.
Quite a different tale is told by the investigations of the
dependent groups. Of the 57,049 paupers without age classification,
enumerated on January 1, 1900, in the United States,
15.4 per cent. were able-bodied, 40.5 were able to do light work,
and 44.1 per cent. were incapacitated. The Massachusetts
Commission found among almshouse inmates 93.8 per cent.
defective; the next highest percentage of defectives was 86.0
for recipients of State and military aid, and 82.7 for those
who received public outdoor relief. On the other hand, the
defectives among the non-dependent poor, as found by the same
Commission, was only 40.3 per cent.
The proportion suffering from chronic ailments among the
aged inmates studied in Wisconsin was also found to be very
high. Only one-third were found to be reasonably sound in
mind and body, and only 14 per cent. were able to work regularly,
while 12 per cent. required attendance.
A study made by the Ohio Commission from the reports to
the State Board of Charities, reveals, the Commission states:
“Nearly half, or 47.6 per cent. of the regular inmates of
county and city infirmaries are old and infirm and 24.5 per cent.
are sick and diseased or persons who have become disabled
through loss of members. More than 75 per cent. of the inmates
of county infirmaries in Ohio are, therefore, old and infirm, or
persons disabled by sickness, disease or accident. The remaining
27.7 per cent. is made up of miscellaneous groups of persons
with various defects.”[34]
A study of 2,260 persons representing the total population
of 22 typical infirmaries in Ohio made by Dr. John O’Grady
showed results somewhat different from the foregoing. Of the
392,260 cases, 830 or 36.46 per cent. were old and infirm; 305 or
13.4 per cent were defective mentally; and 1,106 or 49.77 per
cent. suffered from disease or physical defects.
The Pennsylvania Commission reports in regard to the almshouse
inmates:
“Of the 3,405 cases investigated, only 12.80 per cent. are reported
as being in good or fair health. Of those reported in
bad or poor physical condition 28.92 per cent. were in a general
state of poor health; 13.21 were crippled, maimed or deformed;
9.04 per cent. were feeble-minded; 9.3 per cent. were defective
in sight or hearing; 7.25 per cent. were rheumatic; quite a number
were epileptics and a number were suffering from various diseases.
Of the total number investigated only five per cent. were
reported as able-bodied; 40 per cent. were partially disabled, while
55 per cent. were totally incapacitated. For the same group in
the house-to-house studies, 64.3 per cent. are reported in good or
fair health, and only 35 per cent. are in poor health. In the
total pauper population of the United States in 1910, the percentage
of able-bodied was 20.64 per cent.”[35]
The Commission concludes:
“Regarding the aged paupers and the non-dependent aged
classes, the outstanding differences lie, it would appear, in the
respective family connections and physical conditions.”[36]
Of the 57,888 male paupers admitted to the different county
almshouses in the United States in 1910, 37.5 per cent. gave
their occupations as common and agricultural labourers. The
other occupations gave very small percentages each. The
Massachusetts investigation in the same year disclosed that
33.7 per cent. of the almshouse paupers were previously engaged
in manufacturing and mechanical pursuits, followed by
22.6 per cent. engaged in housekeeping and domestic service,
40and 14.5 per cent. who were recorded as common labourers. In
Pennsylvania, of 1,939 paupers stating their last occupation,
47.6 per cent. were classified as common and unskilled workers;
29 per cent. as engaged previously in housekeeping and domestic
service, and less than 18 per cent. were engaged in occupations
of skilled or semi-skilled character.
PERCENTAGE OF INCAPACITATED AGED PERSONS IN GENERAL AND PAUPER POPULATIONS.
Complete and exact information regarding the economic conditions
of the aged in the United States and the extent of incomes
outside of their earnings is not available. However, even
an examination of the meagre data available, discloses a distinct
insufficiency of incomes, outside immediate earnings, in
old age for the majority of wage-earners. According to the
Twelfth U. S. Census, only 847,069, or 27.4 per cent., of the
3,083,995 persons 65 years and over in the United States
owned their homes free, while 196,407, or 6.4 per cent., owned
them mortgaged. The 1910 Census does not give the home
ownership by ages. The latter enumeration does classify the
41owners of farm homes, however, by age groups. Thus, in
1900 the percentage of those 65 and over in the United States
who owned their own farm homes, to the total population of
that age, was about 16.3. But only about 15.1 per cent. of the
same age group owned their farm homes in 1910, and these
included both free and encumbered. At the same time, the percentage
of the rural population of the same advanced age constituted
57.2 per cent. in 1910.
HOME OWNERSHIP OF PERSONS 65 YEARS AND OVER—1900
The precarious economic status of the aged wage-earners and
the extent of their ability to support themselves in old age
becomes further manifested from the following disclosures:
The Massachusetts Commission’s investigations revealed the
economic conditions of the non-dependent aged poor in 1910
as follows:
WEEKLY INCOMES AND EXPENSES OF NON-DEPENDENT AGED POOR
Av. Income from All Sources
Av. Expenditure for All Purposes
Percentage of Those Receiving Income from Special Sources
From Savings
From Relatives
From Pensions
Individual males
$7.32
$6.26
36.1
36.1
15.5
Individual females
4.50
4.28
44.0
57.0
9.4
Couples
11.70
9.32
55.3
29.0
19.5
Families
12.24
12.00
58.7
12.4
32.3
Commenting on these figures, Mr. Squier points out:
“From the above table, it will be seen that the many thousands
of comparatively well-to-do aged people may, by the slightest slip
of luck or fortune, become absolutely dependent on charity.
With the average weekly income of $7.32 for males and $4.50 for
42females, an average expenditure respectively of $6.26 and $4.28 and
with such a large proportion of the incomes from sources other
than that of weekly wages, one can readily appreciate that it is
but a step from poverty to pauperism after the sixty-fifth birthday
is passed.”[37]
In Wisconsin the economic possessions of the aged, as found
by the Industrial Commission of that State, were found to be
as follows:
“Of the married couples 65 per cent. and of others 56 per cent.
owned homes mortgage free; of all home owners 65 per cent. have
property (including homestead) of more than $2,000; of non-home
owners 12 per cent. have property to the value of more than
$500; of married couples 60 per cent. have incomes from labour
or property over $300, and of others 40 per cent. have incomes
over $200 per annum.”[38]
Even more complete data is given by the Ohio Commission:
“Of the 1,432 persons studied in Hamilton, 525 or 36.6 per
cent. owned their homes free from encumbrance and 138 or 9.6
per cent. owned them mortgaged. Of the 416 persons studied
in Cincinnati, 98, or 23.6 per cent., owned their homes.[39]
“Of the 663 homes owned by the persons studied in Hamilton,
435 were owned by wage-earners or widows of former wage-earners
and 228 by business or professional men or their widows. One
hundred and ninety-six of the wage-earners owning their homes
were relatively skilled or semi-skilled wage-earners and 31.6 per
cent. of the total unskilled wage-earners owned their homes.”[40]
The commission further reveals that:
“Home owning was noticeably more common among immigrants
than among the native-born. Approximately two-thirds of the
Germans owned their own homes and among other foreign born
the proportion was almost as high. Among the natives of Ohio
every other person visited was a home owner, but among the
43natives of other states home owning was rare. The small number
of persons from other states owning their home is due to the
predominance of certain groups, already referred to, from the
backward districts of the south, whose members have not yet
acquired the art of saving.”[41]
The Ohio Commission’s investigations disclosed that one home
in every four of those studied at random was heavily encumbered;
65.2 per cent. of the latter were mortgaged for one-third
of their value, and 20 per cent. for at least two-thirds of their
value. Of the 663 home owners in Hamilton, 198 had in addition
property or some other means of income; out of the 769
non-home owners in the same city, 119 had property or other
means. Nearly 42 per cent. of the former and 67.2 per cent.
of the latter class had property or other source of income
valued at less than $500.
The Pennsylvania Commission in its studies of the aged in
the cities of Philadelphia, Pittsburgh, and Reading, found 38
per cent. having property possessions of one kind or another.
It also found 43.6 per cent. of the population 50 years of age
and over, who claimed to have had no other source of income
outside that of their own earnings. Of those that did have outside
means, 35 per cent. had incomes amounting to less than $10
per week. The incomes in 24.2 per cent. of these cases had come
from their own children, over seventy per cent. of whom were
wage-earners themselves. Of the people investigated the Commission
states: “The earnings of these aged workers in the
high wage period of 1918 were as follows: 14 per cent. earned
less than $12 per week; 29 per cent. more, from $12 to $20;
and 37 per cent. did not earn anything.”
The property possessions and earnings of the definitely
dependent classes are even less. The Massachusetts Commission
found the percentage of those having property above debt
at any time to be 37.8 for all classes of dependents.[42] The
44Wisconsin Report gives the home ownership of aged persons
who received outdoor relief during the fiscal year 1913–1914
as follows: Of 107 married couples only five had a home clear;
one had it mortgaged and 101 had neither; of 460 individuals
of both sexes 47 had their homes clear; 26 had them mortgaged,
while 387 had none at all. Only two of the married couples and
10 of the 460 other individuals had property exclusive of
homestead valued at $500 to $4,000.
The Ohio Commission in discussing the same subject concludes:
“Among the inmates of county infirmaries are to be found some
who were once prosperous; of the 1,608 persons studied 113 had
had property valued at more than $2,000, while 39 had had
property valued at more than $10,000.”[43]
The Pennsylvania Commission found similar conditions:
“Of more than 2,000 inmates questioned, as to their property
holdings, 191 or 9.5 per cent. claimed to have had property above
debts. More than 90 per cent. never possessed any property
of their own. At the time of investigation less than one per cent.
were receiving incomes from property holdings or savings.”[44]
The significance of these disclosures in terms of old-age
destitution, stand out so clearly that they need hardly be
commented upon further. The preceding data leave no doubt
as to the consequences of our present policy of aloofness. In
the face of actual destitution in old age, which now confronts
almost half of our industrial population, it seems hardly consistent
to continue to advocate and pride ourselves upon the
blessings of laissez-faire and individual thrift. The foregoing
would seem to indicate emphatically that the problems
facing the old are as real and difficult of solution by individual
effort in the United States as they have been found to be in
other countries. It is obvious that old-age dependency, whether
45of one form or another, is with us, and that the introduction
of a constructive social policy cannot be delayed much longer.
The investigations of the aged seem to show clearly that for
the wage-earner who has passed beyond the half century mark
the all-important decision whether he is to escape the poorhouse
in old age and a pauper’s grave at the end, does not altogether
depend upon his own desires and ambitions. This decision will
be made largely by the social forces which lie outside his own
control, namely, the extent and economic standing of his family
and his own physical vigour.
46
No social order can for long remain indifferent toward the
problems and difficulties confronting some of its members, without
directly or indirectly paying the price for its unconcern.
The cost of this apathy is difficult of estimation, as it is frequently
indirect and indistinct. A brief examination of the
facts, however, shows that the price paid by society for its indifference
is prodigious. For what is to many more distressing
and nerve-racking than actual suffering is the fear and dread of
such misery and privation. As Thomas Carlyle expressed it:
“It is not to die or even to die of hunger, that makes a man
wretched; many men have died; all men must die. But it is to
live miserably, we know not why; to work sore, yet gain nothing;
to be heart-worn, weary, yet isolated, unrelated, girt in with
a cold, universal laissez-faire.” It is a patent fact that public
pauperism in old age is the dread and agony of thousands of
workingmen and women. Many lives are embittered by the
fear of dependency in old age. Who can measure the extent of
depression of spirits, and the amount of physical drain accompanying
such depression and its loss to society in
terms of efficiency and progress? A brief examination of the
obvious costs is of supreme value.
(a) THE COST TO THE TAX-PAYER
The total cost of the dependent aged in the United States is,
of course, impossible to obtain. Not only are the records of
charitable institutions incomplete, but it is common knowledge
47also that millions of dollars are being given in one form of relief
or another by individuals, as well as by private organizations,
the extent of whose benefactions can never be ascertained.
Basing his estimate upon the average cost per dependent person
given by the Massachusetts Commission in 1910, Mr. L.
W. Squier calculated the total annual cost of the dependent
population 65 years of age and over, exclusive of those in
correctional institutions and insane asylums, to have been $178,899,968.41
in 1910. “In round numbers,” Mr. Squier estimated,
“it is costing this country $220,000,000 a year for the
support of this great host of worn-out toilers.”
The Massachusetts 1915 Decennial Census summarized the
per capita expenditures on the dependent aged 65 and over
in that State as follows:
“Exclusive of United States pensioners, the aggregate number
of dependent persons in Massachusetts 65 years of age and over
who received aid from all sources (both public and private) during
the fiscal year ending March 31, 1915, was 34,496 and the
aggregate amount of aid received by this number was $3,233,948.74.
Corresponding data for public relief were 26,403 persons
aided to the amount of $2,250,685.91 and for private relief
9,862 persons aided to the amount of $983,262.83. The per capita
expenditure on account of persons receiving aid from all sources
(both public and private) was $93.75; for persons receiving aid
from public sources, $85.24; and for persons receiving aid from
private sources $99.70. For males the per capita expenditure
(public and private) was $98.64 and for females $90.26.”[45]
In Wisconsin in 1914 the average cost per person of
almshouse maintenance, including interest on invested capital,
was $3.58 per week or $186 per year. The amount of outdoor
relief averaged $50 per person per year. The Ohio Commission
found that:
“Independent of the value of the farm products consumed in
48these institutions, the cost of maintaining the city and county
infirmaries in Ohio in 1915, was $1,455,944 and the average per
capita cost was $169.88. Of the 80 infirmaries reporting, 13 had
a per capita cost of less than $100; 27 between $100 and $149;
20 between $150 and $200; 15 between $200 and $250; four between
$250 and $300; and one over $300.[46]
“The total expenditure for poor relief by cities, counties and
townships was $1,966,352 in 1916. Other state institutions cared
for 37,139 different persons in the year ending June 30, 1917.
Nearly half of these persons were over 60 years of age. During
the same year expenditure on these institutions was $5,247,327.
“In addition 46 private, church and society homes were caring
for 2,628 aged persons in June, 1917.
“The state has an investment of over $25,000,000 in its state
institutions. The cities and counties have an investment of
$10,000,000 in the county and city infirmaries alone. Altogether,
this public investment calls for an interest charge of nearly two
millions annually, to say nothing of depreciation.
“Roughly speaking, then, nearly $10,000,000 is expended
annually by local and state public charities and a large part of
this, probably about half, is for the care of the aged. The
amount expended by private organized charities for the care of
the aged and for all relief and social work amounts to several
million dollars annually.”[47]
Exceedingly interesting related data is presented by the
Pennsylvania Commission. It finds that in 1917:
“The average cost per week for all almshouses, was $5.87 or
$25.14 per month. In 1916, according to the report of the State
Board of Public Charities, the average per capita cost, when computed
in a similar way, was $5.09 per week or $21.81 per month.
It must be noted that the expenditures made during the year on
buildings and improvements, and the interest on permanent investments,
are not included, in most cases. It is impossible to ascertain
the value of the different institutions at the present time. It
is a well-known fact, however, that many of the larger institutions
49are worth millions of dollars. It is not unusual to find many
county almshouses occupying farms of several hundred acres and
building properties worth several hundred thousand dollars. In
the few institutions where big expenditures were made on buildings
and improvements during the year 1917, five per cent. added
for interest and depreciation increases considerably the per capita
cost.”[48]
It also found that:
“One county home with eleven inmates spends $6,655.60 or
$605.05 per year per inmate; while another County Home with
three inmates spends a grand total of $2,570.55 or $856.85 per inmate
per year. One almshouse is maintained solely for one inmate
and while the direct cost of him to the county was $110.26 there
was spent $240.25 or $2.17 per dollar, to deliver this money to the
inmate.
“In 1916, $4,449,108.20 was spent for maintaining 16,754 inmates.
This total increased to $5,114,307.15 which was spent in
1917 on 16,716 inmates.
“The average yearly per capita cost for 1917 was $301.68.”[49]
In the Benevolent Homes for the aged the Pennsylvania
Commission found that in 1917 a total of $485,441.78 was
being spent on 1,545 inmates, or a per capita cost of $6.03
per week or $25.83 per month. It also found “one institution
in which the weekly per capita cost amounted to $19.88,
while in another it amounted to $33.81.” The above averages
the Commission states do not include the interest on permanent
investment or depreciation. When these were added the Commission
found the average cost per inmate in these Benevolent
Homes to be $33.99 per month in 1917. There are practically
no figures available showing the money spent on the aged poor
by private charity organizations. However, a study of the
Philadelphia Society for Organizing Charity made by the same
Commission, disclosed that during the most prosperous 12
50months—between October 1917 and October 1918—the Philadelphia
Society alone spent $33,291.57 on 162 aged people, or
an average of over $200 per beneficiary. The extent of contributions,
given in a confidential manner, by private persons
as well as by churches and fraternal societies throughout the
country is, of course, impossible to ascertain.
It is obvious that the millions of dollars spent annually on
the care of the aged, whether through public or private agencies,
ultimately come out of the pockets of the taxpayers.
And the Pennsylvania Commission’s indictment of the administration
of these funds is applicable to many States. The
latter Commission states that its investigations:
“Disclose an exceedingly confusing and bewildering system of
management of our county poorhouses. Not only do many of the
officials connected with these institutions have little knowledge
of the problems involved in the care of the aged, but there is
obviously a laxity in the management of these institutions and
the distribution of the county funds. The state supervision of
these aged homes is insufficient, loose and hardly competent. Careful
records are kept in only a few institutions. There are no uniform
methods of accounting. Computations of costs are made in
almost as many forms and methods as the men making them.
Many of the per capita costs of almshouses given in the reports
of the Board of Public Charities do not represent the actual cost.
The latter do not include the interest upon the permanent investment
and, in many cases, do not include the value of farm products.”[50]
In his private business the citizen is continually making
further inquiries in regard to newer and more efficient methods
of management by means of which he may reduce his cost,
and increase his returns. To suggest, however, that the same
principle should be applied to national or State business is, unfortunately,
still considered by many to be the rankest of
radicalism. Yet what could be greater folly than to continue
51to spend these many millions of dollars without either an accurate
account of the expenditures or of the returns secured?
(b) THE COST TO THE INSTITUTIONAL
INMATES OR RECIPIENTS OF CHARITY
Of greater social importance than the mere expenditures of
the enormous sums of money cited in the preceding pages is
the degree of effectiveness and the adequacy of these methods
of aged relief in meeting the purposes desired. These methods
must be judged in terms of the quality of the services rendered
to those who are forced to seek assistance in return for the
funds expended. Even the present chaotic means of caring
for the aged, if they are at all to be effective, must not only
seek to relieve the immediate needs of the aged but must aim
also to prevent dependency and thus ultimately reduce the cost
of pauperism. Measured by these standards it may safely be
stated that the existing means of aged relief are ineffective,
inadequate and undesirable. The present methods of relief
are looked upon as degrading and are of a repugnant nature,
invariably resulting in the loss of self-respect in the individual
recipient and increased pauperism in the group. The stigma
of public charity is inseparable from the almshouse and public
outdoor relief as commonly administered, because of long custom
and deeply ingrained public opinion.
Francis Herbert Stead, who was connected with the English
workhouses for years, says in his book, “How Old Age Pensions
Began to Be”:
“I saw men who trembled for very age hawking trifles in the
streets, and tottering on through mud and sleet and icy wind. I
saw men slowly wither up, body and soul, under the blighting
sense that they were wanted nowhere, and a burden everywhere.
When he is forsaken,
Withered and shaken,
What can an old man do but die?
52“Only those who have seen it can conceive the misery of the
poor old fellow who finds that society has no longer any use for
him, who feels he is done with and done for. Many old men
come to me, with tears running down their cheek, imploring me
as if I were Almighty God to have pity on them and get them
work.—‘Anything, oh, anything, no matter what it is, to keep me
from the workhouse.’”
Another Englishman—John Metcalfe—declared:
“One of the sights which make life unbearable to me is that
of old men and women, who in a worse plight than the sturdy
beggar (who has the spirit to beg) are trying to get a scanty
living by doing any kind of little odd jobs. They know that life
must soon end for them, and they have one ambition left, the
ambition not to die in the workhouse.”
These conditions do not exist in England alone. In this
country too it has often been asserted by competent authorities
that insanity and suicide of middle-aged persons is
due in a large measure to the dread of old age. Even in the
United States there are, apparently, workers who would rather
enter the valley of the shadow of death than the loathed confines
of a poorhouse. In a brief period of two months the
writer’s morning newspaper reported the following two stories,
which need no further comment:
“AGED MAN DIES AS HE FACES ALMSHOUSE
“Camden, N. J., Feb. 28—Heartbroken because he had to go to
the almshouse, Jacob ... 78 years old, of this place, was taken
ill and died yesterday afternoon.
“Jacob, and his brother, George, 76 years old, lived and worked
together all their lives. They have spent their last declining years
alone together, with no relatives, at their home here. As age
crept upon them they found themselves unable to obtain work, but
they eked out their slender savings until the final penny was gone.
Arrangements were made to have them sent to the almshouse at
Blackwood, and the news was too much for the elder of the
brothers and he became ill. His brother went to the almshouse
alone.”
53“FEARING OLD AGE HE JUMPS FROM HIGH BRIDGE
“Cleveland, May 7.—Fear of losing his position because of his
age is said by friends to have been the reason for a suicide leap
today by Joseph H...., 60 who hurled himself to death from
the high level bridge to the street pavement 125 feet below.”
The almshouse, like most charitable institutions, leaves much
to be desired as a home for the aged. Even if the majority of
almshouses and charitable homes in the United States afforded
a fair degree of physical comfort, sanitation, good food and
humane treatment, it would still seem hardly fair to herd together
indiscriminately the worn-out honest workers, the insane,
the feeble-minded, the confirmed inebriates and the petty
criminals, as is done in most public poorhouses at present. The
actual conditions of the great majority of county and semi-private
institutions are far from ideal. The recent investigations
of the several State Commissions, as well as personal
observations, reveal that life in public almshouses is far from
inviting, not merely on account of the opprobrium of public
opinion, but because in addition life in these institutions is
exceedingly dull, depressing and restricted.
In practically all States the superintendents of the county
almshouses are as a rule political appointees. “The great
majority of these,” says the Pennsylvania Commission, “have
had no experience of this nature, previous to their appointments.
Many of the men connected with the management of
the almshouses are prejudiced and often without the rudiments
of an education. Where the superintendents are highly educated
men and trained—of these there are only a few—they
are as a rule powerless, and have no authority to make improvements
without the consent of the Poor Board or the
County Commissioners.”
Similar conclusions are reached by the Ohio Commission.
Regarding the actual conditions of the County Almshouse the
Ohio Commission says:
“The care of the various inmates in the county and city infirmaries
54in Ohio is a rather difficult problem, but it is one which is
not taken very seriously, as is evident from the conditions prevailing
in the 45 infirmaries visited in the course of this study. Thirteen
were in very bad condition, 19 others would not come up to
any reasonable standard, and the remaining 13 were in fairly
good condition.
“In three infirmaries among those in bad condition, new buildings
are absolutely essential for any improvement in the situation,
the old buildings being entirely uninhabitable. Persons employed
to keep the premises clean seemed more lavish in the use of disinfectant
than of soap and water. The inside of the buildings
was unclean and slovenly; the walls had not been painted in a
generation and no attempt had been made to repair cracks or other
defacements.
“Many old persons suffer from foul smelling disorders and
when a number of them congregate in small groups, the resulting
bad odor is very noticeable to a person unaccustomed to it. Lack
of attention regarding personal cleanliness, poor ventilation and
over-heating tend to accentuate the odor. In many of the buildings
inspected, sections occupied by the inmates were so foul smelling
that they were almost unbearable. The inmates frequently
were unclean, the beds dirty, the bed covers old and worn and
ventilation poor. Those who were unable to care for their physical
needs and demanded constant attention, had to depend on other
inmates for the most urgent wants. Often these improvised attendants
were feeble-minded or at least ignorant and inattentive.
In the entire group there was virtually no medical supervision.”[51]
Somewhat better conditions are described by the investigators
of the Pennsylvania Commission as having been found
in the larger institutions in the State; but even in these institutions
the Commission declares:
“There was no genuine homelike spirit. Most of the inmates
looked sullen and wore depressed and downcast mien. Practically
all were eager to get out of the place. Even in the best equipped
institutions there were no recreational facilities provided for these
55inmates. Except for a pack of cards, a game of checkers and a
few old magazines, there was nothing these aged could do to
keep their minds occupied and to prevent their nursing of grievances
and discontent. This feeling of depression is augmented
by the fact that in most Homes no attempt is made to segregate
the old people,—who have been compelled to go to the almshouse
through no fault of their own,—from the feeble-minded, and in
some cases even the partially insane. In many places they are
compelled to eat at the same tables and sleep in the same dormitories
with the latter groups. The inmates in most almshouses
are a very heterogeneous collection. They comprise insane,
feeble-minded persons and epileptics, blind and deaf mutes;
sufferers from chronic diseases, persons with criminal records;
prostitutes; mothers of illegitimate children, orphans and deserted
children.”[52]
Miss Nassau, after visiting the Homes for the Aged on
Blackwell’s Island declared:
“Perhaps the most striking thing of all is the horror of the
huge dormitories with the beds nearer together than in the usual
hospital wards. That people can sleep in such huge dormitories
so close together seems incomprehensible—for although the very
poor have never been used to the luxury of real privacy there is
a difference between sharing a room with two to four relatives—and
a room with a hundred or so strangers.... In spite of long
years of tenement visiting I could stand no longer the sight of
such depressed, hopeless, sad, vacant, wretched faces. All seemed
to live such a hopelessly monotonous life with no individuality or
scope for personal effort.... Of course people do get desperate
and commit suicide or try to do so. One of the nurses at
Blackwell’s Island said, ‘I don’t think I can stand it here much
longer, it is awful. I don’t wonder some of the old people wander
down to the river and get in boats and—well, sometimes nothing
more is heard of them!’”
While commenting favourably upon the regulations for cleanliness
and general hygiene, Miss Nassau states:
56“My last comment is on the lack of provision at both places for
the keeping of personal effects, which is a most serious defect.
“At Staten Island, in the dormitories the women had chairs by
their bedsides, so they practically owned a chair as well as a bed,
and the clothes on their backs. Think of the tragedy of owning
nothing more, when every human being has inherently a love of
acquisition of property, as is proved also in asylums for children,
where it is found that children pine away if acquisition of personal
belongings is denied them! I asked one of the heads at Staten
Island if the inmates could not have a locked tin box for personal
belongings, but he insisted that that would be a menace to the
general hygiene. I said, ‘But the boxes could be inspected regularly.’
To which he objected irritably, ‘There is no one here to
do such work. I am short of help as it is; besides the people here
are riff-raff, anyway.’ This statement I could not agree with at
all, for many of the inmates seemed very decent, respectable people,
and in the cottages where they were given liberty (entrance to the
cottages is rather by ‘pull,’ and perhaps to some especially deserving
ones) they looked very neat and nice.”[53]
In practically all States outdoor relief is given by the different
Poor Boards to persons either whose physical condition
does not permit their removal to the County Homes, or to
women with dependent children, temporarily in need, who are
physically able to care for themselves. Outdoor relief may
be given also to those who have some one to care for them
in their own homes, or it is given to those who while physically
able are in temporary need of relief. This form of relief is
usually dispensed through the County Poor Directors themselves
or through a clerk appointed by them. Cash is given
only in rare cases. Generally an order for groceries or merchandise
is given to merchants extending credit to the Poor
Directors. Of the constituency of these Boards, the Pennsylvania
Commission states:
“It is seldom that the county poor directors, county commissioners
57or other poor authorities have any definite knowledge or understanding
of the problems of poor relief. These bodies are generally
elected or appointed because of their political leadership in
their respective communities. The policies of rendering relief to
the poor are very often shaped in accordance with the political
fluctuations and whims of the particular localities. Few make
provisions for careful investigation as to the extent and need of
assistance or for supervision of those who receive relief. The
clerk of one County Poor Board, who dispensed more than $10,000
worth of goods in one year, frankly admitted that he had no
experience in this work. He was a machinist by trade and confessed
he knew nothing of the problem. He said that he rarely
investigated a case but that he knew he was supposed to ‘relieve
the needs of the poor,’ and furthermore, that there ought to be
a better method of conducting this poor relief system, but that
he held his job because of his political influence and that ‘it was
much worse with the Democratic clerk who preceded him in this
office.’”[54]
What are the actual returns made to institutional inmates
for the enormous expenditures cited above? The Pennsylvania
Commission has made a careful analysis of the quality
and quantity of food consumed in one typical county almshouse
of that state on the respective tables for inmates and
stewards. The general methods of caring for the aged may
be seen from the following: The almshouse studied had a
farm of 514 acres valued at $200,000, while the buildings were
valued at $250,000 more. The analysis showed that during the
year 1917 the inmates’ table consisted on the average of 313
persons, while the stewards’ table consisted of 32 persons. The
following differences in table fare were found: The amount
of butter consumed during that year averaged 7½ lbs. per
inmate and 30¾ lbs. per steward. The inmates averaged 28
eggs per year, while the stewards averaged 200 per year.
Sugar was consumed on the average of 22½ lbs. per inmate
and 32½ per steward. The average amount of milk consumed
58by the inmates during that year was 23 qts., while the stewards
averaged 101 qts. The average amount of chicken consumed
by the inmates was a little over one ounce per year, while the
stewards averaged ten pounds. The same proportion held true
of other foodstuffs. The Commission comments:
“The above is illuminating from the standpoint of the quality
and quantity of the foods consumed at the respective tables of
inmates and stewards. It is shown throughout that the coarser
foods are consumed by the inmates, while the better kinds, are
used by the stewards. This is significant when it is remembered
that many of the aged folks are continuously sick and need more
of the better foodstuffs.”[55]
(c) THE COST TO INDUSTRY
Much has been heard lately of the importance of increasing
production. The necessity for higher standards of workmanship,
newer devices, and more scientific methods of management
in order to increase the efficiency of the workers is now
dwelt upon by all industrial leaders. Innumerable devices
which would tend to stimulate a greater out-put by their
workers are suggested by business men. It is patent, however,
that a high degree of efficiency can be obtained only when one
is possessed of a mind that is cheery, hopeful, and more or less
contented. The reactions of mind upon body, in terms of
industrial efficiency, can hardly be over-emphasized. But as
long as the worker is left to grope with the problems of old
age individually, the wage-earner—especially the middle-aged
worker—can hardly be expected to maintain a happy state
of mind.
To many millions of workers in the United States today,
the future is a dark, unfathomable abyss in which hope, independence
and comfort have no place. Advancing age is looked
upon with great apprehension and dread even by many who are
engaged in the skilled trades. What with the unemployment
of old age, the high cost of living, and the numerous other
59vicissitudes of modern life, their meagre savings are soon exhausted.
Slowly, as the years advance, the thought of what he
is to face during the days when he is no longer capable of
working, robs the mind of the middle-aged worker of every form
of contentment and enjoyment of the present. The thought
of helplessness in the future gradually fills the life of a worker,
especially if he is already advanced in age, with a fear and a
feeling of fatalism which has a deadening influence upon everything
he does. The prospect of the poorhouse with its stigma
of pauperism, so detestable to the honest wage-earner, haunts
him like a dark shadow and saps every bit of his vitality. The
dreadful thought that after a lifetime of valuable service, he
will be compelled to give up long-cherished home ties and life
associations, to lose sight of the old home, to hear no longer
the sound of his loved ones’ voices, is constantly before him and
fills his life with bitterness. He knows that life must soon
end for him, yet he has one ambition left—not to die in a
poorhouse. And these reflections inevitably result, especially
to the sensitive and thoughtful worker, who cannot help dwelling
with horror on the dreary period of old-age imprisonment
which awaits him, in physical deterioration and the reduction
of physical vigour, which in turn increasingly affect adversely
his interest, efficiency, and contentment. Under these circumstances,
what opportunities are there for the conservation of
energy and the increase of production?
(d) THE COST TO THE YOUNGER
GENERATIONS AND TO SOCIETY
The present system of aged relief stands indicted not merely
because it is inadequate, incompetently administered, and destructive
of industrial efficiency. It must be called to account
chiefly because of the detrimental effect it has upon the future.
The present methods of caring for the aged necessitate a reconsideration
and a readjustment because of their evil results
upon the coming generation and upon society as a whole. For
60of greater social significance and more far-reaching importance
than either the money spent on the decrepit, or the treatment
received by those whose lives have been spent and whose hopes
of rehabilitation or restoration to society are slight, more
sinister than even the industrial inefficiency it creates, are the
effects the present methods of aged relief have upon great numbers
of the younger and especially middle-aged wage-earners.
It is now generally recognized that society ultimately pays
the price for all its apathy and resultant maladjustments.
From the first impression it would appear that while this truth
may be admitted, the price in the case of the neglected aged
would be reduced to a minimum. For the great majority of
the aged are rarely restored to active social participation, and
their effect upon society, whether for good or evil, would seem
to be nil. However, a closer observation reveals an intimate
relationship between the superannuated workers and the
younger generation with its children.
The data given in a preceding chapter show that, while aged
dependency is widespread in this country, most persons, despite
their poverty, succeed in avoiding either public or private
charity. Obviously, these do not all commit suicide upon reaching
old age, nor are many found actually starving on the
streets. Most of these aged folk, as shown in the preceding
chapters, are taken care of by their children or relatives. Indeed,
this is given by the Pennsylvania Commission as the chief
difference between those who remain “non-dependent” and
those who must seek the poorhouse as their sheltering place.
The studies of the different State Commissions show conclusively
that few children able to do so are unwilling to aid their
parents. On the other hand, it was found that in many instances
children were supporting their aged parents, against
great odds, either because of deep attachment to them or because
of pride, which would rather suffer in silence than accept
charity. While this may seem a very meritorious act, to those
who consider it an obligation for children to support their
61parents, or who take it as indication of the much-prized family
solidarity, it can hardly be accepted as a desirable basis of
society, under present conditions, that the older generation
must be supported by the younger.
The younger generation must be considered in any discussion
of the aged problem, especially if it is to be accepted that the
aged are to be supported by their children. The proverbial
“mother-in-law” is undoubtedly blamed for many more things
than she is actually guilty of. Nevertheless, there are few
persons who could not reflect upon one or more of their acquaintances
whose young lives have been made pitiably wretched,
and in some instances totally ruined, by the constant “pestering”
of an old father-in-law or mother-in-law. Such conflicts
are almost inevitable.
Romain Rolland’s characteristic Frenchman, Colas Breugnon,
faced with such a situation after a fire, bewails his misfortune
thus:
“I have lost everything in the world,” thought I. “My home,—the
house was full of dear memories,—and the hope of ever
having another of my own; all my savings, which it took me
years to get together, bit by bit, and which were so much the more
valuable to me, and worst of all, my independence is gone; for
now, of course, I shall have to live with one of my children, and
I don’t know which of us will hate it the most. It is the one
thing I have always been resolved against, as the worst that could
happen. There is no use telling me that I love them, and they
love me,—I know all that, but young people and old interfere with
each other, and it is natural and proper for a bird to sit on its
own nest, and hatch out its own eggs in its own way. Respect
for the old is all very well, or rather it makes a difficulty, for you
are not on an equality with people when you are obliged to show
them respect. I have tried to behave so that my five children
should not have too much respect for me, and I think I have succeeded
pretty well, but there must always be a distance between
us. Parents come and go in their children’s lives, like strangers
from a far country; there can never be perfect understanding
62from one generation to another, and too often there is, on the
contrary, interference and irritation.”
As a rule the old persons hate to feel dependent upon their
children. They suffer greatly from not being “able to make
their own dollar,” instead of accepting it from their children.
On the one hand, the old who for years have been accustomed
to be looked up to as the superiors and masters of the household
can hardly adjust themselves to a position of “added
burdens,” when they become dependent upon their children.
They find it difficult to give up their authority. On the
other hand, even loyal children begin to lose their respect for
parents who have become feeble, irritable, and burdensome. As
a result there is frequently great suffering on the part of both
the old and young generations, which sometimes ends disastrously
for the children.
In addition to the evil effects upon the second generation described
above, there is also the third generation to be considered.
It seems cruel to force any father or mother in this twentieth
century to decide between supporting old parents and contenting
themselves with a little less food, less room, less clothing,
and the curtailment of their children’s education; or sending
parents to the poorhouse or charitable agencies, accepting the
stigma of pauperism, and thus assuring themselves of more
food, more room, and more clothing, and a better education for
their children which would help them to become somewhat more
proficient workers. This is a difficult alternative, yet it is
certain that thousands of parents in the United States are annually
compelled to make such decisions.
Unfortunately for the children, the hateful odium of charity
and pauperism is so repugnant to self-respecting labouring men
and women that the decision, in the majority of such cases, is
made in favour of the passing generation. Thus the lack of
provisions for the old is often responsible for the stunted and
thwarted growth of the children. Because of the necessity
of supporting the aged, the children are frequently doomed to
63under-nourishment; and to a life in the midst of crowded and
unsanitary quarters. The children are compelled to leave
school early in life and join the ranks of the unskilled; to add
further to the already over-crowded industries and thus lower
the wages of their own fathers and other such workers. They
are doomed to physical deterioration early in life, and in turn
to aged dependency, in order that they may keep up the vicious
cycle. And this slaughter of the innocent brought upon the
altar of ignorance to the ostrich continues, because the majority
of the people in the United States still are afraid to lift
their heads from the sand. They dread to face and meet the
facts—as every other civilized country has already done—with
a constructive social policy, for fear that in doing so they
may be accused of “paternalism,” or “socialism,” or perhaps
“Bolshevism”!
PART TWO CAUSES OF OLD AGE DEPENDENCY — CHAPTER V INDIVIDUAL CAUSES OF OLD AGE DEPENDENCY — SUPERANNUATION AS A CAUSE OF OLD AGE DEPENDENCY — DEPENDENCY DUE TO WANING EARNING POWER — LACK OF FAMILY CONNECTIONS — SICKNESS AND INDUSTRIAL ACCIDENTS AS CAUSES OF AGED DEPENDENCY — CHAPTER VI THE CHASM BETWEEN THE COST OF LIVING AND WAGES — 1890–1900 — 1901–1904 — 1905–1907 — 1908–1909 — 1910–1913 — 1914 — WAR CHANGES IN WAGES AND COSTS OF LIVING — CHAPTER VII SOCIO-ECONOMIC AND MORAL CAUSES OF AGED DEPENDENCY — UNEMPLOYMENT — STRIKES — GENERAL MISFORTUNE — THE PART PLAYED BY MORAL CHARACTER
65
67
The causes that make for dependency in old age, like those
which make for poverty in general, are many and varied. The
forces which underlie the brutal sweeping aside of thousands of
wage-earners as decrepit and dependent, are ordinarily too
complex and of too heterogeneous a nature to permit of enumeration.
Some are due, doubtless, to congenital or hereditary
biological influences, some to physical environment and social
heredity, while others may be the result of the existing social,
economic, political, and perhaps even moral conditions. No
completely accurate classification can be made of the factors
and influences which go to make up human life, and which result
in the fortune or misfortune of the individual. What may seem
the effect of one particular cause may be so only in part. The
main cause may overlap and encroach upon one or more related
causes. It is especially difficult to classify the causes which
make for old-age dependency, as even first hand information
cannot be taken at its face value in this instance; for frequently,
where the mental grip of the aged upon life is loosening, many
things are complained of which may have little or no actual
basis for complaint. The division of individual and socio-economic
causes of old-age dependency made in the following
chapters must not, therefore, be taken to mean that they are
mutually exclusive. The classification is made largely for convenience
and on the ground that certain influences are more
closely related, and are affected by the individual, while others
lie largely outside of the individual and are more intimately
allied with and dependent upon the current social and economic
forces.
68
In any discussion of the causes of old-age dependency it is
important to state first the part played by feebleness and inefficiency,
naturally resulting from old age. The studies made
by the several State Commissions, as well as by many other
competent authorities reveal that old age as such is a comparatively
minor cause of dependency in later life. As was
pointed out before, the present problem of old age is due largely,
not to the total incapacity or feebleness on the part of the aged,
but rather to their inability to cope with the conditions under
the highly developed modern machine industry which finds less
need for expertness and experience and greater use for speed
and rapid production. As a result, the younger generation,
though less experienced, is continuously crowding out the older
and less efficient workers.
The small part old age, as such, plays in dependency may
be seen from the following: The Thirteenth U. S. Census’
pauper enumeration gives the percentage of aged and infirm
in almshouses as 32.1. The Massachusetts Commission in 1910
found the percentage of physical defect, due to old age,
among the aged poor 65 years and over, ranging from 17.2 in
the case of those receiving State and Military aid, to 35.7 in the
case of those receiving private outdoor relief. Of 133 cases
studied in Hamilton, Ohio, as to the cause of their retirement,
only 25 attributed it directly to old age. Among the almshouse
inmates in Ohio, of 1,608 cases investigated, only 90 or
5.6 per cent, attributed it to the same cause. In Pennsylvania
also only 33.9 per cent. among almshouse paupers, 47.6
per cent. among inmates of benevolent homes, and 25 per cent.
among the non-dependent aged 50 years of age and over were defective
because of old age. In a study of 5,000 dependent families
who came under the care of the New York Charity Organization
Society during the years 1907–1908, Professor Devine
69found only 11.98 per cent. who were dependent because the head
of the family was 60 years old or more.[56]
Closely associated with superannuation as a factor in dependency
is the decreasing earning power of those who have passed
their prime in life. It is commonly known that in many of the
larger industries the age of employment is set below the age of
40 and in some cases not above 35. As a result many workers,
who for one reason or another are compelled to leave the
occupations in which they were engaged for many years, cannot
be re-employed in the trades in which they have acquired
expertness and experience. These are compelled to seek new
employment more suited to their age, which invariably means
decreased wages. As a factor in dependency this is of utmost
significance, for it must be remembered that in spite of the reduction
in wages the expenditures of these persons for food and
rent, even under normal conditions of living costs, remain the
same, while the expenditures for medicines are increasing with
age.
The extent of the changes in occupation, with the resulting
decrease in wages among workers who have passed their prime,
may be judged from the following. The Ohio Commission
found in its studies of wage-earners in Hamilton, that many
men of weak physique who enter occupations like moulding,
blacksmithing and boiler-making, make the discovery that they
are not equal to the strain, after it is too late. These are
forced to seek new and lighter employments. Its intensive
analysis of the Census reports regarding ages and occupations
indicates:
“That there are certain unskilled occupations which old men
enter after they have been compelled to give up work in their
principal occupations. There is a striking preponderance of old
men in such occupations as those of janitor, city labourer, watchman
for cities, and boarding and lodging house keepers. Nearly
7024.8 per cent. of the boarding and lodging house keepers (male),
in the United States in 1900 were between 45 and 54; 21.8 per
cent. were between 55 and 64 and 15.2 per cent. were 65 and over.
Of the watchmen, policemen and firemen 21.9 per cent. were between
45 and 54; 14.0 per cent. were between 55 and 65 and 5.4
per cent. were 65 and over. Of the janitors and sextons 21.8
per cent. were between 45 and 54; about 17.9 per cent. were between
55 and 64 and 9.7 per cent. were 65 and over. In 1910,
52.0 per cent. of the janitors, 63.4 per cent. of the sextons, 41.3
per cent. of the city labourers, 65.7 per cent. of the city watchmen,
and 55.0 per cent. of the boarding and lodging house keepers
were 45 and over.”
The foregoing, concludes the Commission, shows that:
“Many workingmen are compelled between 50 and 60 to leave
trades which impose a severe physical strain.”[57]
Comparisons of wages earned in old age with those earned at
lesser ages bear out the relationship of old age to decreased
earnings even more clearly. According to the findings of the
Massachusetts Commission in 1910, of all aged classes investigated,
the earnings at the time of investigation varied considerably
from their earnings in the last occupations. While 31.3
per cent. were found earning above $10 per week, at the time of
investigation, 49.9 per cent. were in this wage-earning group
during their last occupations. The percentage of those who received
below $10 a week was 50.1 during their previous earnings;
while 68.7 per cent earned below this sum at time of investigation,
or just prior to their admission to the various institutions.
Valuable information regarding the wages earned by paupers
in old age, just prior to their admission to an institution, and
in their earlier days is also supplied by the Pennsylvania Commission.
It comments:
“While 32.30 per cent. of the almshouse inmates earned less
71than $8 per week in their earlier years, a greater number, or 44.12
per cent. were earning the same sum prior to their admission. On
the other hand, while 61.07 per cent. were earning between $8 and
$20 per week in their younger days, only 52.48 per cent. were
earning the same amount at the time of admission. This would
prove that the earning power of these inmates was gradually
declining, due either to old age or similar causes. The small
wages earned by the majority of the inmates also seem to show
that many of these aged folk could not earn a sufficient sum to
maintain themselves in comfort. Of those who reported their
last earnings 21.33 per cent. earned between $12 and $20 per
week and only 6.4 per cent. were making $20 or more a week.”[58]
In the discussions of family connections (Chapter III),
it was seen that aged dependency and pauperism are almost in
inverse ratio to the number of children or relatives. Indeed,
the presence of large numbers of childless persons in our poorhouses
indicates clearly the connection between abnormally
deficient family relationships and pauperism. In a total of
44,433 female paupers enumerated by the U. S. Census of
1910, only 30.9 per cent. had children still living. In Pennsylvania
also, the Commission found, that while 63.5 per cent
among the almshouse paupers had no children, in the case of
those classified as “non-dependent aged,” only 10.6 per cent.
had no children living.
Very closely related to, and constantly attendant upon, aged
dependency is physical disability resulting from either accident
or bad health in general. It is common knowledge among social
and charity workers that ill health stands out as the largest
factor in all causes of dependency. It is conservatively estimated
that in at least 50 per cent. of the families who apply
72for aid, physical disability, either directly or indirectly, constitutes
the paramount cause for relief. The problem of old
age is largely a problem of sickness and invalidity. This fact
is generally recognized in European countries where old age
insurance is frequently operated in conjunction with health
and invalidity insurance systems. In these countries there are
usually more persons receiving invalidity pensions than old age
pensions.
The extent of sickness as a cause of dependency among the
aged may be deduced from the following official studies. The
U. S. Census enumeration of almshouse paupers in 1910 discloses
that “Of the 84,198 paupers enumerated in almshouses
on January 1, 1910, 53,619, or 63.7 per cent., were reported
as having some serious physical or mental defect.” The Massachusetts
Commission in 1910 found in its almshouse population
only 12.5 per cent. able-bodied persons and the general percentage
of physically defective ones for all classes was high (72.2).
Of the conditions in Ohio, Dr. John O’Grady concludes:
“These figures, as well as the general observation of the investigators
during the course of the study, seem to indicate that sickness,
disease and accident are important factors in shortening the
period of man’s economic usefulness. Many of the workers interviewed
stated that they began to fail after 50. Machinists and pattern
makers complained of defective eyesight and the molders of
rheumatism. As a rule they paid little attention to these disorders
until there was a breakdown compelling them to give up work for
two or three months.
“Illnesses were more important than any other cause in bringing
about premature superannuation and frequently required the
expenditure of all previous savings.
“There was every indication that for many wage-earners over 50
in Hamilton, the problem of sickness was really serious. The maladjustments,
neglects and excesses of early life were then making
themselves felt. One hundred and fifty-five of the men interviewed
reported themselves as afflicted with definite disorders of
various kinds, such as rheumatism and kidney, bladder and stomach
73troubles. These ailments, accentuated by age, frequently compelled
them to be absent from work for two or three months at
a time.[59]
“Of the 2,260 infirmary inmates of whom a detailed study
was made, it was possible to obtain information in regard to
the most important cause of poverty in 1,608 cases. Disease,
sickness, or accident was given as the most important cause of
dependency in 482, or 29.9 per cent. of the total number of
cases.”[60]
Sickness was also found to be the leading cause of disability
by the Pennsylvania Commission. This cause was given by 34.5
per cent. in the case of the almshouse group; 36.2 among Benevolent
Home inmates and 47 per cent. among the “non-dependent”
aged.
The part played by physical disability in old-age dependency,
however, is not confined to the actual period of senility.
Indeed, illness and poverty are all too closely inter-related
throughout our social system. It is very often difficult to
determine which comes first. The Social Insurance Commission
of California found in a study of 500 families who received
public aid, that there were many family heads who had been
earning considerably more than the average wage, but who
were, nevertheless, compelled to ask for aid because of sickness
which had consumed the savings of years.
That sickness encroaches upon the small property possessions
of the poor and succeeds in ultimately wiping them out,
is clearly brought out by the investigations of at least two
State Commissions. Of all dependent groups investigated by
the Massachusetts Commission, 60.1 per cent. of those who had
property in their earlier days attributed its loss to prolonged
illness. In Pennsylvania 35.5 per cent. of the almshouse paupers
and 88.3 per cent. of the “non-dependent” aged claimed
to have disposed of their previous property possessions in
order to meet emergencies, largely those of sickness.
74The relationship of bad health and dependency is indeed of
such importance that a summary of some of the data gathered
by the most recent State Commissions on Health Insurance
is exceedingly valuable in this discussion.
As early as 1900, the National Conservation Commission in
its report on national vitality declared that one rarely finds
a person past forty-five years of age who is in perfect health.
Since that time this broad statement of ill health has been corroborated
by many studies of health conditions as found among
different groups of workers.
“In an intensive physical examination of garment workers in
New York City, made by the United States Public Health Service
in 1914–15, it was found that among 2,086 males examined,
there were present 9,541 defects and diseases, or an average of
4.57 for each male. The examination of 1,000 females showed
3,916 defects and diseases, or 4.33 for each female.[61]
“Our knowledge of morbidity among the general population has
been increased during the past few years by the surveys made by
the Metropolitan Life Insurance Co. Surveys among the industrial
policy-holders of this company have been made by the agents
and have covered Rochester, N. Y., Boston, Mass., Kansas City,
Mo., cities of West Virginia, cities of Pennsylvania, North Carolina,
Trenton, N. J., and the Chelsea district of New York City.
A total of 579,197 white men, women and children were covered
and 10,878 were found unable to work, or 18.8 per thousand.
A total of 376,673 people over 15 years of age showed 8,636
cases of disabling illness or 22.9 per thousand. The average disabling
sickness for each of the persons of working age was, therefore,
8.4 days or 6.9 working days per year. When the data
for disabling illness are classified according to sex, they show
that white males over 15 have a morbidity rate of 22.8 per thousand
and white females over 15 have a rate of 23.0 per thousand.
These sickness rates represent an average total loss of 8.3 days
a year for men and 8.4 days per year for women. If these rates
are applied to the population over 15 in Ohio (3,700,000), it gives
75an annual total of 31,000,000 sick days and a loss of 25,000,000
working days per year.
“The United States Commission on Industrial Relations estimated
upon the basis of an examination of sickness statistics of
more than a million workmen, that each industrial worker loses
an average of nine days a year. This estimate is approved by
Warren and Sydenstricker in their report on health insurance for
the United States Public Health Service.
“The experience of nine benefit funds, in Ohio, covering
663,163 workers and 131,921 cases of disability which lasted
eight days and over and which were due to sickness and non-industrial
accident was examined. The analysis showed that for every
100 members, there were 19.7 cases of disability lasting eight
days and over. The average number of days’ disability per member
per year—based on these cases, exclusive of days of disability
beyond 189 days—was 6.0 days. In the Workmen’s Sick and
Death Benefit Fund which was analyzed separately, it is estimated
upon the basis of compensated cases of disability lasting
more than one day—exclusive of days of disability beyond one
year—that each member was compensated on the average of 6.9
days of disability a year. Since these figures are for compensated
cases only and do not include days of disability beyond the
specified ranges, they are, therefore, somewhat less than the total
sickness among the groups studied. From the mass of data all
pointing to the same conclusion, the Commission estimates that
for the whole group of employed workers in Ohio the average days
of sickness will be about nine days annually.[62]
“Among the 663,163 workers under observation, there were
131,921 cases of disability lasting eight days or over, or 19.7 cases
for every 100 members. Of the cases lasting eight days or more,
34.7 per cent. lasted from eight to 14 days; 19.5 per cent. lasted
from 15 to 21 days; 11.3 per cent. lasted from 22 to 27 days;
7.9 per cent. over one month but less than two months; 6.4 per
cent. over two months but less than three months; 7.1 per cent.
over three months but less than six months and 3.1 per cent.
over six months.”[63]
76In Dr. Emmet’s study of the Workmen’s Sick and Benefit
Society,[64] already referred to in a previous chapter, the average
age of the members of this organization, composed largely of
wage-earners, was 42.9 years. The total membership and the
total cases of disability due to sickness and injuries of these
were found as follows:
EXTENT OF DISABILITY AMONG MEMBERS OF THE WORKMEN’S SICK AND BENEFIT SOCIETY
Year
No. of Members
Total Disability Cases
No. of Cases per 1,000 Members
No. of Disability Days among 1,000 Members
1912
40,294
10.791
267.8
4,920.6
1913
42,075
11.529
274.0
5,076.4
1914
42,821
11.231
262.2
5,636.8
1915
43,300
11.240
259.6
5,628.4
1916
44,188
11.870
268.6
5,528.4
Thus the total membership during a period of five years was
subjected to a disability extent measured by 43,885 sick persons,
disabled an aggregate of 1,223,324 days or an average
of 6.6 days per member and 28.1 days per disabled person.
The Pennsylvania Health Insurance Commission in its report
of 1919 concludes:
“More than 385,000 persons in the State are constantly suffering
from illness; approximately 140,000 from severe, and 245,000
from slighter illnesses.
“The average loss of working time among employés in the State
is at least six days each year because of sickness. In 1916, 3,025,071
working days were lost because of industrial accidents in the State;
sickness causes approximately five to seven times as much loss as
industrial accidents.
“At the nominal rate of $2.00 a day the wage loss to employés
of this State every year because of illness is at least $33,000,000.[65]
“A study of twelve well organized establishment funds, was made
during the summer and fall of 1918 by the Connecticut, Ohio, Illinois,
and Pennsylvania Health Insurance Commissions with the help of
77Mr. Boris Emmet of the United States Bureau of Labour Statistics.
The results of this study were tabulated by the Ohio Commission
in ten groupings. The benefit associations selected for study include
employés in the following occupations: railroad transportation, manufacture
of iron and steel products, textiles, steel mill, general foundry
work and letter carriers. The most important facts to be gathered
from this study relate to the duration of the illnesses for which
benefit had been paid. As most of the funds had a seven day
‘waiting period’ only cases of more than eight days’ duration were
used in the combined experience tables. Because of differences in
administration of benefits and hazards of the several occupations
represented, the proportions of cases of long and short duration
vary widely in the different funds. For instance, 55.73 per cent. of
the sickness in Fund No. 1 lasted less than two weeks, while in
Fund No. 10 only 16.1 per cent. was of this duration. In the ‘over six
months’ group, Fund No. 1 had 1.39 per cent. of its cases, while
Fund No. 10 had 5.24 per cent.
“Taking the combined experience of these funds, however, it
was found that 34.56 per cent. of the cases lasted less than two
weeks; 34.68 lasted more than a month, and 3.26 per cent. more
than six months.”[66]
The Connecticut Report of the Public Welfare Commission
in an examination of the disability experiences of 22 factory
Mutual Benefit Associations in that State also finds that:
“The average number of disability days per member per year
for the 22 associations taken as a whole is 4.9 days. Making
allowance for the fact that in these associations disabilities of
shorter duration than the waiting period and disability running
beyond the maximum benefit period are not reported, it is found
that on the average a workman is disabled approximately six days
per year because of non-industrial accidents and sickness. This
figure is the same as was disclosed by the investigation of the
Social Insurance Commission of the State of California.
78“The individual experience for one year of a concern which
employs approximately 1,200 females showed for this group that
the average number of disability days due to non-industrial accidents
and sickness per female employé per year was 17.2.”[67]
According to the American Labour Legislation Review for
December 1920 (p 232), the United States Department of
Labour estimates that 450,000,000 days’ time is lost every year
by 50,000,000 workers in this country on account of sickness.
The degree of physical disability in the United States as a
whole is told vividly by the military draft rejections for physical
defects. Of all the young men examined in the United
States by the draft boards 29.11 per cent. were rejected on
account of physical defects.
The responsibility of industrial accidents for a great deal
of poverty and dependency is known to all. The exact number
of industrial accidents occurring in the United States annually,
however, is still impossible to determine. Even the best State
compensation laws include neither all classes of workers nor
all hazards, and no complete statistics of accidents are therefore
available. For the year 1913 the U. S. Bureau of Labour
Statistics[68] estimated the probable approximate number of
fatal industrial accidents in the United States at 25,000 for
both sexes, and the number of injuries involving a disability
of more than four weeks at approximately 700,000. This
estimate of comparatively prolonged disability was obviously
no indication of the total number of minor accidents which
occurred during that year. In a study of 10,000 accidents in
the iron and steel industry involving disability of one day and
over, made by the same Bureau,[69] it was found that in 41.2
per cent. of the cases the disability terminated in the first
week; 59.8 per cent. of the total cases terminated in two weeks,
while 77.7 per cent. recovered in four weeks. If the accidents
in the iron and steel industry are taken as representative of
79industry in general, in the United States, in respect to the
period of termination, it would mean that the total number of
industrial accidents in the United States approximate 4,000,000
a year.
Miss Margaret Gadsby in a recent study of industrial accident
statistics in the United States[70] points out succinctly the
deplorable inadequacy of complete data on this subject:
“How many industrial accidents occur yearly in the United
States? We do not know. To what extent have workmen’s compensation
laws and the safety movement mitigated the accident
evil in American industries? We are unable to determine with
any degree of certainty. What are the causes of industrial accidents?
What is the accident frequency rate in the leading industries;
the accident severity rate? We do not know. Where can
preventative measures be most effectively applied? It has never
been adequately determined; there are no adequate comparable
data. How many industrially disabled are there in the country
who will be affected by the recent legislation extending the provisions
of the rehabilitation act to the industrial cripple? No
authoritative statistics are available. What is the annual loss
in productive efficiency through industrial accidents? What is
the annual cost in time and money lost through accidents in industry?
We do not know; there are no figures available by
which it can be determined.... Even the part of this information
which is the most elementary—the mere number of accidents
occurring within a given year—is unavailable for the country
as a whole. Not only is there no uniform method of tabulating
statistics of accidents for the entire country, but also few States
can be said to have accurate knowledge of the total number of
accidents occurring in the industries within their borders. As for
an analysis of such accidents as to cause and severity within each
industry, only half a dozen States can be said to have approximated
a significant analysis.”
From a study of all the available sources of information
which, Miss Gadsby states, “can in no case be said to represent
80the total number of accidents occurring within the State,”
she presents the following industrial accident figures for the
years 1917–1918–1919.
Year
Fatal Accidents
Non-Fatal Accidents
1917
11,111
1,398,151
1918
12,082
1,569,771
1919
9,963
1,170,384
The above totals, as was pointed out, are incomplete. From
several states no figures whatever were available for the period
covered. In four instances, the figures refer to accidents in
mines only. In some cases only accidents resulting in more than
two weeks’ disability are included, and in one case the data
refer only to such accidents occurring in establishments where
women and children are employed. In addition, the investigator
contends: “A State that has a seven day waiting period
has no record of approximately 40 per cent. of its tabulatable
accidents. Those States having a waiting period of two weeks
have no record of from 65 to 70 per cent. of their industrial
casualties.”
After a thorough analysis of European and American industrial
accident rates, Rubinow concludes:
“That there occur in the United States annually some 30,000
fatal industrial accidents, about 200,000 accidents leading to permanent
disability, of which nearly 60,000 are cases of actual loss
of part of body, and about 100,000 resulting in disability of under
25 per cent. and another 50,000 in disability of 25 to 50 per
cent., and the remainder cause disability of over 50 per cent.
In addition, some 170,000 accidents are serious in that disability
lasts over three months, but eventually they result in complete
recovery, especially, if economic conditions favour it.”[71]
A recent pamphlet issued by the Metropolitan Life Insurance
Company declares that the United States leads all other countries
“equally advanced industrially and socially” in industrial
deaths. It is stated that there are “not less than 85,000
81deaths from accidental causes each year in this country. If
our accident rate were reduced to that of England and Wales,
we should have only 44,000 deaths from accidents.”
R. W. Little of the Safety Institute of America, referring
to the 2,000,000 industrial accidents in the United States every
year, points out that each of more than 700,000 industrial
workers loses more than four weeks every year as a result of
industrial accidents; that there are at least 22,500 industrial
deaths annually in this country, and that our industries turn
out each year 15,000 workmen suffering from permanent disability—“battle
casualties of peace.”[72]
The above estimates are hardly exaggerated. In the State
of Massachusetts alone, whose population was less than three
and one-half millions in 1910, there were reported to the Industrial
Accident Board of that State, the following number of
injuries:
The New York Industrial Commission found that from July
1, 1914, to Jan. 1, 1916, there were 683 industrial accidents in
that State every working day. In other words, there were in
that State alone 315,000 industrial accidents in eighteen
months. According to the September, 1920, Bulletin of the
New York Industrial Commission there were during the year
ending June, 1920, 345,672 industrial accidents reported to
the above Commission. During the three-year period of 1915
to 1917 the total cases compensated in Wisconsin, including
both fatal and non-fatal accidents, was 40,980.[74] During the
year ending June 30, 1919, 18,448 cases of injury were reported
82under the Wisconsin law, while during the year ending June
1920, 18,441 additional cases of injury were reported.[75] In
California, the Industrial Accident Commission gives the total
number of accidents for the calendar year of 1918 in that State
as 104,767.[76] In 1919 the total increased to 108,947.[77]
In Pennsylvania the Department of Labour and Industry
Reports state that in 1916 there were 255,616 accidents of all
kinds. In 1917 the number decreased to 227,880. In
1918 there were in Pennsylvania a total of 184,844 industrial
accidents, 3,403 of which were fatal. In 53,783 or
29.1 per cent. of the cases, the injuries resulted in a loss of
more than 14 days, while in 127,658 or 69.1 per cent., the disability
lasted from two to 14 days. The total number of
days lost that year amounted to 2,767,471 and the wages lost
amounted to $10,286,872. In 1919 there were a total number
of 152,544 industrial accidents of which 2,569 were fatal.[78]
There were lost through accidents during the same year 2,053,277
work days in Pennsylvania, an average of 13.46 days lost
for each accident. The total wage loss through accident during
that year amounted to $8,756,697, or an average wage
loss of $57.47 for each accident.[79]
In 1920 the total number of accidents amounted to 174,979
of which 2,514 were fatal. The number of days lost was 2,442,219
and the wage loss amounted to $12,154,829.[80]
How staggering is the accident toll exacted by industries
may be seen from the following Pennsylvania figures. During
the five years—1916–1920—since the inauguration of the
Compensation Bureau of Pennsylvania, there occurred a total
of 995,863 industrial accidents, of which 14,108 were fatal.
83The total number of days lost amounted to 14,590,701. The
total wage loss amounted to $50,146,055.
The accident toll exacted by modern industries from the
wage-earners engaged in them, is also evident from the following.
The accidents in the metal mines in the United States in
1916 amounted to 48,237; 46,286 in 1917,[81] and 42,915 in
1918.[82] The number of coal mine fatal accidents were as
follows:[83]
Year
Number
1916
2,226
1917
2,696
1918
2,580
1919
2,309
1920 (first 8 months)
1,340
In the iron and steel industry from 1910 to 1918 the industrial
casualties were as follows:
The number of casualties on the steam roads in the United
States were as follows in 1917: Killed 10,087; injured 194,805.[85]
In 1918 the total casualties on the steam roads amounted
to 9,286 killed and 174,575 injured.[86]
That it is the poorest workers who are largely affected by
accidents is evident from the Fifth Annual Report of the Industrial
Accident Board of Massachusetts. This report analyzes
the accident cases for the year 1916–17 and finds that 65
84per cent. of the non-fatal injuries were in the $8.01 to $15.00
a week wage group. What effect this has upon the family is
further revealed from an analysis of the dependents left by 460
fatal cases in California in 1918, made by the Industrial Accident
Commission of that State. The 460 individuals killed left
a total of 817 persons who were completely dependent upon
them. Of this total 329 were wives whose average age was 37.6
years; 455 were children whose average age was 8.5 years,
while 33 others consisted of dependent parents and relatives
whose average age was about 65 years.[87] In Pennsylvania also
of the 995,863 total industrial accidents which occurred during
the period of 1916–1920, 582,609, or almost two-thirds of the
cases, were married persons. The total number of dependents
of the injured ones amounted to 802,236 during the five-year
period.
It is out of place to dwell here upon the tremendous price
which is being paid annually in human and economic values in
this country, largely as a sacrifice to greed and greater efficiency.
That the accident rates are declining in practically
all occupations is, of course, encouraging. The relation of
the above figures to dependency, however, is obvious. What
this annual hecatomb means in terms of destitution and mental
and physical suffering to the victims and their dependents permits
no estimation.
85
The wages earned by the labouring classes in the United States
are too intimately related to aged dependency and too important
not to require the most thorough and careful consideration.
It is all too frequently assumed that the lack of individual
savings for old age is an indication of thriftlessness and lack of
foresight of the wage-earner or his family. The plain
fact is that the prevailing standard or daily wage is
generally based upon the daily minimum needs, and permits of
little or no saving. Rarely is it taken into consideration by
either party to the labour contract in modern society that the
basis of the daily wage must make provision for such exigencies
as sickness, accident, disability and old age. Wage rates today
depend largely upon demand and supply, and when labour
is purchased as a commodity in the open market it is naturally
bought at the lowest possible price. Such a bargain obviously
takes into consideration only the essential and immediate needs
of the wage-earner and his family. Indeed, in determining the
wage scale it is as if, in respect to old age, both employer and
employé had accepted what has falsely been represented as
Dr. Osler’s theory, that men 60 and over have no right to
live. Under such circumstances it is really surprising to find,
as was disclosed in a previous chapter, large numbers of wage-earners
who have actually had savings that were swept away
by sickness and other misfortunes by the time they reached old
age. Indeed, an examination of available wage statistics seems
to show that the great mass of wage-earners in this country
have at no time received a wage which would enable them to
86procure the American standard of living set by students
government authorities as necessary to support a family consisting
of the father, mother and three small children with the
absolute necessities of life.
Prof. John A. Ryan in his book “A Living Wage” made
an exhaustive and careful study of the Census Reports of 1890
and 1900, as well as of numerous other statistical reports prepared
by the Federal and various State labour bureaus, regarding
wages and the cost of living during the last decade of the
nineteenth century and the beginning of the twentieth century.
His studies of the cost of living during that decade convinced
him that:
“The conclusions that seem to be abundantly justified by the
facts brought out may, therefore, be stated as follows: first, anything
less than $600 per year is not a Living Wage in any of the
cities of the United States; second, this sum is probably a Living
Wage in those cities of the Southern States in which fuel, clothing,
food and some other items of expenditures are cheaper than in the
North; third, it is possibly a Living Wage in the moderately
sized cities of the West, North and East; and fourth, in some
of the largest cities of the last named regions, it is certainly not
a Living Wage.”[88]
In addition to Professor Ryan’s estimate, the United States
Bureau of Labour in 1901 studied the incomes and expenditures
of 25,440 families whose average size was 4.88 persons. This
investigation showed that it cost at least $700 on the average
to support each of these families.[89]
After he had established his standard Professor Ryan then
made a further study of wage reports and taking his estimate as
the minimum basis, presented the following proportion of
underpaid workers in the different industries:
The important feature of the table, summarizes Professor
Ryan:
“Is the percentages, which may be taken as fairly representative
of average wage conditions in manufacturing and railway industries.
And the general level of remuneration in these two fields
is undoubtedly quite as high as the average of the other urban
occupations. It is to be noted, moreover, that these percentages
reflect the conditions of 1890 and 1900–1903, when wages were
about as high as they are at present (1905), fully as high as
the average of the last fifteen years, and higher than that of the
last twenty-five years.”[91]
During the same period, according to Streightoff,[92] the
yearly remuneration of the garment makers in 1894 in New
York ranged from $249.94 for knee-pants-makers to $402 for
cap-makers: and the male machine operators and handworkers
of Chicago earned on the average $430 and $325, respectively,
the average recompense of all male workers in the cloak-making
trades being $330.42. In 1900, in North Dakota, were 2,168
men investigated, whose wages averaged $535; Minnesota recorded
66,889 workmen at an average of $492; and Wisconsin
120,131, at $449. In the same year the average earnings of
88male cotton operators was $405.69 in Massachusetts, $243.34
in Georgia, $216.39 in North Carolina, and $207.58 in South
Carolina.
In analyzing the labour reports of the States of New Jersey
and Massachusetts for 1901, Streightoff found that 64.75 per
cent. of all adult male factory employés in the manufacturing
industries of the former State and 62.86 per cent. of the male
employés in similar industries in the latter State earned less
than $12 per week, or approximately $600 per year.[93]
A study of family incomes made by the Massachusetts Bureau
of Statistics of Labour in 1902 revealed that it cost on the
average about $800 to support each of these families, whose
average size was 4.8 persons.[94] In the same year also the New
York Bureau of Labour Statistics estimated that an income of
$10 a week, or $520 a year, was inadequate for a family living
in a city.[95]
From the 1902 reports of the Labour Bureaus, Streightoff[96]
found that 62.51 per cent. of the male employés in the manufacturing
industries in New Jersey, and 61.35 per cent. of
the male employés in Massachusetts earned less than $12 a week
or approximately $600 per year. The Indiana returns for the
same year showed the average earnings of pumpmen as $2.20
per day, while that of trappers who worked only 215 days in
the year was $1.13 per day. Professor Ryan also points out
that the Interstate Commerce Commission’s Reports for the
year 1903 revealed that 72 per cent. of the more than two
million railroad employés investigated earned less than $600
per year.
In 1904 Robert Hunter stated that:
“It was shown by the Massachusetts Bureau of Statistics that
89it takes $754 a year for a family of five persons to live on.
John Mitchell has said that a minimum wage of $600 a year is
necessary in the anthracite district for a worker with a family of
ordinary size. The New York Bureau of Labour considers that
$10 a week or $520 a year is inadequate for city workmen. A
prominent official of one of the largest charities in New York
City thinks that $2 a day, or about $624 a year, is necessary for
a family of five in that city.”[97]
From these estimates Hunter expressed the opinion that $624
was not too much for a family in New York City. “When one
gets below these figures,” he declared, “every dollar cut off
may mean depriving a family of a necessity of life, in times
of health even, and unquestionably in times of sickness.” But
in order to be thoroughly conservative he estimated “more or
less arbitrarily, $460 a year as essential to defray the expenses
of an average family,—a father, a mother, and three children,—in
the cities and industrial communities of the New England
States, of New York, Pennsylvania, Indiana, Ohio, and Illinois.”
“This estimate,” he concluded, “would approach very nearly
a fair standard for the poverty line; that is to say, if any
working-class family should be unable to obtain this wage, they
would in all likelihood be unable to obtain the necessaries for
maintaining physical efficiency.”[98]
One of the most extensive investigations of wages in the
United States was made during 1903–1904 by the United States
Census Bureau. This investigation covered 3,297,811 wage-earners
of whom 2,619,025 or 79.4 per cent. were men; 588,599
or 17.9 per cent. were women and some 90,167 or 2.7 were
children.
90
EARNINGS OF MALES, SIXTEEN YEARS AND OVER, ENGAGED IN MANUFACTURE IN THE UNITED STATES IN 1904[99]
Percentages
Weekly Wage
Number
Actual
Cumulative
Under
$3
56,346
2.2
2.2
$ 3
but
under
$ 4
57,597
2.2
4.4
$ 4
„
„
$ 5
87,739
3.4
7.8
$ 5
„
„
$ 6
103,429
4.0
11.8
$ 6
„
„
$ 7
161,940
6.2
18.0
$ 7
„
„
$ 8
196,981
7.5
25.5
$ 8
„
„
$ 9
207,954
7.9
33.4
$ 9
„
„
$10
343,812
13.1
46.5
$10
„
„
$12
409,483
15.6
62.1
$12
„
„
$15
450,568
17.2
70.3
$15
„
„
$20
385,647
14.7
94.0
$20
„
„
$25
106,046
4.0
98.0
$25
and
over
51,511
2.0
100.0
The accompanying table indicates that during the period
studied, over one quarter of the male workers were earning less
than $8 a week, or less than $420 a year; 46 per cent. earned
less than $10 a week, while over 70 per cent. or nearly three-fourths
were earning less than $15 a week, or $780 a year.
Ninety-eight per cent. of all wage-earners earned less than $25
a week. The average for all classes is $10.06, or approximately
$520 per year, the average for men being $11.16, for
women $6.17, and for children $3.46.
In the same year Streightoff made the following estimate of
the distribution of income in the United States derived primarily
from labour:[100]
Approximate number of males, 16 years old or over, employed in 1904
19,658,000
Number earning under $600 yearly, or under $12 weekly
12,738,000
Number earning $600, but under $1,000 yearly, $12 but under $20 weekly
5,315,000
Number earning $1,000 or more yearly, or $20 or more weekly
1,605,000
On the basis of the above data, Streightoff concluded that
in 1904 over 60 per cent. of the males, at least 16 years of
age, employed in manufacturing, mining, trade, transportation,
and a few other occupations were earning less than $624 per
annum, or less than $12 per week on an average. Summarizing
the official reports which he studied, Streightoff also shows[101]
that 46.5 per cent. of the Illinois miners earned less than $500
per year. He gives the percentages of adult males, exclusive
of officers, clerks and salaried persons, engaged in manufacturing
91in the same year, whose earnings were less than $12 per
week, as 62.35 in Massachusetts; 60.8 in New Jersey; 58.05
in Missouri; 31.15 in Illinois, and 67.95 in Wisconsin.
From an intensive study of the budgets of 200 wage-earning
families in New York City during the years 1903 and 1905,
Mrs. More concluded as a result of her investigations that “a
fair living wage for a workingman’s family in New York City
should be at least $728 a year or a steady income of $14 a
week.”[102]
According to the Census of Manufactures, the 4,244,538
men engaged in manufacturing in 1905 received an average income
of $533.95. Of 13,796 railway men in North Carolina,
in the same year, 11,295 were found to have averaged less than
$1.62 per day or $500 per year. In 30 Maine clothing factories
in 1905, 234 men investigated received wages averaging
$10.82 per week, while 1078 women earned a mean weekly wage
of $6.78. Of the adult males engaged in manufacturing industries
during the same year, 58.5 per cent. in New Jersey and
57.09 in Massachusetts earned less than $12 per week.[103]
In concluding his estimates of what constitutes a living wage
Professor Ryan states:
“According to careful studies and estimates made by several
groups of investigators in 1906, the minimum cost of decent living
for a family of moderate size was: in New York, $950; in
Chicago, $900; in Baltimore, $750; while the average for these
and several other large cities was $938.”
Professor Ryan, however, declares:
“The conclusion seems justified that at least sixty per cent. of
the adult male workers in the cities of the United States are today
(1905) receiving less than $600 annually.”[104]
During 1906, the percentages of adult male employés engaged
92in manufacturing industries who earned less than $12
per week were as follows:[105] In New Jersey, 57.49; in Massachusetts,
55.12, while in San Francisco, where wages have
always been higher, of all employés, including women and children,
in the same year 63.40 per cent. earned less than $12 per
week. In Indiana during the same year the earnings of railway
workers were found as follows: 1,870 conductors earned
an average of $1,084.93; 2,287 engineers averaged $1,284.69;
4,408 station men averaged $508.37, and 88,967 track men
earned $378.93 each on an average that year.[106] The 30,742
miners investigated in Illinois in 1906 worked only 189.6 days
during that year and earned on an average $480.82.[107] Of
9,679 men at work in cotton factories in New Hampshire during
the same year the average wage amounted to $417.31.
Little improvement occurred the following year. In 1907
of the adult male factory employés (exclusive of officers, clerks
and salaried men) engaged in manufacturing industries in New
Jersey, 54.5 per cent. of the total earned less than $12 per week,
while of those engaged in the same industries in Massachusetts,
51.64 per cent. earned a similar wage.[108]
Quite a large number of investigations regarding both minimum
standards required and wages actually received were carried
on during 1908. The United States Bureau of Labour estimated
that in Fall River, Mass., in 1908, the minimum standard
of living for an average family could not be less than
$484.41 per year. This standard the Bureau defined as follows:
“If the family live upon this sum without suffering, wisdom to
properly apportion the income is necessary. There can be no
amusements or recreations that involve any expense. No tobacco
can be used. No newspapers can be purchased. The children
93cannot go to school because there will be no money to buy their
books. Household articles that are worn out or destroyed cannot
be replaced. The above sum provides for neither birth nor death
nor any illness that demands a doctor’s attention or calls for
medicine. Even though all these things are eliminated, if the
family is not to suffer, the mother must be a woman of rare ability.
She must know how to make her own and her children’s clothing;
she must be physically able to do all the household work, including
the washing. And she must know enough to purchase with
her allowance the food that has the proper nutritive value.”[109]
The Bureau estimated that a fairer standard of living for
Portuguese, Polish and Italian families required at least
$690.95, and $731.99 for English, Irish and Canadian-French
families. This higher standard, the Bureau said:
“Will enable him (the father) to furnish them (his family)
good nourishing food and sufficient clothing. He can send his
children to school. Unless a prolonged or serious illness befall
the family, he can pay for medical attention. If a death should
occur, insurance will meet the expense. He can provide some
simple recreation for his family, the cost not to be over $15.60
for the year. If this cotton-mill father is given employment 300
days out of the year, he must earn $2 per day to maintain this
standard. As the children grow older and the family increases
in size, the cost of living will naturally increase. The father must
either earn more himself or be assisted by his younger children.
“But even this standard is by no means an ideal one. It does
not allow savings to meet the contingency of any unusual event,
such as lack of employment or accident to the father. It makes
provision for old age. It provides for culture wants only in
the most limited manner, viz., one paper costing $1 a year.
It provides elementary schooling for the children up to their
twelfth year only.”[110]
The Massachusetts Bureau of Statistics investigations during
94the same year showed that the average wage of all cotton-mill
employés in Fall River was only $447.40, quite below even
the minimum standard set for the same city.[111] The average
remuneration of all the 176,377 anthracite miners in Pennsylvania
in that year was $496.13, just above the lowest standard;
that of the bituminous miners averaged only $447; while the
average for all the employés amounted only to $458.29,[112] considerably
less than the minimum required. Of the male employés
engaged in factories, 56.7 per cent. in New Jersey and
51.70 in Massachusetts earned less than $12 per week.[113]
“In 1908 the railroads of the United States employed 61,215
firemen at an average per diem compensation of $2.64; 57,668
enginemen at $4.45; 43,322 conductors at $3.81; 114,580 other
trainmen at $2.60; 41,419 section foremen at $1.95; 299,448 other
trackmen at $1.45; and 46,221 switch tenders and crossing watchmen
at $1.78.”[114]
In the same year the New Jersey roads employed some 42,514
men at an average annual wage of $657.22, considerably below
the fair standard set for Fall River.
On the basis of numerous statistical reports of wages in
Massachusetts during 1908 furnished by the different State
Bureaus, Nearing concluded that:
“It may be fairly stated that no more than one adult male
wage-earner in every twenty employed in the industries of Massachusetts
receives, in annual earnings, for a normally prosperous
year, more than $1,000. On the other hand, more than one-third
of all the adult males are paid wages under $500; more than one-half
receive wages under $600; while nearly three-quarters receive
less than $700 annually.[115]
95In cotton goods, the leading Massachusetts industry, Nearing
found that wages were very much lower than in the State
at large, nearly three-fifths of all the adult male employés having
received less than $459 in 1908.
From budget studies made by Dr. R. C. Chapin in 1909,
the New York State Conference of Charities and Corrections
concluded that:
“It is fairly conservative to estimate that $825 is sufficient for
the average family of five individuals, comprising the father, mother
and three children under 14 years of age, to maintain a fairly
proper standard of living in the borough of Manhattan.”[116]
In 1909, Nearing made a study of wages in New Jersey similar
to that which he had made the year before of wages in
Massachusetts and found that:
“For the State of New Jersey at large, and for the five industries
employing the largest numbers of persons, it appears that
after deducting the known unemployment, between one-third and
one-half of the adult males received less than $500 in 1909; that
from one-half to three-fifths received less than $600; that about
three-quarters were paid less than $750; nine-tenths received less
than $950; while from one-twentieth to one-tenth received $950
or over. The wages of adult females were very much lower. From
three-quarters to four-fifths received less than $400; nine-tenths
were paid less than $500, while a vanishing small percentage
received an annual wage of more than $750.”[117]
A study of wages in the leading industries of Kansas in
1909, by the same writer, showed that while the industrial conditions
in Kansas differ from those in Massachusetts and New
Jersey, about one-third of the male employés in the car and
shop construction and slaughtering industries received less than
$500, one-half less than $600 and three-fourths received less
96than $750 per year. The proportion of females earning less
than $520 was exactly twice that of males.[118]
Nearing’s conclusions are fully borne out by official investigators.
The 1910 Census Reports give the average number
of wage-earners engaged in manufacturing in 1909 as 6,631,931.
The total amount spent in wages in those industries during
that year was $3,434,734,000. When this total is divided
by the average number of wage-earners the quotient is $517.91,
which was the average wage during that year and which is
below $10 per week.
The U. S. Department of Agriculture also gave the farm
wages during the year 1909. Farm labour by the day in the
lowest type of work averaged $1.71 in 1909, outdoor farm
labour with board averaged $1.43 a day, while the average
monthly wage for outdoor farm labour quoted for the year without
board was $25.46 or $305.52 per year.[119]
In 1910, after a most exhaustive study of wealth possessions,
Dr. Willford I. King estimated that 95 per cent. of the families
of the United States had incomes of less than $2,000 a
year; 82 per cent. had incomes of less than $1,200; while 69
per cent. were living on less than $1,000.[120]
An elaborate Congressional investigation of the iron and
steel industry in the United States, covering 172,706 employés,
found the wage rates per year as of May, 1910, as
follows: Eight per cent. earned under $500, 60 per cent. under
$750, 85 per cent. under $1,000, and 97 per cent. under $1,500.
The separate rates of the employés of the Bethlehem Steel Company
during January of that year were found to be less than
97$500 per year in one-third of the cases; less than $625 in two-thirds,
while only eight per cent. averaged $1,000 and over.[121]
The Census Reports also show that in 1910 the average number
of wage-earners engaged in mining industries was 1,093,286.
The total wages earned by them was $606,135,238. The average
wage secured when the total sum earned is divided by the
total number of workers is $554.42, or $10.66 per week.
The Federal Immigration Commission’s report of 1910 announced
that not one of the 12 basic American industries
paid the average head of a family within $100 a year of the
minimum for family subsistence, and two-thirds of the 12 industries
paid the family head less than $550 a year.[122]
From the exhaustive studies made by Streightoff of incomes
and actual expenditures in different parts of the country, he
presented for 1911 the following minimum of expenditures necessary
for a family consisting of a husband, a wife, a boy between
11 and 14, a child between 7 and 10, and a baby under
three. These expenditures obviously include only a minimum
of the most essential necessities:
Food
$297
Rent
100
Clothing
120
Fuel
40
Church and Other Organizations
20
Medical Attendance
12
Amusement
20
Miscellaneous
40
Total
$649
Mr. Streightoff concludes:
“The above would show that it is conservative to set $650 as
the extreme low limit of a Living Wage in cities of the North,
East, and West. Probably $600 is high enough for the cities
of the South. At this wage there can be no saving and a minimum
of pleasure. Yet there are in the United States, at least five
million industrial workmen who are earning $600 or less a year.”
98Streightoff then calls attention to the fact that:
“It will be remembered that 1,116,199 men engaged in manufacturing
alone are earning no more than $400 per annum, and
2,009,914 are receiving no more than $500. If all industrial
occupations are considered probably four million men are not enjoying
annual incomes of $600.”[123]
During the period of 1911–12 a number of wage studies were
brought out by the United States Department of Labour. In
the cigar industry studied in that period, of 3,615 males investigated,
three-tenths received a wage of less than $750, while
half of those studied earned wages under $1,000 per year.
Four-fifths of the 7,551 females investigated received a wage
of less than $750 per year.[124]
The Tariff Board made extensive investigations during the
same period of wage rates in the cotton industry. These
studies disclosed that in the North five per cent. and in the South
22 per cent. of the males 16 years of age and over in the cotton
industry received a wage rate of less than $250 per year. Half
of the employés in the North and more than four-fifths of
those employed in the South were paid at the rate of less than
$500 per year. The figures for women range much lower than
those for men.[125]
For the dyeing and finishing woolens and worsted industry the
Tariff Board reports that four-fifths of the male dyers earned
less than $500 and nine-tenths less than $700 per year.[126]
The wages of employés engaged in woolen, worsted and cotton
mills of Lawrence, Mass., in 1911 were similar to those
found by the Tariff Board. In that city half of the men
studied received wages below $500 while seven-eighths earned
less than $600. In the case of female employés more than
99four-fifths earned less than $500, while 94 per cent. received
less than $600.[127]
The U. S. Labour Department in its investigations in the
textile industry brought out similar results. In the cotton
industry three-fifths of the males and four-fifths of the females
received wages of less than $500 per year, while 99 per cent. of
the females and 97 per cent. of the males earned less than $750
per year.[128]
In 1911–12 the Oklahoma Department of Labour reported
that of 668 male wage-earners in the telephone and telegraph
industry 27 per cent. received less than $500; 78 per cent. less
than $750 and 95 per cent. less than $1,000 per year. Of the
1,143 female workers employed in the same industry 17 per
cent. were earning under $250, 96 per cent. under $500 and 99
per cent. under $750.[129]
A typical Chicago slaughter-house in 1912 paid 82 per cent.
of its employés less than 20 cents an hour. This company
worked their men on the average of 37½ hours in the week, and
this gave the 55 per cent. of the men who averaged 17 cents
an hour, an income of $6.37 a week.[130]
From reports compiled by the different State Bureaus of
Labour, Nearing found the following percentages of wages during
the years 1911–12:
In 1913 Nearing in his book, “Financing The Wage Earner’s
100Family” (p 97), concluded from his examination of numerous
reports and wage studies that:
“The available data indicate that a man, wife and three children
under fourteen cannot maintain a fair standard of living in
the industrial towns of Eastern United States on an amount less
than $700 a year in the Southern, and $750 in the Northern
States. In the large cities where rents are higher, this amount
must be increased by at least $100.”
A joint investigation carried on during that year by the Consumers’
League of Eastern Pennsylvania and the Department
of Labour and Industry of that State, showed that the wages
of women in Philadelphia department stores were as follows:
16.5 per cent. received less than $5 per week, 63.8 per cent.
more earned between $5 and $10 and only 3.2 per cent. received
$15 or over per week.
The year following Prof. J. H. Hollander, of Johns Hopkins’
University, estimated:
“That in order to maintain a decent standard of living in the
United States for an average family of five, an annual income of
$600 to $700 is insufficient; that $700 to $800 requires exceptional
management and escape from extraordinary disbursements consequent
upon illness or death; and that $825 permits the maintenance
of a fairly proper standard.”[132]
An even higher estimate during the same year (1914) was
set by the Bureau of Personal Service of the Board of Estimate
and Apportionment of New York City, which declared $845 as
the least minimum of subsistence for families of unskilled labourers
in that city. The New York Factory Investigating Commission
declared that $876 was the lowest minimum wage possible
for the year 1914.
The actual earnings during this period were found by the
101Pennsylvania Department of Labour and Industry in a study
of over 20,000 industrial establishments to have averaged $720
a year or $14.40 a week for all males—quite below the minimum
standard set. The average annual wage for all females
was $335, or slightly over $6 a week.
The total amount paid in wages in the States of Massachusetts
and Pennsylvania in the year 1914 amounted to $869,262,517.
The number of employés in these two States was 1,531,176
and the average wage per worker amounted to $568 per
year.[133] The New York State Industrial Commission, which
in that year began to compile figures of nearly 600,000 factory
and office workers, found that the average weekly wage for the
last six months of 1914 amounted to $12.48, which would give
an annual wage of $648.96 if employed fifty-two weeks in the
year.
In 1915 Lauck and Sydenstricker after a comprehensive
study of wages and costs of living stated that four-fifths of the
heads of families obtained less than $800 per year, while two-thirds
of the female wage-earners were paid less than $400 per
year. According to a statement of the Chamber of Commerce
of Akron, Ohio, the 30,511 workers engaged in the rubber industry
in that city received an average annual wage of $628 during
the year of 1915.[134] In the same year the Pennsylvania
Department of Internal Affairs, which keeps records of the total
pay-roll amounts and the number of workers employed in that
State, found that the average weekly wage per wage-earner
(exclusive of salaried and office workers) amounted to $581.68.
The New York Industrial Commission gave the average weekly
wage received in that State during the year 1915 as $12.85,
or $668.20 per year. The Final Report of the Commission
on Industrial Relations declared that it is certain that at least
one-third and possibly one-half of the families of wage-earners
employed in manufacturing and mining earn in the course of
102the year, less than enough to support them in anything like a
comfortable and decent condition.[135]
The weekly wages received during the year 1915 throughout
the United States in the various industries, have been compiled
by the Bureau of Applied Economics from the published
surveys of the United States Bureau of Labour Statistics.
These were found as follows in the different industries:[136]
Industry
Per Capita Earnings Per Week—1915
Boots and Shoes
$12.12
Cotton Finishing
10.54
Cotton Manufacturing
8.31
Hosiery and Underwear
7.75
Iron and Steel
11.76
Men’s Ready-made Clothing
11.92
Silk Manufacturing
8.99
Woolen Manufacturing
9.70
Car Building and Repairing
13.20
Cigar Manufacturing
9.33
Automobile Manufacturing
17.23
Leather Manufacturing
11.76
Paper Making
13.20
An analysis of the standard of living in the District of Columbia
by Professor Ogburn, for the Bureau of Labour Statistics
in 1916, led him to conclude that:
“An average family of man, wife and three children, of ages four,
six and eight years, in the District of Columbia in 1916 was in
debt if the annual income was less than $1,155.”[137]
During 1915–16 the average daily wage for males in many
Pennsylvania establishments reported by the Department of
Labour and Industry as working on war contracts was found
to be only slightly higher in 1916 than in 1914, $2.76 in the
latter year as against $2.40 in 1914. For females the rise
reported was from $1.11 to $1.30. The average daily wage of
males engaged in public service industries, such as street and
103steam railways, etc., was $2.55.[138] The average wage received
by all wage-earners in Pennsylvania as given by the Department
of Internal Affairs was $737.96 in the year 1916. Salaried and
office workers were not included in this tabulation. In the
rubber industry of Akron, Ohio, the average annual wage according
to the Chamber of Commerce of that city amounted to
$759 in 1916. The wages for that year as found by the New
York State Industrial Commission were very similar. The average
weekly wage was $14.43, or, if employed for fifty-two weeks
in the year, $750.36 per year.
The year 1914 may be considered a landmark for both wages
and costs of living. Since then money wages have increased in
all industries. Even greater, however, has been the rise in the
cost of living. Standards of living in terms of money wages
need therefore considerable adjustment, and a revaluation in
purchasing power. According to the Pennsylvania Health Insurance
Commission, the standard “minimum of subsistence”
budgets, estimated in 1914 as $845 by the Bureau of Personal
Service of the Board of Estimate and Apportionment of
New York City for unskilled labourers’ families; $875, the
estimate made by the New York Factory Investigation Commission
in 1914, and $900, the estimate by Dr. Chapin for a family
of five in 1907, became in June, 1918, $1,320, $1,360 and $1,390
respectively. Similar estimates for 1918 were made by the Commission
of the Interchurch World Movement in its Report on
the Steel Strike.
The Philadelphia Bureau of Municipal Research stated in
December, 1917, that the necessary minimum cost of healthful
living for a family of two adults and three children was $1,200
a year. But in the autumn of 1918 it found $1,636.79 as necessary
for a similar standard of living.
In November, 1918, the United States Bureau of Labour Statistics
104estimated that the minimum necessary for subsistence for
an average family in a large eastern city was about $1,500. In
the same year, the National War Labour Board drew up a “minimum
comfort” budget which amounted to $1,760 per year for
a family of five.[139]
It is interesting to note, that the above estimates regarding
the minimum budget necessary for subsistence, although showing
some variation as would be expected, do not show considerable
differences. However, in 1918 the United States Bureau
of Labour Statistics made an investigation of the budgets of
working families in a number of cities. The average actual
expenditures of these families per year in the different cities
investigated follow:
AVERAGE ACTUAL FAMILY EXPENDITURES IN VARIOUS CITIES
City
Number of Families Investigated
Average Persons in Family
Total Average Yearly Expense Per Family
Baltimore (white)
195
4.8
$1,260.96
Boston
407
5.3
1,438.13
Bridgeport, Conn.
143
4.6
1,540.24
Buffalo
256
4.6
1,460.00
Chambersburg, Pa.
77
4.9
1,241.90
Dover, N. J.
74
5.3
1,608.92
Fall River, Mass.
158
5.4
1,320.84
Johnstown, N. Y.
78
4.5
1,308.51
Lawrence, Mass.
109
5.3
1,504.67
Manchester, N. H.
112
5.2
1,370.83
Newark
147
4.7
1,445.41
New York
518
4.9
1,525.66
Philadelphia and Camden, N. J.
301
4.9
1,469.40
Pittsburgh, Pa. (white)
254
5.1
1,412.10
Portland, Me.
97
4.9
1,412.84
Providence, R. I.
158
5.3
1,303.18
Rutland, Vt.
80
5.1
1,264.29
Scranton
151
5.2
1,344.99
Syracuse, N. Y.
158
4.9
1,407.03
Trenton, N. J.
100
4.4
1,418.50
Westfield, Mass.
74
5.2
1,494.84
Wilmington, Del.
98
4.6
1,640.50
In summarizing the data, the Bureau found that of 12,096
105white families investigated in 92 industrial centres scattered
throughout the country comprising 4.9 average persons, the
average yearly expenses per family was $1,434.36 in 1918.[140]
In 1918 investigations of the Pennsylvania Commission
on Health Insurance the following data are given:
“In the Philadelphia Survey which covered 1,850 families in
seven districts in Philadelphia the average family income was but
$21.60 a week, and almost a third of these families contained over
five persons, the normal standard.”
“In the Visiting Nurse Study, 80.6 per cent. of the 438 families
had incomes of less than $30.00 a week. In the Sickness and
Dependency Study 94.3 per cent. of the families had incomes of
less than this amount.”
“Wages for women, proverbially lower than those for men,
proved in the Working Women’s study to be in 98.1 per cent. of
the cases under $25.00 a week; in 92 per cent. of the cases, under
$20.00.”
“In the Pittsburgh Factory Investigation, made in August–November,
1918, covering the work places of over 9,000 women, it
was found that in 70 per cent. of the operations the wages were
between $5.00 and $15.00 per week. In only two processes were
the weekly wages over $25.00.”
“In a study made by the Consumers’ League in New York in
1916–17 among 417 women working in steam laundries, it was
found that 78.3 per cent. earned less than $10.00 a week, and
almost half earned less than $8.00.”
“The Kensington Survey, which covered the most representative
industrial group, showed that more than half—56.6 per cent. of the
608 families had incomes under $30 a week, 42 per cent. were
living on less than $25.00 a week.”[141]
From July 1st, 1914, to April 1st, 1918, the wholesale prices
of 46 essential commodities given in Bradstreet’s showed
a rise of 115 per cent. According to the Bureau of
Labour Statistics, its study of the increase in the cost of living
106in shipbuilding centres in 1918, showed that the cost of living
for white families had risen 67.17 per cent. in August, 1918,
over the cost in December, 1914, in Philadelphia; in New York
it was 62.07 per cent. in December, 1918, over December, 1914.
While the cost of living and prices have thus increased from
60 to 115 per cent., a study of the rise in wages made by H.
S. Hanna and W. J. Lauck, led them to conclude:[142]
“That the rise in wages between 1914–15 and December, 1917,
or January, 1918, was only 18 per cent. for anthracite miners;
26 per cent. for machinists in the Philadelphia Navy Yard; 30
per cent. for bituminous miners working by hand, and 34, 36 and
37 per cent, respectively for shipbuilders, and pipe fitters in the
Philadelphia Navy Yard. The rise in the building trades was
12 to 20 per cent. The wages in some industries had actually
decreased, while some remained stationary.”
The Thirty-third Annual Report of Massachusetts on Statistics
of Manufacture states that during the year 1918 the
total disbursements in wages paid to labour amounted to $679,401,273.
When compared with the year 1913 the increase in
the total wages disbursed amounted to 93.4 per cent. However,
the average yearly earnings for all wage-earners without
distinction as to age, sex or skill which in 1917 were $758.23
per capita, rose only to $944.65 per capita in 1918. Compared
with 1913, when the per capita wage in manufacturing
industries was $569.43, the increase amounts to 65.9 per cent.[143]
During the year 1918, the average wage in Pennsylvania was
$1,213.54. In the rubber industries in Akron, Ohio, it was
$1,173 and in New York State $1,058.20—quite far below the
actual family expenditures during that year as found by the
United States Bureau of Labour Statistics in the different cities.
The Administrative Committee of the National Catholic War
Council in its Social Reconstruction Program in 1919 reached
107the conclusion that the average rate of pay has not increased
as fast as the cost of living. That this conclusion is fully justified
and that a considerable number of wage-earners, both men
and women, have not been receiving what is generally considered
a living wage, even during the time when money wages were
at their highest peak, is clearly indicated by the following recent
investigations, which throw some additional light upon the continuous
chase and struggle between increased prices and
increased earning power.
In 1919, the National Industrial Conference Board, an organization
composed of employers of labour, in an investigation of
the cost of maintaining a minimum standard of living for a representative
wage-earner’s family of five, reached the conclusion
that in Lawrence, Massachusetts, in order to maintain the lowest
standard, $1,385.79 was required or an average weekly income
of $26.65 the year around. A more liberal standard,
which would make no provision for savings except such as were
secured through insurance, was found to require a yearly expenditure
of $1,658.04, or a steady income of $31.88 per week.[144]
In August, 1919, the United States Bureau of Labour Statistics
in a study of budgets of government employés’ families
in Washington, D. C., set the standard necessary for the maintenance
of a family of five in that city at $2,262.47.
The extent to which wages have increased during the same
period is significant. The National Industrial Conference
Board has recently published a report analyzing the wage
changes in several important industries from 1914 to 1919.
The average weekly earnings of male employés in the specified
industries from 1914 to 1919 follow.[145]
The figures in several instances show actual decreases
between September, 1918, and March, 1919, and not a single
group earned the minimum wage necessary for the support of
108a family with the most necessary comfort as conservatively
estimated by the employers’ organization itself.
Industry
Sept. 1814
Sept. 1815
Sept. 1816
Sept. 1817
Sept. 1818
March 1818
Boots and Shoes
$14.70
$15.33
$16.50
$18.36
$24.04
$25.80
Chemical Mfg.
12.85
13.26
16.10
20.50
26.80
26.20
Cotton Mfg.
10.00
10.05
11.85
14.22
20.60
17.10
Metal Mfg.
13.18
14.80
17.22
20.08
26.80
24.75
Paper Mfg.
12.75
12.75
15.03
18.03
22.40
22.40
Rubber Mfg.
14.00
14.85
18.60
22.80
22.60
28.35
Silk Mfg.
11.77
12.66
14.10
15.50
21.54
22.68
Wool Mfg.
11.52
11.05
13.51
16.87
23.21
18.61
Early in 1818 the United States Bureau of Labour Statistics
conducted extensive wage studies in a number of industries
throughout the country. Some of its findings are presented
here:[146]
AVERAGE ACTUAL EARNINGS IN VARIOUS INDUSTRIES IN 1818
Industry and Occupation
Average Actual Earnings Per Week for Male Employés
Average Actual Earnings Per Week for Female Employés
Paper Box Mfg.
$18.40
$11.05
Women’s Clothing Mfg.
35.11
15.85
Confectionery Mfg.
18.45
10.08
Overall Mfg.
25.02
12.06
Cigar Industry
20.84
15.54
Men’s Clothing Industry
24.78
14.75
Hosiery and Underwear
20.80
12.88
Silk Mfg.
22.78
15.28
Brick Mfg.
20.00
Chemicals Mfg.
20.80
12.35
Glass Mfg.
22.66
18.38
Leather Mfg.
26.03
13.40
Paper and Pulp
26.47
13.44
Pottery Mfg.
26.60
13.37
Rubber Mfg.
27.04
14.85
Automobile Mfg.
25.87
16.88
Car Mfg.
26.78
Elect’l Apparatus Mfg.
25.53
15.30
Foundry Mfg.
26.28
12.66
Machine Mfg.
26.85
12.80
Machine Tool Mfg.
26.74
16.62
Typewriter Mfg.
26.77
14.67
109It is of interest to note that the above figures show that a
living wage was obtained in only one industry—the Women’s
Clothing industry—which is now thoroughly organized, and
which only a few years ago was one of the most underpaid industries.
The 1818 Industrial Survey made by the United States Bureau
of Labour Statistics covered 2,365 establishments, 28 industries
scattered through 43 States, 780 different occupations,
including a total of 404,758 employés. These investigations[147]
disclosed that of the 318,846 men workers, 151,725, or 47.5 per
cent., earned less than 50 cents an hour. As the average number
of hours per day was found to have been 7.6, at least half of
the male workers earned less than $22.80 per week. The average
weekly wage for all was $25.58.
In the case of the women workers, of the 85,812 persons investigated,
47,817, or 54.75, earned less than 30 cents per hour.
The average number of hours here was 7.5 per day, which means
that more than half of the female workers earned less than
$13.50 per week. The average weekly wage for all was $13.54.
The 1818 minimum wage standards for women workers in the
States that have established such were as follows: District of
Columbia (mercantile trade) $16.50; California $13.50; Washington
$13.20; Massachusetts (candy occupations) $12.50; and
Kansas $11.00. In 1818–1818, the wage investigations of the
Massachusetts Minimum Wage Commission showed that from
57 to 88 per cent. of the women workers investigated in five industries
in that State earned less than $11.00 per week. In
New York the minimum weekly budget set for a single working
woman in 1818 was $16.13. Studies of 500 working girls
chosen at random by the New York State and City Consumers’
Leagues early in 1820 showed that 443 or 88 per cent. of the
girls investigated received less than $16.00 per week. In spite
110of the increased cost of living in 1818, 28 per cent. of the
women investigated reported no wage increase during the same
year.[148]
In the same year despite the minimum wages established, the
United States Bureau of Labour Statistics found the following
weekly earnings of women from payrolls:[149]
Industry
Average Weekly Earnings
Glass
$10.12
Confectionery
10.25
Paper Boxes
10.88
Overalls
12.26
Hosiery and Underwear
13.04
That women workers frequently work for less than the
amount necessary for their maintenance has recently been
revealed from an investigation carried on in 1820 by the Industrial
Welfare Commission of Texas. The Commission investigated
2,028 women in 40 cities in Texas. The figures were
sworn to and represent actual expenditures on maintenance and
not estimates. A study was also made of the weekly wages of
13,311 employés as furnished by employers in these 40 cities.
The results are given as follows:[150]
Industry
Cost of Living Per Week
Average Wages Per Week
Telephone
$14.14
$12.31
Mercantile
15.44
12.88
Laundry
13.78
8.38
Factory
14.65
11.52
Average
$14.78
$11.88
In December, 1818, the Bureau of Labour Statistics published
a complete study of wages and hours of labour in the coal-mining
industry as found in the early part of that year. This study
included 551,646 workers throughout the United States. The
111actual earnings of these miners in the bituminous fields as
studied during one-half-month pay-roll by States is given as
follows:[151]
AVERAGE ACTUAL EARNINGS IN BITUMINOUS MINES IN ONE-HALF MONTH PAY-ROLL PERIOD BY STATES
State
Hand Miners
Machine Miners
Loaders
Alabama
$40.41
$45.88
Colorado
47.42
$73.73
50.65
Illinois
47.72
61.02
51.03
Indiana
36.47
55.78
40.02
Iowa
43.37
52.55
34.17
Kansas
42.75
Kentucky
34.38
58.62
40.42
Maryland
50.57
Missouri
36.42
43.27
42.86
New Mexico
52.12
36.45
50.80
Ohio
63.56
86.86
58.40
Oklahoma
53.82
50.66
48.58
Pennsylvania
57.48
72.02
55.21
Tennessee
34.08
26.25
33.36
Utah
57.66
82.07
57.85
Virginia
52.66
38.83
West Virginia
52.58
71.80
47.53
Wyoming
57.08
45.85
Total
$47.12
$67.58
$50.51
In the case of the anthracite miners, the average earnings
made in one-half month pay-roll period in 1818 are given as
follows: Inside occupations averaged $65.17 while those engaged
in outside occupations averaged $55.37 per two weeks’ pay-roll.[152] The figures presented by the operators to the Coal Commission
in 1820, and which were greatly disputed by the representatives
of the miners, showed that the average wage of 68,416
miners examined in 1818 was $1,422, but declined to $1,234.44
in 1818. The miners presented figures of much lower averages.
The Bureau of Labour Statistics also keeps records of the
changes in union wage scales. The year 1813 is taken as the
basis of the index and set at 100. Accordingly the rates of
wages per full-time week are presented as follows:[153]
112
1813
100
1814
102
1815
102
1816
106
1817
112
1818
130
1818
148
1820
188
Further compilations of increases in union rates of pay per
hour from 1814 to 1818 in the building trades in about 30 cities
in the United States were made by the Bureau of Applied Economics.[154]
The increases received as given by the international
unions concerned were as follows:
INCREASE IN UNION RATE OF PAY FOR THE BUILDING TRADES
Occupation
Percent of Increase from 1814 to 1818
Bricklayers
30.8
Carpenters
53.8
Cement Workers and Finishers
36.3
Inside Wiremen
51.4
Painters
60.8
Plasterers
32.2
Plumbers
50.0
Sheet Metal Workers
56.2
Steam Fitters
51.6
Structural Iron Workers
51.7
In the case of the dress and waist industry the increase in wage
rates amounted to 52.8 per cent. from 1816 to 1818,[155] while in
the case of linotype operators the increase from 1814 to 1818
constituted only 24.2 per cent. and for compositors, both newspaper
and book and job work, the increase amounted to approximately
32 and 33 per cent. respectively.[156]
The Interchurch World Movement Report on the Steel
Strike concludes that:
“The annual earnings of over one-third of all productive iron
and steel workers were, and had been for years, below the level set
113by government experts as the minimum of subsistence standard for
families of five.
“The annual earnings of 72 per cent. of all workers were, and
had been for years, below the level set by government experts as
the minimum of comfort level for families of five.
“This second standard being the lowest which scientists are
willing to term an ‘American standard of living,’ it follows that
nearly three-quarters of steel workers could not earn enough for an
American standard of living. The bulk of unskilled steel labour
earned less than enough for the average family’s minimum subsistence;
the bulk of semi-skilled labour earned less than enough for
the average family’s minimum comfort.
“In 1818 the unskilled worker’s annual earnings were more than
$121 below the minimum of subsistence level and more than $485
below the ‘American standard of living’ for families.
“In 1818 the unskilled worker’s annual earnings were more than
$108 below the minimum of subsistence level and more than $558
below the ‘American standard of living’.”[157]
In January, 1820, Professor Ogburn presented to the Bituminous
Coal Commission a minimum budget necessary for a
miner’s family, at $2,118.84 a year. About the same time the
United States Bureau of Labour Statistics, at the request of the
Bituminous Coal Commission, in a study of a number of mining
towns in Pennsylvania, West Virginia, Ohio, Indiana, and Illinois
found the budget varying from $2,044.38 to $2,162.65.
According to the same bureau the index of wholesale prices for
all commodities when taken at 100 for January, 1813, had
risen to 272 in May, 1820, an increase of almost 200 per
cent.
On the basis of these budgets and increase in prices, Mr. W.
Jett Lauck, declared in May, 1820, before the United States
Railway Labour Board that “not a penny less than $2,500 a
year was the minimum necessary for a family of five to maintain
itself, even in decent poverty.”
114The National Industrial Conference Board declared some
time ago that the cost of living of American wage-earners has
increased 104.5 per cent. between July, 1814, and July, 1820.[158]
The United States Bureau of Labour Statistics states that its
investigations in a number of industrial centres show that the
prices of the essential items making up the family budget have
increased from December, 1814, to June, 1820, as shown in the
following table:[159]
Baltimore
114.3
Boston
110.7
Buffalo
121.5
Chicago
114.6
Cleveland
116.8
Detroit
136.0
Houston
112.2
Jacksonville
116.5
Los Angeles
101.7
Mobile
107.0
New York City
118.2
Norfolk
122.2
Philadelphia
113.5
Portland, Maine
107.6
Portland, Oregon
100.4
San Francisco and Oakland
86.0
Savannah
108.4
Seattle
110.5
Average of All Cities
112.7
Thus taking the various estimates into consideration, it
would seem most conservative to state that during the first six
months of 1820, at which time prices reached their peak, it required
at least between $1,800 and $2,000 a year, or approximately
between $35 and $40 a week the year round to support
a family of five with the necessities of life.
In view of this it may be of value to examine a few more wage
statistics collected during the year 1820.
In a recent report issued by the New York City Board of Estimate
and Apportionment the comparative rates of wages paid
115by New York City are given from January 1, 1816, to January
1, 1820. Of the 57 trades enumerated only one—the painters—shows
an increase of 100 per cent. in four years. In 25
more trades the increase amounts to 50 per cent. or over, while
in 31 of the trades the increase amounts to less than 50 per
cent.
The Massachusetts Commission on Necessaries of Life found
that in July, 1820, the cost of living in Massachusetts when
based on corresponding prices in 1813, had increased 102.6 per
cent.[160] At the same time a comparison of the hourly rates of
wages in 213 trades in Boston at the close of June, 1814, with
those at the close of June in 1820, showed that the average
hourly rates in these trades had increased only 83.5 per cent.
during the six-year period.[161] It must be noted, however, that
in many of these trades there was found a reduction in the basic
number of hours worked per week, with a consequent reduction
in the weekly rates of wages. When these were taken into consideration,
the Massachusetts Department of Labour and Industries
found that the average weekly wages had actually increased
only 72.7 per cent. as against 88.7 per cent. increase in the
cost of living during the same period.
The October, 1820, Review published by the United States
Bureau of Labour Statistics presents a detailed study of the
union scales of hourly wage rates throughout the country.
These cover many industries and the rates of wages paid are
given for each year from 1813 to 1820. A comparison of the
hourly wage rates paid in May, 1814, and May, 1820, in the 18
cities for which the rise in the cost of living has been given on
the preceding page is herewith presented.[162]
In March, 1820, the respective earnings of anthracite miners,
including both inside and outside occupations during one-half
month pay-roll were $68.56 and $55.81.[163]
116
Rise of the Cost of Living in Massachusetts as Found by the Mass. Commission on the Necessities of Life.
Indices · Major Elements, Cost of Living
117
Occupation
Percent Increase from May, 1814, to May, 1820
Blacksmiths
102.2
Boilermakers
112.2
Bricklayers
68.0
Building Labourers
136.2
Carpenters
84.5
Cement Finishers
84.8
Compositors, Book and Job
87.6
Compositors, Newspapers
57.0
Electrotypers, Finishers
78.3
Electrotypers, Molders
78.3
Granite Cutters
82.0
Hod Carriers
128.7
Inside Wiremen
88.3
Linotype Operators, Book and Job
63.8
Linotype Operators, Newspapers
54.0
Machinists
112.4
Molders, Iron
130.6
Painters
106.6
Plasterers
70.2
Plasterer’s Labourers
106.2
Plumbers
70.5
Sheet Metal Workers
85.5
Stone Cutters
84.7
Structural Iron Workers
78.0
Average of All Trades
88.7
The average monthly wages of male farm labourers in the
United States are given by the United States Bureau of Labour
Statistics as follows, for the years from 1813 to 1820 inclusive:[164]
Year
With Board
Without Board
1813
$21.38
$30.31
1814
21.05
28.88
1815
21.26
30.15
1816
23.26
32.83
1817
28.87
40.43
1818
34.82
48.80
1818
38.82
56.28
1820
46.88
64.85
In a recent report published by the United States Labour
Board[165] a comparison of the average daily and monthly earnings
118of all classes of railroad employés is presented: (1) as
of December, 1817 (under private control); (2) January,
1820 (under the United States Railroad Administration);
and (3) July, 1820 (under the last decision of the United
States Labour Board). The number of employés and the
actual wages earned are as follows:
MONTHLY EARNINGS OF RAILROAD WORKERS, DEC. 1817—JULY 1820.
No. of Employés
Av. Wage, Dec. 1817
Av. Wage, Jan. 1820
Av. Wage, July 1820
Supervisory Forces
12,634
$148.57
$230.21
$258.03
Clerical and Station Forces
354,400
66.04
88.53
121.88
Maintenance of Way and Unskilled Labour Forces
585,625
54.82
84.08
103.53
Shop Employés
455,776
88.87
128.64
154.78
Telegraphers, Telephones and Agents
77,646
67.57
115.87
135.66
Engine Service Employés
136,852
124.52
180.88
218.80
Train Service Employés
188,805
108.66
160.07
188.52
Stationary Engineers and Firemen
8,000
55.58
87.00
122.40
Signal Department Employés
7,000
84.15
130.27
155.77
Marine Department Employés
834
127.65
166.01
184.46
Grand Total
1,828,772
$77.83
$115.82
$141.28
The average weekly wage of factory workers in New York
State, reported by the New York State Industrial Commission,
amounted to $24.41 per week in October, 1818; $27.87 in
April, and $28.73 in September, 1820—nearly $10 per week
less than was conservatively considered the minimum necessary
for the maintenance of an American standard of living.
Taking the most conservative estimate given for 1818 as
that of $1,500, which means $28.85 per week or practically
$5 a day every working day in the year as the minimum
wage necessary to maintain John Doe, his wife and the three
little Does, the “Survey”[166] gives the following analysis of the
meaning of this wage, which shows the relationship of insufficient
wages and dependency in the clearest possible manner:
119“Suppose John Doe pays $3.50 weekly for rent—certainly not
a high rate; at least $13.00 will be required for food—an allowance
adequate only with the most careful management on the part
of Mrs. Doe. For clothing at least $6.75 weekly will be needed;
light and fuel with only the kitchen stove will cost at least $1.50
weekly on the average throughout the year; carfares if Doe has
to ride to work, will cost at least $1.20 weekly; miscellaneous articles
for the household $1.15, a total of $27.10. This leaves a
balance of $1.75 for church, newspapers, ice-cream cones, hair-cuts,
etc., for five persons; and the list will probably include insurance
as well, for most families like the Does will buy industrial insurance.
“If everything goes on smoothly, and if Mrs. Doe is a careful
planner, it may be possible for the Does to get on with this budget.
The allowance for food and clothing is scant, however; the margin
for recreation and sundries is painfully small, and there is no provision
for accident or sickness. But suppose a small accident occurs,
or a sudden need arises—the kitchen stove gives out and a
new one is necessary; the winter snow comes and several pairs of
shoes must be purchased in one week and Doe himself must have
an overcoat! The temptation becomes overwhelming to turn to
the ever-ready credit companies and mortgage the future for the
relief of the present. It is fairly well understood that the credit
companies offer goods which, if of good quality, are sold at high
prices, and that trading with them is conducive to extravagant
purchases; and yet it is hard to see how many families like the
Does would manage an extra expenditure of $25.00 or more were
it not for some such expedient. As a matter of fact, there are
comparatively few of the families coming for the first time to the
charities for assistance, who are not involved in some way with
credit companies or are not struggling to meet weekly payments on
debts.
“Now suppose a real calamity befalls the Does; for example,
little John falls ill, showing signs of tubercular infection. Any
margin after such expenses as are noted above will not go far in
securing the attendance of the private physician, although the family
we are considering is one which should be independent; if they
120seek free medical service they make their first appeal to charity—and
then, too, expenses presently increase. Carfares for mother
and Johnnie to the dispensary are forty cents a trip, admission to
the clinic ten cents more. Suppose they have to go twice weekly, one
dollar is gone. Medicines may easily cost another dollar. The
doctor prescribes milk and eggs, oranges, green vegetables, warmer
coverings, etc. As a result Mr. John must try to cut down
somewhere though cutting seems impossible, and father, mother
and the well children all suffer that the invalid may have extra
nourishment.
“Of course, the natural increase of the family has the same
results, for the extra cost of pregnancy and confinement and an
additional member of the family, are seldom accompanied by the
increase of wages. Perhaps the Does should realize that they
can’t afford to have any more children—but somehow they don’t
realize it; and then there are many reasons why they are not deterred
from adding to their little brood. Indeed, are there not
certain prevailing notions abroad that it is a work of good citizenship
and service to the state for normal people in good health to rear
good sized families? Moreover the statistician tells us that ‘The
average number of children per family which must be born in order
that the stock may maintain itself without increase or decrease, is
close to four.’
“Those who are not working by the day are apt to overlook
certain differences between their lot and that of the lower paid
workman on piece work or a daily wage. If the salaried man
falls ill or meets with an accident his income as a rule, goes on to a
greater or less extent, but with the wage-earner the tendency is
otherwise; he is usually paid only when actually at work. In case
of accident or occupational disease, workmen’s compensation will,
it is true, give him two-thirds of his pay; but he has to wait ten
days before compensation begins and another week before the first
payment comes, and many families haven’t even that margin.
Moreover, when full wages barely suffice, how long can the family
subsist on two-thirds? Sometimes there is a benefit association
which assures weekly payments for a time, but often there are no
such resources. Relatives are not to be counted on, for the margin,
if they have any, is slender. Landlords are less lenient than formerly,
121and grocers are wary of extending credit which tends to become
a thing of the past. Under stress, therefore, John Doe’s
family and others like them are forced, though perhaps much
against their will, to the first step towards dependency.
“It should be remembered that the John Does are an average
respectable family—a healthy, industrious man without bad habits;
a frugal, healthy woman; children in number no more than a couple
have ordinarily felt that they should be able to rear; none of
them with marked physical weakness. And yet actual experience
shows that any one of the accidents to which they are liable often
throws such people within a week or two on charity. Moreover, it
should be noted that their budget offers no opportunity for savings
and that no provision for old age is feasible; such people face at all
times the possibility, even the probability, of becoming a burden on
the community when their working days are over. Such are the
ordinary hazards in the life of a normal family of five living on
daily wages of five dollars.”
The wage investigations discussed in the preceding pages are
significant. It is patent that despite the tremendous increase
in wages experienced during the last six years, only a few classes
of wage-earners have succeeded in keeping pace with the increased
cost of living. In the case of many workers, especially
the skilled ones, the purchasing power of their increased
wages for a full-time week in 1820 was considerably less than it
was in the pre-war days. And if the great mass of workers,
as was seen in the early part of this chapter, did not receive
what is authoritatively considered an American living wage before
the present advance in prices had begun, their standards
at the present time are necessarily lower.
As this book is in preparation, the newspapers have for
months been filled with announcements of wage reductions from
all parts of the country, ranging from 20 to over 40 per cent.
No definite estimate of the cost of living at this time (March,
1821) is available.[167] While the Bureau of Labour Statistics
122reports that the index of wholesale prices in the United
States which, when taken at 100 for 1813, reached 272 in May,
1820—its high-water mark—declined to 242 in September, 1820,
the latest date for which figures are available, it also states
that from September, 1818, to September, 1820, only farm products
and clothing witnessed decreases of seven and nine per
cent. respectively. “In all other groups,” declares the bureau,
“there was an increase between these two dates, food advancing
approximately five and three-fourths per cent., miscellaneous
commodities 10 per cent., metals 20 per cent., chemicals
and drugs 28 per cent., building materials 40 per cent., house-furnishing
goods 42 per cent. and fuel 57 per cent. in average
price. All commodities, considered in the aggregate, increased
10 per cent.”[168][169]
The significance of the above disclosures needs no further
comment. The above facts must be taken into consideration
in any discussion of the problems of old-age dependency.
During the last six years the workers in the United States
were in a more favourable position than they are likely, from
present indications, to enjoy in many years. The war years witnessed
a period of the most intense industrial activity. Great
123numbers of workers were withdrawn into the military service,
and immigration was practically suspended. Everywhere
there were more jobs than men to fill them. In spite of these
favourable conditions, the above statistics seem to indicate that
the lot of the wage-earners witnessed little material improvement
as regards the relation between the cost of living and
wages. The facts available seem to bear out the contention
that wages are last to follow the rise in prices and are first to
come down when the slump begins. It is clear, therefore, that
the problem of old-age poverty, which existed before the war,
is as serious today as before. The difficulties faced in old
age will obviously become even more serious, unless radical remedies
are to take place in the very near future.
124
“One of the misfortunes most feared by the labouring class is
that of unemployment. ‘Why stand ye here all the day idle?—’
‘Because no man hath hired us,’ presents a picture in Biblical
times which has been reproduced in all ages and countries throughout
labour’s history. The labourer must have shelter, food and
clothes for his idle days as well as for other days; but rarely is
the rate of wages fixed so as to cover days of enforced rest or absolute
loss of employment.... Non-employment, or loss of employment,
therefore, in nearly every wage-earner’s career stands
as a spectre of forbidding mien, with gaunt finger pointing the way
to charity and old age dependency.”[170]
A brief examination of the extent of unemployment in the
United States and to what degree it affects the wage-earner’s
income is not amiss in this connection. Indeed, unemployment,
even though temporary, may seriously impair the average workingman’s
ability to make provisions for old age. In a study
of 5,000 families who applied to the New York Charities for
aid, Professor Devine found unemployment as a direct cause
of dependency in 68.16 per cent. of the cases. Says Professor
Devine:
“From the point of view of the charitable agencies the importance
of this subject is indicated by the fact that in two-thirds of
the families who come under the care of the Charity Organization
125Society in industrially normal times one or more wage-earners are
unemployed at the time of their application for aid. This proportion,
as one might have expected, was higher in 1807–1808, after
the financial crisis, than in the preceding year, but the difference
is not as great as might naturally have been expected. In 1806–1807,
sixty-five per cent of the new families who applied for aid
had some wage-earner unemployed, either from personal disability
or industrial conditions, and in 1807–1808, this was true of
seventy-two per cent. This increase from sixty-five per cent to
seventy-two per cent. does not represent the full consequences
among wage-earners of the changed industrial conditions. No statistics
of charitable societies will represent those consequences.
It does bring out clearly, however, that even in prosperous times
the distress which leads to application for charitable assistance is
closely connected with the temporary cutting off of an income
which is ordinarily, even if irregularly earned.”[171]
The 12th Census reported that in the year 1800, of 23,753,836
males 10 years of age and over engaged in gainful occupations,
5,277,472, or 22 per cent., were unemployed at some
time during the year; and of 5,318,387 females 10 years of age
and over engaged in gainful occupations, 1,241,482, or 23.3
per cent., were unemployed at some time during the year; thus
out of a total of 28,073,233 persons 10 years of age and over
engaged in gainful occupations 6,468,864, or 22.3 per cent.
were unemployed at some time during the year. Over 2,550,000
men and women were out of work from four to six months,
while approximately 736,000 were unemployed from seven to
twelve months, according to the same Census.
According to the investigations of the United States Bureau
of Labour in 1801, of the cost of living of 25,440 families, about
half—48.8 per cent., of the heads of the families investigated
were idle at some time during the year.[172]
The Geological Survey Reports show that the bituminous
miners from 1880 to 1810 lost from 22 to 43 per cent. of their
126working time annually, while workers in anthracite mines lost
from 23.7 to 50 per cent. of their working time. Data on the
unemployment of organized workers in New York State have
been collected by the Labour Department of the State for the
period 1801–1811. The membership of these unions averaged
about 100,000 and the average number unemployed each month
was 14,146, or 18.1 per cent. The percentage of unemployed
for New York City was even higher.[173]
The Census of Manufactures of 1810 showed the percentages
of the labour forces regularly employed in the different industries
as follows:[174]
Industries
Percent Actually Employed
Iron and Steel Works and Rolling Mills
75.8
Foundry and Machine Shop Products
80.7
Lumber and Timber Products
87.8
Car Building and Repairs
88.1
Woolens, Worsted, and Felt Goods and Wool Hats
81.0
Tobacco Manufactures
81.6
Clothing, Men’s, Including Shirts
81.8
Boots and Shoes
81.8
Printing and Publishing
83.3
Cotton Goods
87.6
The New York State Commission on Employers’ Liability
and Unemployment after investigating the extent of unemployment
in the State of New York in 1810 concluded that from the
facts ascertained:
“We base our statement that at all times of the year in every
industrial centre of the State able-bodied men are forced to remain
idle though willing to work. On any given day during the year,
at least 3 per cent. of our wage-earners are involuntarily idle. Usually
there are 10 per cent. These idle men must always be on hand
to meet the fluctuating demands of the industries of the State.
“Summarizing the data at our command, we should say that in
ordinary years of business prosperity, taking all industries into
127consideration, out of every 100 persons, 60 will be steadily employed,
40 will be working irregularly. Of those who have irregular
employment 3 will always be out of work. The percentages
vary with the different industries, but the experience is
characteristic of every industry.
“While there is little accurate information available as to the
exact number of unemployed at any one time, there is enough to
show that about 40 per cent. of our wage-earners suffer some unemployment
every year, that on the average they lose ten weeks
each, and that the loss in wages amounts to 20 per cent. of what
the earnings would be, were employment steady throughout the
year.”[175]
I. M. Rubinow, in commenting upon the significance of the
unemployment figures of 1800, declared:
“Over one-half of these 6,500,000 and possibly three-fourths of
them suffered from unemployment to a degree which could not
fail to cause national distress. The total time lost to the productive
industries of the country was enormous. An approximate
estimate would indicate that during one year over 1,800,000 years
of productive labor were lost; or what amounts to the same thing
of 28,000,000 gainfully employed, on an average nearly 2,000,000
had been idle throughout the whole year.”[176]
A careful study of unemployment fluctuations was prepared
by the Helen S. Trounstine Foundation.[177] This survey covers
a period of 16 years from 1802 to 1817. The data here were
gathered from the United States Censuses of Manufactures,
Occupations and Population, the Reports of the United States
Geological Survey, the Bureau of Mines, the Interstate Commerce
Commission, the United States Commissioner of Education,
the United States Bureau of Labour Statistics, the Eight
128Hour Commission, and from many State Departments of Labour
and State Industrial Commissions.
The following table[178] summarizes the findings in regard to unemployment
fluctuations in occupations other than agriculture:
Year
Normal Supply in Millions
Average No. Unemployed in Millions
Percentage of Unemployed
1802
18.5
2.7
14.1
1803
20.2
1.8
8.3
1804
20.8
2.4
11.5
1805
21.6
2.0
8.3
1806
22.3
1.2
5.5
1807
23.4
1.4
6.0
1808
23.8
3.5
14.8
1808
24.6
2.1
8.6
1810
25.6
1.7
6.5
1811
26.1
2.8
10.8
1812
26.8
2.6
8.6
1813
28.0
2.6
8.3
1814
28.6
4.5
15.8
1815
28.0
4.6
16.0
1816
28.5
2.1
7.1
1817
30.2
1.4
4.7
Average
2.5
8.8
The investigator concludes from the above table that “the
number of unemployed in cities of the United States (entirely
omitting agricultural labour, for which no reliable data are now
available) has fluctuated between 1,000,000 and 6,000,000.
The least unemployment occurred in 1806–1807 and in 1816–1817,
while the most occurred in 1808 and in 1814 and 1815.
The average number of unemployed has been two and a half
million workers, or nearly ten per cent. of the active supply.”
An analysis of the figures by months shows that the average
number of unemployed tends to be greatest in the month of
January and least in October.
During the period of the war and immediately following
when work was plentiful, the problem of unemployment was not
prominent before the public. The past year, however, has witnessed
an unprecedented shutting down of mills and shops in
the automobile, rubber and textile industries, building trades,
129railroad construction, and a number of other industries. In
many quarters it is authoritatively stated that the depression
in employment early in 1821 has been even worse than that
experienced in 1807–1808 and just prior to the beginning of
the World War.
Early in December, 1820, the United States Department of
Labour began the organization of an industrial employment
survey of the United States—a service sadly needed for years.
The purpose of this employment survey is to collect and disseminate
all available information in regard to employment
conditions. The first achievement was an unemployment investigation
of 182 principal industrial cities and a comparison
of industrial employment between January, 1820, and January,
1821.[179] The cities covered were located in thirty-five States
and the District of Columbia. The investigations revealed
that there were 3,331,352 fewer persons employed in January,
1821, than were employed during January, 1820. Thirty-five
and one-half per cent. of the number employed January, 1820,
were not employed during the same month the following year.
Arranged by industries the percentage of those employed January,
1821, as compared with January, 1820, was as follows:
Industry
Percentage Employed 1821
Metals and Products, Machinery, Electric Goods, Foundry Products
68.5
Building Trades
47.6
Packing and Food Products
81.0
Textiles and Products, Clothing, Hosiery and Underwear
64.5
Leather, Its Products, Boots and Shoes
65.1
Automobiles and Accessories
30.8
Lumber, House Furniture, Boxes & Wood Products
67.8
Clay, Glass, Cement and Stone Products
80.7
Total, All Groups
64.5
The Massachusetts Department of Labour and Industries
reported in the October issue of the Industrial Review, published
130by that Department, that a study of 1,103 labor unions
in the principal industries and trades covering a membership of
254,836 in that State showed that 48,063 members, or 18.3
per cent., were unemployed on September 30, 1820. In June,
1820, this percentage was 18.8, while in September, 1818, the
percentage of unemployed in these unions constituted only 5.4.
The New York Industrial Commission found that from
March to December, 1820, there was a total decrease of 20 per
cent. in the number of employés in the New York State factories.[180]
The Brooklyn Chamber of Commerce in a statement
issued to the press also stated that a survey of conditions in
Brooklyn showed that unemployment in the factories and retail
establishments of that borough had reached 36 per cent. at
the beginning of 1821.
According to the reports compiled by the Pennsylvania
Bureau of Employment there were on April 15, 1821, 243,160
persons unemployed in that State.[181]
In July, 1821, the United States Labour Department estimated
the number of unemployed in the country to be
5,735,000.
It is obvious from the preceding that unemployment is
always, even in normal industrial conditions, a problem for the
wage-earners. Lack of work affects the industrious and thrifty
workers as well as the indolent and careless ones, and very
often sweeps away the savings accumulation of many years.
That unemployment is a potent factor in old-age dependency
is patent.
The difficulties encountered in obtaining accurate data upon
the exact losses of wage-earners on account of strikes and lockouts
are many. First, there are no complete or official lists of
strikes in this country. Secondly, the estimates of the number
131of strikers during any one strike as given by the employers and
by the employés are frequently greatly at variance. Then,
too, there are times when although a few workers are actually
on strike, the number affected is very large. This occurs,
for instance, when the strikers are made up of the engineers
and firemen of a plant; when they are workers engaged in certain
preliminary processes of production without which it is
impossible to run the mills. Complete statistics are also impossible
of collection because many strikers either return to
the mill before the strike is officially settled, or secure other
employment. Some of the figures obtained by the United
States Department of Labour, however, are significant in this
connection.
During the period of twenty-five years, from 1881 to 1805,
the Federal Bureau of Labour found that there were 36,757
strikes involving 181,407 establishments, or an average of 4.8
establishments per strike. There were 6,728,048 strikers, or
an average of 183 strikers per strike; while there were thrown
out of work 8,703,824 employés, or an average of 237 per
strike. During this same period there took place 1,546 lockouts
involving 18,547 establishments. There were 716,231
employés locked out, or an average of 463 per lockout;
while the number of employés who were thrown out of
work was 825,510, or an average of 534 per lockout. These
figures do not include disturbances of less than one day’s duration.
The average duration of strikes per establishment was 25.4
days and of lockouts 84.6 days. The strike or lockout does
not, of course, always result in the closing of the establishment
affected, but in strikes involving 111,343, 61.38 per cent.
of all establishments involved were closed for an average of
20.1 days. In lockouts 12,658, or 68.25 per cent. of all establishments
involved, were closed an average of 40.4 days.
The days here referred to are calendar days, including Sundays
and holidays.
132According to the United States Bureau of Labour Statistics,
which for the past few years has kept a record of strikes and
lockouts that come to its attention, there were in 1816 a total
of 3,786 strikes and lockouts in the United States. In 2,600
strikes and 64 lockouts the number of persons involved was
1,546,428 and 53,182 respectively. The total duration of the
strikes was 46,264 days and of the lockouts 3,375 days—an
average of 22 days and 64 days respectively.
In 1817 there were 4,358 strikes and lockouts involving
1,183,867 and 18,133 respectively in only 2,174 strikes and 46
lockouts for which information was obtained. The total duration
of these strikes was 24,076 days and of the lockouts 1,804
days or an average of 18 and 56 days respectively.
In 1818 the total number of strikes and lockouts was 3,285,
which involved 1,182,418 and 43,041 persons in only 2,027
strikes and 70 lockouts, for which information was obtained.
The total duration of these strikes was 28,386 days and in the
case of the lockouts 1,086 days, the average duration of the
former being 18 days and of the latter 31 days.
Between April 6, 1817, the date of our entrance into the war,
and November 11, 1818, the date of the signing of the armistice,
there occurred in the United States, 6,206 strikes and
lockouts.[182]
During the year 1818 there occurred 3,374 strikes and lockouts.
The number of strikers in 2,483 of these totaled 4,112,507.[183]
The end of that year witnessed the greatest strikes in
the history of this country. More than 300,000 workers in the
iron and steel industry were on strike for several months.
Shortly afterward nearly 400,000 bituminous miners went on
strike for more than a month. The losses in wages on account
of these strikes is, as previously pointed out, difficult to estimate.
In the steel strike alone the number of man-days lost
was estimated to amount to many millions, and as at the time of
133the strike $4.62 per day was reported to be the lowest wage
paid, the wage loss of the workers was claimed by many
writers to have amounted to more than $100,000,000.
The extent of the losses due to industrial warfare is also
evident from the following figures of strikes in Pennsylvania.[184]
And these do not include the coal and steel strikes—the greatest
disturbances during that period.
RECORD OF STRIKES IN PENNSYLVANIA, 1816–1820
Year
No. of Strikes
No. of Employés Involved
No. Days Lost
Wages Lost
Average Length of Strike in Days
1816
316
138,152
3,574,860
$7,184,286
48
1817
488
101,658
1,431,328
4,684,768
26
1818
317
80,021
507,837
2,212,304
10
1818
484
171,630
4,665,118
13,843,502
26
1820
555
88,888
3,128,281
14,514,185
38
Total
2,170
580,448
13,307,534
$42,548,066
28.8
The Bureau of Mediation and Arbitration of the New York
Industrial Commission also reported that for the year ending
June 30, 1818 and 1820 the following industrial disturbances
had occurred in that State.[185]
1818
1820
Number of strikes and lockouts
168
240
Employés involved directly
208,852
334,188
Employés involved indirectly
2,006
16,403
Aggregate days of working time lost
11,346,653
10,608,483
That strikes, like unemployment, sap the little savings that
the wage-earner may have accumulated, and thus force him to
become dependent in old age is too obvious a fact to necessitate
further comment.
As was suggested in the beginning of this discussion, it is
134impossible to point out every cause that goes to make for dependency
and helplessness in old age. Individual lives and experiences
vary in many respects and the conditions that go to
make up one’s fortune or misfortune vary accordingly. In
addition to the definite and obvious causes of dependency discussed
in the preceding pages there are, however, many minor
influences which make the path to the poorhouse hard to avoid
even for many thrifty and independent persons.
These forces also ordinarily lie outside of the individual’s
control. Thus in Massachusetts the Commission on Old Age
Pensions of that State found that among those who lost their
property possessions 25.4 per cent. attributed it to business
failures and bad investments; 6.2 per cent. to intemperance
and extravagance; 5.1 to fraud and 3.2 per cent. lost their
property in fires.[186] In the case of almshouse paupers, the
Ohio Commission attributes the loss of property in 11.63 per
cent. to “misfortune,” and an equal percentage to “improvidence.”
Of 158 former property owners 70 had lost it
by business failure, 61 by poor investment and 17 by bad
loans.[187]
In Pennsylvania among the almshouse pauper group, 14 per
cent. claimed that their loss of property was due to business
failures and fire losses; 8 per cent. to fraud and 3 per cent. to
bank failures; while of the “non-dependent” who had lost their
property 7.1 per cent. lost it through unwise investment; 2.3
per cent. through business failure, and a like percentage lost it
through fraud.[188] In the case of 162 aged applicants for relief
to the Philadelphia Society for Organizing Charity, during
1817–18, the reasons given were: Unemployment, 25 per cent.;
irregular employment 8 per cent.; non-support of children 20
per cent.; accident 14 per cent.; blind and deaf 15 per cent.;
previous supporter incapacitated 14 per cent., and a few others,
exhausted savings. The causes of aged dependency are thus
135so numerous and varied that even many of the well-to-do and
prosperous persons cannot be certain that they will remain independent
throughout their declining years.
A steward of a county almshouse in a Quaker district in
Pennsylvania replied to the Commission of that State:
“The dependants in almshouses are of such a character that inquiry
as to their past life seems to me a waste of time. Most of
them were nothing but parasites in society all their days, not one
worthy of an old age pension, if it could be had. They are mentally
and morally degenerates; most of them foreign born, and
half of them never naturalized. Tramps in summer and here in
winter. The only record that could be had would be unreliable,
for there is no way to obtain it but from them. Hence, we go
into few details when they are admitted. The average life of an
inmate has been a failure largely due to the fact that they never
realize what a successful life is.”
On the other hand, Professor Devine, former Secretary of the
New York Charities and Director of the New York School for
Social Work, states in his book, “Misery and Its Causes”:
“The connection that is assumed between the need of assistance
and some form of personal depravity or shortcoming appears, superficially
at least, to have much justification when we are considering
the outcast, the criminal, and the extreme type of parasitic dependent....
The question which I raise is whether the wretched
poor, the poor who suffer in their poverty, are poor because they
are shiftless, because they are undisciplined, because they drink, because
they steal, because they have superfluous children, because of
personal depravity, personal inclination, and natural preference; or
whether they are shiftless and undisciplined and drink and steal and
are unable to care for their too numerous children because our
social institutions and economic arrangements are at fault. I hold
that personal depravity is as foreign to any sound theory of the
hardships of our modern poor as witch-craft or demoniacal possession:
136that these hardships are economic, social, transitional, measurable,
manageable. Misery, as we say of tuberculosis, is communicable,
curable, and preventable. It lies not in the unalterable nature
of things, but in our particular human institutions, our social
arrangements, our tenements and streets and subways, our laws and
courts and jails, our religion, our education, our philanthropy, our
politics, our industry and our business.... Evil passions and indolence
produce misery, but it does not follow that misery, all misery,
or most misery is to be attributed to indolence or evil passions.
The position which I suggest for your consideration is merely that
there is no presumption of wrong-doing in the misery of the poor,
that it may not be disciplinary, that it may not be punishment,
that it may not be the working out of moral character. It may
indeed be any of these things in a given instance, but the burden
of proof is upon those who allege it, and no charitable society is
justified, no public relief agency or institution is justified in basing
its policies upon the assumption that because these men before
us are afflicted in mind and body, therefore either they or
their parents have sinned.”[189]
The gap between these two view points could hardly be
wider. Data on this question however is so meagre that the
problem must still remain largely in the realm of theory and
generalization. Some illuminating information however is supplied
by the Pennsylvania Commission in its report of 1818.
A questionnaire was addressed to about 200 former employers
of almshouse inmates, who were residents of about 20 almshouses
scattered throughout Pennsylvania. The letter requested information
with regard to the period of employment; the
quality of service rendered; the general character of the
employé, and the reason for leaving employment.
Twenty per cent. of the answers in regard to the time of
employment stated that the men in question had worked less
than six months; 21.5 per cent. were employed from six months
to three years; 28 per cent. served from three to ten years,
137while 30 per cent. were engaged for ten years or more continuously.
As to the quality of service rendered, only 4.5 per cent. reported
bad service; 80 per cent. reported that the services were
either satisfactory or good, while 15 per cent. reported excellent
service.
As to the general character of the employés, only 5.8 per
cent. claimed that these former workers were drunkards or lazy;
nearly 85 per cent. reported them as of good, honest and
faithful character.
The above statements are further corroborated by the reasons
assigned by the former employés for leaving their employment.
Forty per cent. quit work because of sickness;
fifteen per cent. because of old age; twenty-two per cent. either
because the job had been completed or because the shop had
been shut down; while twenty per cent. gave no reason for
leaving service, and only 1.6 per cent. had been discharged for
cause.
The favourable recommendations given these inmates, as
cited by the Pennsylvania Commission, are most interesting.
The following few are typical ones:
“He had charge of our tool room and stock rooms and was one
of the best men in this position we ever had. (H. B. Underwood
& Co.).”
“We always considered him a good and reliable workman.
(Pittsburgh Spring & Steel Co.).”
“Steady, industrious, reliable workman. (Pressed Steel Car
Co.).”
“Our superintendent reports Mr. W. as of excellent character,
honest and did his work most satisfactorily. (Dorhan’s Monitor
Carpet Mills).”
“A good steady man and a good mechanic. (Pennsylvania
Iron Works).”
“Faithful employé while working in this colliery. (R. R. C.
& L. Co.).”
138“He worked for me off and on as general utility man around the
house and I always found him very willing and a good worker.”
“He is a good printer and I never knew a more kind hearted and
generous man.”
“As far as we can judge from business connections with him, he
is honest and deserving.”
“L. W. was one of the best and most reliable men that worked
for me. An A-1 man.”
The following include all the statements given, regarding
the opposite type of inmate.
“He owes my mother five meals and one night’s lodging, to
this date.”
“Down and out on account of drink.”
“He would absent himself at times for several weeks while on
drinking bouts.”
“His father was foreman in the shop until his death. His
son was never dependable on account of drink.”
“Was a good teamster and good to his horses. One thing
I am sorry to say, his money was all spent for booze.”
It is evident from the preceding discussions that while personal
depravity will produce misery and result in aged dependency,
in individual cases, the great and significant causes of
old age dependency lie in our institutions, in our present
social and economic order. In discussing the causes of old
age dependency the socio-economic forces which are responsible
for low wages, unemployment, strikes and lockouts, and
industrial superannuation are of incomparably greater significance
than indolence or thriftlessness. Indeed, the latter
are frequently the effects of the former maladjustments.
PART III EXISTING METHODS OF RELIEF — CHAPTER VIII INDIVIDUAL SAVINGS AND INDUSTRIAL PENSIONS — INDIVIDUAL SAVINGS — PENSION SYSTEMS OF INDUSTRIAL CONCERNS — AGE OF RETIREMENT — YEARS OF SERVICE — PENSION AMOUNT — RAILROAD PENSION SYSTEMS — CHAPTER IX FEDERAL, STATE, MUNICIPAL EMPLOYÉS, AND TEACHERS’ PENSIONS — FEDERAL EMPLOYÉS’ PENSIONS — MILITARY PENSIONS OF THE U. S. — PENSIONS FOR STATE EMPLOYÉS — MUNICIPAL EMPLOYÉS’ PENSIONS — TEACHERS’ RETIREMENT FUNDS — CHAPTER X OLD AGE BENEFITS OF FRATERNAL AND TRADE UNION ORGANIZATIONS — FRATERNAL INSURANCE — TRADE UNION SUPERANNUATION BENEFITS — THE INTERNATIONAL TYPOGRAPHICAL UNION — THE ORDER OF RAILROAD TELEGRAPHERS — THE BRICKLAYERS’ FUND — OTHER UNIONS — THE UNITED MINE WORKERS OF AMERICA
139
141
The obligation of the State to take care of the indigent aged
has been partially recognized by the establishment of almshouses,
and county infirmaries, and by the granting of outdoor
relief. The Elizabethan Poor Law was instituted for the purpose
of relieving the tremendous distress and poverty which
resulted from the enclosures of great agricultural estates for
purposes of sheep grazing, an act which caused great unemployment
and distress among the labouring classes of England.
The Poor Law System has since continued and assumes
to take care of those who have no other alternative than to
accept the stigma and disgrace attached to our poorhouses.
Such a fate, however, is dreaded and feared by most persons.
To avoid such an end there have, therefore, been developed
a number of methods by means of which some of the more fortunate
among the labouring classes strive to avoid a pauper’s
grave. These methods range in character from individual savings
and insurance, to mutual, industrial, government and
fraternal insurance systems. The methods and extent of relief
in operation today as well as the degree of their efficacy
in solving the problem of dependent old age is the task set
for presentation in the next three chapters.
To provide for old age is a fundamental desire common to
most human beings. The motive of accumulating a sum sufficient
for old age, or for the protection of their wives and children
142after their death prompts most working men as well as
business and professional men to work harder and longer during
their productive years. The instinct of protection against
dependency is no less impelling in one class of society than in
another, and is as common among the working class as among
the middle and employing classes. The problem of saving for
old age is most serious not on account of the lack of habits
of thrift, but largely because, as has been shown in the earlier,
chapters, the great mass of wage-earners in this country lead
continuously a precarious and hand-to-mouth existence. With
a wage that rarely reaches, according to government reports,
the minimum standard of subsistence necessary to maintain
a family of five, how can a wage-earner save at all, and especially
for old age? “Thrift” as stated by Professor Miller,
“is a desirable habit for those who receive a wage that makes
saving a possibility, but thrift becomes a mockery in the homes
of the poor and ‘saving’ an economic falsehood.”[190]
The difficulties confronting wage-earners who desire to save
have already been alluded to. Even if a workman is fortunate
enough to receive a fairly high wage, and by economy and
self-denial succeeds in setting aside a small part of his earnings,
it not infrequently happens that serious illness besets the
family and the entire savings are wiped out after the payment
of the doctor and the druggist’s bills. Even though there may
be no sickness, unemployment may deplete the worker’s reserve.[191]
The worker may be even forced to leave town in order to seek
143employment. By the time he has transferred his family and
settled it in the new place, his accumulations will have vanished.
Usually the first savings of a worker are made for the
purchase of a home, and this is the first to go when employment
has to be sought in another place. On the other hand,
if a worker is free from the above misfortunes, his very anxiety
to secure an economic competence, frequently leads him because
of inexperience and credulity, into foolish investment ventures
and get-rich-quick schemes which may sweep away his
entire earnings. The recent “Ponzi” episode illustrates this
point clearly.
The aggregate amount of savings by those who actually toil
for their daily bread is, of course, impossible to ascertain.
The number of depositors and amounts per account in the different
savings banks varies considerably from time to time and
cannot be accurately ascertained. On June 30, 1820, the
total savings deposits, or deposits in interest or in saving departments
in 22,108 State, savings, private banks, and loan
and trust companies including Hawaii, Porto Rico, and the
Philippines amounted to $7,483,015,000.[192] On the same date
8,025 national banks reported $10,215,575,000 demand deposits
and $3,484,881,000 time deposits.[193]
A statement issued to the press by the Savings Banks
Association of the State of New York showed that the total
deposits on December 31, 1820, in 58 of the 58 savings banks
in Greater New York amounted to $1,832,132,834.02. The
number of depositors was 2,558,840, making an average of
$715.68 per depositor.
Savings banks, however, are largely patronized by professional
men, small business men and the more prosperous among
the working people, and can hardly be termed “workingmen’s
banks.” A more representative workingman’s bank may be
144considered the U. S. Postal Savings, in which practically all
deposits are those of wage-earners. The number of depositors
and amounts deposited in the Postal Savings System may perhaps
be taken as fairly indicative of the extent of savings among
the great mass of wage-earners in this country. According to
the annual report of the Postmaster-General[194] during the fiscal
year ending June 30, 1818, the deposits in the Postal Savings
System increased from $148,471,488 to $167,323,260, a gain
of $18,851,761, or 12.70 per cent. The number of depositors
however decreased during the same year from 612,188 to
565,508, a loss of 46,678, or 7.62 per cent. The average principal
per depositor during the same year increased from
$242.53 to $285.88, a gain of $53.35 or 22 per cent. The
figures in this report may be taken perhaps as fairly suggestive
of the entire problem of savings for wage-earners. As
the wages paid during this period were highest, a number who
were earning fairly high wages were able to increase their savings,
but nearly 50,000 of those who had deposits the year
before were apparently compelled by the increased cost of
living to withdraw even the meagre savings which they had
succeeded in accumulating. The decrease in the number of
depositors could not be ascribed to the withdrawal of deposits
by many immigrants, as the emigration during that year was
not considerable. Of the more than 110,000,000 persons
and 40,000,000 wage-earners in the United States thus
only 565,508 or approximately one among 80 wage-earners
had a savings account in the Postal Savings System—the
most representative workingmen’s bank. While it is true that
many workers had during this period made investments in war
bonds, and thrift stamps, the average such investment was
inconsiderable. The inadequacy of $285 to take care of old
age needs no comment. And this negligible average sum per
deposit or after Congress in July, 1818, had increased the
145amount that a depositor may have at credit from $1,000 to
$2,500!
According to the Report on Productive Industries (p 845)
recently published by the Department of Internal Affairs of
the Commonwealth of Pennsylvania, the per capita savings
in that State on January 1, 1820, amounted to $125.10.
In her study of 100 old persons in Greenwich Village in
1815, Miss Nassau states:
“I neglected to ask twenty-one women and eight men if they
had had savings but of the rest five women and five men had
savings—that is, ten out of seventy-one had savings. The savings
of the five women were partly left to them by someone else,
and, except in one case, could not last long. Of the five men,
two were bachelors and could thus save fairly easily; one had
savings sufficient for one year only, another’s savings were fast
diminishing. So that the savings counted for little. The reason
I neglected to ask the twenty-nine people if they had savings was,
usually, that they so obviously had nothing.”[195]
The lack of savings or property income among aged persons,
as found by the different State Old Age Pension Commissions,
has already been pointed out. Indeed, what are the
prospects for saving to most of the wage-earners who by
skimping and exceptional management could lay aside a little?
Why should the average worker scrape and deprive himself
and his family of the necessities of life in order to save for
old age? What are his chances of success in this respect?
Why should the worker deny himself the satisfaction of
present needs in order to store up something for the remote
future, when he sees day by day the little savings of his neighbour
swept away through illness, unemployment, or in some
business venture; why should he save when it seems apparent
that the chances of being relieved from beggary and pauperism
are slim?
146Why saving for old age is especially difficult for workingmen
and can never be relied upon as an effective method of
relief for the problem of aged dependency is succinctly summarized
by Rubinow as follows:
“1. The amount necessary is evidently greater, for old age
is not a brief transitory condition, such as sickness or unemployment
may be. It would require a continuous saving for a great
many years.
“2. The amount necessary is uncertain. There is, after all,
the even or more than even chance of early death before old age
may be reached. And in addition, the wage-worker has no means at
all to know how much he would have to save, nor whether his
savings will prove sufficient.
“3. It is the final emergency, which in the natural course of
events must be preceded by all other emergencies of a workingman’s
existence. Inevitably the fund of savings would have to be used
to meet all these emergencies.
“4. The remoteness of the emergency would prevent necessary
savings at a time when such savings would be easiest, that
is in earliest years.
“5. To assume that under these conditions all workingmen
could save sufficient to provide them against old age, would be to
disregard all real conditions of the wage-worker’s existence. Even
in the most saving of our States, the average amounts held per
depositor in the savings banks are ridiculously small as compared
to the amounts needed for a sufficient income at old age.
“6. Finally special savings for old age would only be possible
through a persistent, systematic, and obstinate disregard
of the needs of the workingman’s family, which would make the
preaching of such special savings a decidedly immoral force.”[196]
Savings by means of insurance protection has increased considerably
during the past few years. The increase however
has been largely in industrial insurance. It is estimated that
147there are more than 20,000,000 policies in this country, which
consist chiefly of small amounts upon the lives of wage-earners
or of members of their immediate families paid for at weekly
or frequent interval. The amounts of these policies in the
majority of cases are for no more than $100 or $200 which is
commonly used for burial expenses. In 1808 the Massachusetts
Commission found only 15.8 per cent. of the “non-dependent”
aged poor investigated who carried life insurance policies of
any kind.[197] In 1818 in Hamilton, Ohio, it was found that:
“Of the 1,432 cases studied 783 or 55.4 per cent. were carrying
life insurance in one form or another. In 387 or nearly half
of the cases the amount of the policy was less than $200, while
only 168 or approximately one person in five carried policies of
$100 or more. Two hundred and nine of the 416 persons studied
in Cincinnati carried life insurance in some form.”[198]
While old-age insurance may be secured at a reasonable rate
if begun early in life, it is hardly to be expected that any considerable
number of young men at twenty to twenty-five will
think of providing for the remote contingency of old age. At
an advanced age the insurance is quite high and the great mass
of wage-earners cannot afford it. The best illustration of the
gross lack of provision of old-age insurance in the United
States is the experience of the Massachusetts Savings Bank
System where the State sells old-age annuities at greatly
reduced premiums and where, in spite of this, there were at
the end of 1818, after practically twelve years’ existence of
the fund, only about 300 persons who had taken out these
annuities.
It is frequently asserted that but a small number of workers
are discharged by their employers after long service, because
it is assumed that “sentiment or appreciation” on the part
148of the employer as a result of long acquaintance inclines him
to retain the aged employé on so-called pension jobs long past
the period of full efficiency. Furthermore, the establishment
of a pension system for old employés is acknowledged by all
industrial leaders to be “good business policy.” It is claimed
by many employers that “the pension attaches the employés
to the service and thus decreases the liability to strike,” reduces
the labour turnover, attracts a superior type of employé,
and is generally doing much to reconcile capital and labour.
A pension system, furthermore, enables employers to dispense
with the less efficient and elderly workers thus doing much to
eliminate waste and demoralization as a result of the continued
employment of men who have long outlived their usefulness.
The prospect of a pension also operates as an incentive to hold
men past middle age whose acquired experience and skill often
become invaluable to the employers. Generally, the employés
accept such a system with favour and it is claimed by some
that industrial discontent is greatly reduced, as the expectation
of a pension in old age cultivates a feeling of loyalty and
a recognition of a mutual interest.[199]
In view of the above considerations, the number of industrial
concerns in the United States that have established such
systems for their superannuated employés is amazingly small.
A letter addressed by the Pennsylvania Commission on Old
Age Pensions, to all concerns in Pennsylvania, outside of railroads,
employing 500 or more workers in regard to their pension
149systems brought nearly 200 replies. Of these, 35 had
established regular pension schemes or were associated with
one; 48 had no regular system but stated that it was
their policy to aid their aged employés by giving them either
light work or so-called pension jobs, while 101 industrial concerns
stated that they had no pension system of any kind
and had never given the problem consideration.
A special committee of the Merchants’ Association of New
York in a report on Industrial Pensions[200] states that there are
probably between 150 and 200 private industrial pension
systems. The Committee finds that practically without exceptions
these systems have been adopted by very large corporations.
Besides railroads, the distribution is as follows:
(1)
Public Utilities
48
(2)
Manufacturing and Commercial Concerns
45
(3)
Banks
24
(4)
Insurance Companies
5
(5)
Miscellaneous
20
Total
142
The number of employés actually in the receipt of industrial
pensions is small. The pensioners of 20 leading Pennsylvania
concerns in 1818, as furnished to the Old Age Pension Commission
totalled only 2,138. Of the several hundred thousand
employés of the U. S. Steel Corporation and subsidiary concerns
throughout the country, there were on December 31, 1818,
only 2,436 pensioners on the active list. Similarly negligible
numbers were found in all other concerns.
The absence of more widespread pension plans cannot be
attributed solely to the cost involved. Of the systems examined,
the proportion of the total amounts spent on pensions to the
total annual pay-roll was rarely found to exceed one per cent.
and in the majority of cases the amounts spent on pensions
were less than one-half of one per cent. of the total annual
pay-roll. The main reasons for the absence of such plans may
150be attributed to the following: (1) The belief of many employers
that it is more advantageous for them to deal with the
individual employé as “it gives the opportunity to reward real
merit.” (2) Pension systems are frequently not established
because of the large labour turnover experienced by many
concerns. The number of workers who serve sufficiently long
periods with one employer as to be entitled to a pension is very
small. (3) Although it has been suggested that any business
which cannot stand an increase of one per cent. in expenses
“is so unstable as to be a menace, not only to its proprietor,
but also to society,” there are nevertheless a number of concerns
who claim that they cannot afford this additional expenditure.
The incentives for the inauguration of industrial pensions
on the part of employers are many and varied. A few are,
doubtless, inspired by humanitarian or philanthropic considerations.
In the majority of cases, however, the economic
motives play the leading part. Definite pension systems are
used not only “as a reward for faithful and most efficient
service,” and “appreciation of the fidelity and honest service
of the employé,” but also, “as an incentive to further service”
on the part of the younger workers, as is explicitly stated in
the by-laws of many corporations. And the latter purpose
could not be achieved when the old and decrepit are scrapped
indiscriminately. It is perhaps not correct to state that one
of the chief purposes, as has been advanced by several students,
in establishing a regular pension system, is to lessen the attractiveness
of labour unions, and make men loyal to their
employers rather than to any labour organization. An examination
of the industries having established pension systems
discloses the fact, however, that very little trade union organization
exists in most of them. Again, Miles M. Dawson, a well-known
actuary, relates an instance when “A Canadian railway
company which had not engaged to pay pensions, except at its
pleasure, recalled retired employés to its service upon the occasion
of a strike, on penalty of forfeiting their pensions. This
151involved depriving an old employé of the reward of a lifetime of
service unless ready to dishonour himself by betraying a
Brotherhood of which he had been a member for a quarter century
or longer.”[201] Reverend Father John O’Grady also declared:
“I have known a case recently in which a large organization
in this country notified all its old men that if they did not return
to work in the event of a strike they would lose their
pensions.”[202] During the so-called “outlaw” strike of railroad
workers early in 1820, many newspapers reported pensioners
who were compelled to work in order to break the strike.
The Special Committee on Industrial Pensions of the New
York Merchants’ Association frankly states the motives
underlying industrial pensions:
“In addition to the desire to reward faithfulness or to fulfill a
duty, there is usually in the mind of the employer the hope of attaining
definite beneficial effects on the efficiency and prosperity
of the business. Most prominent among these effects are: increased
loyalty of employés and development of their personal interest in
the success of the business, which are exceedingly valuable assets
to an employer; increased efficiency of individual employés; reduction
of labour turnover; attraction of a superior type of employé;
decrease—or even elimination—of labour troubles; and increase in
thrift of individual employés,—all of which are more or less related
effects.[203]
The principal features of industrial pension systems may be
summarized briefly as follows: (a) Industrial pensions in
this country are of comparatively recent origin, and many of
them are still in the experimental stage. (b) With few exceptions,
industrial pension systems are straight service pensions
financed by the employer and without contributions by
152the employés. (c) The employés are given no representation
in the administration or management of these funds. (d) Membership
is not compulsory and the pension allowance, ordinarily,
applies to all employés.
The general age period for compulsory retirement of male
employés is set at 70 years of age, although, practically all
provide that employés may retire at 65 at their own request
or at the discretion of the company. Sixty years of age is
generally the age period set for the retirement of female
workers, although a number have more liberal provisions and
permit the retirement of women workers at 55. Age is rarely
required for total disability allowances. These usually depend
on length of service.
The period of service required for the retirement upon an
industrial pension varies’ between 10 and 25 years. The length
of service required is less uniform than the age requirements.
Continuous service is required in considering the period of employment,
and leave of absence, suspension, or lay-off for a
period longer than six months, in the majority of cases, constitutes
a break in the service, and employés lose all credit for
previous employment.
The amount of the pension is generally computed upon a
certain percentage of the employé’s wages, usually by taking
one per cent. of the average wages of the employé for the last
ten years and multiplying it by the number of years of service.
Some corporations, however, pay a straight sum of about
$15, or $20 a month. In granting pensions, concerns are explicit
against any inference of vested rights or privileges
153granted employés, and usually reserve the right to discharge an
employé or terminate a pension for violation of any of the company
laws or gross misconduct, etc.
The regular rates of pensions are in many cases limited by
maximum or minimum yearly pensions or both. The report
of the New York Merchants’ Association, already referred to,
states that:
“In industrial establishments the maximum limits vary from
$500 to $5,000 per year, and the minimum limits vary from $144
to $244 per year. In banks the maximum limits vary from
$1,800 to $6,000 per year. In some cases the limit is a maximum
salary upon which a pension is computed. In other cases it
is a maximum per cent. of highest salary, in which case the figure
is usually from 60 to 75 per cent. so that few employers are
actually affected by it, because even under a three per cent. rate,
more than a 20-year period of service at least is necessary to reach
the maximum rate.[204]
The granting of a pension ordinarily does not debar the
pensioner from engaging in any other business. But in a few
cases the amount of annuity varies inversely with the income
from other sources. That it would, however, be practically impossible
for any employé to follow the line of work he could do
best and to which he was accustomed, is obvious from the provision
made by practically all concerns that he cannot engage
in any other business which may be prejudicial to the company’s
interest. Nor may he be further engaged by the same company.
Objections to industrial pensions are based on the following
grounds:
(1) They are generally opposed by organized labour
because it is said they are established largely for the
purpose of lessening the attractiveness of labour unions and
make men more loyal to their employers rather than to one
another.
154(2) Industrial pensions, it is also argued, are merely
deferred wages, and it is commonly known that wages are frequently
found to be lower in those industries which have the
best pension schemes. The Illinois Pension Laws Commission
concluded in its 1816 report that:
“Whether the contribution to a pension fund be taken wholly
from the employé’s wages or salary, or be paid wholly by the
employer, or be derived in part from each, these contributions are
in all three cases to be regarded as in reality a deduction from
wages and salary. The existence of a pension system in connection
with any position or employment is taken into account by
both parties to the contract of employment, and broadly
speaking, wages and salaries actually paid are in due course reduced
below what they otherwise would be by the amount of
the total contributions from both the employer and employé to a
pension fund. The employé will thus pay for his pension by deductions
from his wages or salary, whether he is conscious of
it or not. Indeed it is quite possible that with a sound fund in
existence the reduction in wages and salaries may in time materially
exceed the amount of the total contributions owing to the
advantages of such a fund to the employé under present economic
conditions. This consideration further emphasizes the advantage
to the employer of having such a fund established.”[205]
“In order to get a full understanding of the old-age and service
pensions, they should be considered as a part of the real wages of a
workman. There is a tendency to speak of these pensions as
being paid by the company, or, in cases where the employé contributes
a portion, as being paid partly by the employer and partly
by the employé. In a certain sense, of course, this may be correct,
but it leads to confusion. A pension system considered as part of
the real wages of an employé is really paid by the employé,
not perhaps in money, but in the foregoing of an increase in
wages which he might obtain except for the establishment of a
155pension system.... It seems to me on the whole that most of
the pension systems adopted by private employers are merely
very shrewd bits of wage bargaining. The absence of any contractual
right and the lack of assurance that a pension will be
paid upon fulfilling the conditions, gives merely the shadow of
provision for old age and not the substance.”
(3) Industrial pension systems prevent the mobility of
labour, often to the detriment of both the individual and the
community, and offer opportunities for arbitrary discriminations
against workers. The administration of these funds is
in most cases in the hands of the employer. As a result, notwithstanding
the definite regulations provided for the granting
of a pension, the latter is always contingent upon the nature
and loyalty of services rendered and the opportunities in the
hands of the employer for discriminations are evident. For,
while the employer is left free to discharge him, cut down his
wages or discriminate against him generally, the worker must
remain loyal at all times. He must not, for instance, take
part in any movement which the employer may consider detrimental
to his interests, such as associating himself with his
fellow workers, in order to increase their wages or improve
their working conditions generally. He not only can do
little to better his own conditions and those of his fellow
workers, but he cannot even leave his employment in order
to seek more suitable work, as it means losing his pension
privileges for which he has laboured many years. That
it is undesirable and even socially harmful to tie a man to his
job and discourage him from changing from one employer to
another is generally recognized and need not be emphasized in
this connection.
(4) Industrial pensions are also objected to because the age
for retirement is generally too high and the pension too low.
(5) In the case of many concerns there is no guarantee that
the pension promised will be lasting and permanent, even if
all requirements are lived up to, as practically all concerns reserve
156the right to either reduce the pension rate when the demands
are in excess of the sums fixed, or discontinue the entire
fund “without vesting any rights to such a pension to any
individual member.”
The Committee of the New York Merchants’ Association,
it is worthy to note, points out that pension systems that may
at any time be discontinued are immoral. It says:
“Even if the pensions are apparently the free gift of the
corporation, and the economic possibility of this for a considerable
period is doubtful, the employé is entitled to look forward with
assurance to the pension promise. A pension promise that is
not certain involves an uncertain morality.... To provide, as
is often done, that the corporation may wind up the pension
plan at any time without fulfilling the promises already made,
and then to expect employés to look forward with confidence
and order their lives upon the strength of these promises, is
certainly inconsistent. When the economic aspect of pensions
is considered, such retroactive power of revocation can hardly
be considered as moral.”[207]
While it is true that the very large industrial concerns are
not likely to terminate their pension systems without sufficient
notice there are nevertheless many of the smaller concerns which
are continuously facing such emergencies. A large industrial
concern in Pennsylvania in 1818 wrote to the Old Age Pension
Commission of that State:
“We have for many years paid pensions to a few of our employés
who had served long periods with our concern. We have
no regular system for this, however, and during the business depression
prior to the war, which hit us severely, we had to
suspend payment of these in some cases.”
That this situation is fraught with the greatest danger is
obvious. Mr. L. W. Squier addressed a letter to a corporation
reliably reported as having a pension plan in operation and it
157was returned unopened and stamped “Firm Dissolved.” He
comments
“The question naturally comes to the mind of the thinking
working man: What is the measure of the disappointment of the
scores, perhaps hundreds, of employés of the corporation who
were looking forward to pensions for the support of old age and
are now helpless and unprovided for? Such a condition is analogous
to that of the crew of a vessel who, after a long hard
voyage over dangerous seas with food exhausted, nerves racked
and strength almost gone, have only one hope left,—that of speedily
making an hospitable harbour; but alas, find themselves shipwrecked
upon a barren island.”[208]
(6) Industrial pensions are also objected to by some, on the
ground that they have a depressing effect upon wages, due to
the competition of returned pensioners who accept jobs for less
money because added to their pension their needs are more
readily satisfied. This objection, however, has little basis of
fact, as it is common knowledge that with most industrial
pensioners their life power had been already spent before retiring.
Indeed of the number retired on pensions by the United
States Steel and Carnegie Pension Fund in 1817, 15 per cent.
had died in the same year “indicating,” as commented on by the
manager of the Fund, “that they had given their full measure
of loyalty to the service.” At any rate, the fact of receiving
a pension would hardly make one a more dangerous competitor
in the labour market. One would certainly display keener
competition were he left starving at the age of 60 or 70, and
still able to perform some useful labour.
Other objections to these pensions are as follows: (7)
They generally make no provision for cases of total disability
when an employé has not served the required time. (8) Only
corporations employing wage-earners on a large scale can afford
to establish well defined systems of retirement. (8) Some
companies provide that the employés forfeit claim to pensions
158when leaving service, under strike orders. (10) Generally
before a pension is granted, one must have lived up to the most
stringent requirements and provisions.
The railroads were the first in this country to establish
retirement systems for their employés. This is, doubtless, explained
by the fact that railroad employés are very often required
to be under the most prolonged tension of both mind
and body. Men in modern transportation systems are subject
to greater hazards and wear out more rapidly than in
many other branches of industry. With the rapid and unprecedented
development of the American railroads, the problem
of what to do with the superannuated worker loomed up earlier
in this industry than in any other. Railroads in this country
thus began to establish private retirement systems about
the same time that European governments first engaged in
instituting systems of public pensions and insurance.
The main development in railroad pensions did not begin
until the early days of the present century. The Baltimore
and Ohio Railroad has the distinction of introducing the industrial
private pension system in this country.[209] Its pension fund
was established in 1888—the same year in which the government
pension scheme was adopted by Germany. More than a
decade passed before the next railroad—the Pennsylvania—saw
the necessity of following the example. The great majority
of the railroads have established a regular system of pensioning
since 1800.
What is true of the pension plans of the industrial concerns
is, in a descriptive sense, true of all the railroads, namely: the
administration of these funds is either by the direct control of
the board of directors of the various companies, or by a board
appointed by them, or by the president of the railroad. The
only exception to this is the Baltimore and Ohio Fund, which
159requires four years’ membership in the Relief Fund for eligibility
and which is controlled by the same executive committee
as administers the latter department. Such absolute control
is readily explained by the fact that excepting the Baltimore
and Ohio Fund the employés make no contributions to any
fund. The payments are entirely gratuitous on the part of
the company “as a reward for faithful services rendered,” and
the funds are therefore controlled by them.
As is the case of the industrial pension plans, a compulsory
and voluntary age of retirement is provided also in the transportation
systems. With very few exceptions the former is
set at seventy years. The period of service required before
an employé can retire on a pension differs. It ranges from ten
years to thirty years. Where the shorter period of service is
specified, however, it is generally provided that no person is
eligible to a pension who enters the service after 40 or 45
years of age. In a few cases the age of eligibility to service
is as low as 35 years. That the longer period of service is thus
necessary before a pension can actually be secured is obvious.
In the majority of railroad pension establishments, the difference
between the age when one is compelled to retire and the
period when one may retire voluntarily on account of physical
incapacity, amounts only to five years. Seventy being the age
of compulsory retirement, it is usually provided that an employé
may retire on account of physical incapacity between the
ages of 65 and 68. A few corporations, however, provide for
no set age or service but leave it to the discretion of the Board
of Directors to decide upon the merits of the individual case.
The differences in the terms of service required for the
granting of a pension by the industrial concerns and the various
railroads are significant. Twenty-five years of service
is the maximum set by the different industrial establishments.
Many require twenty or fifteen years of service and a few require
only ten years of service. In the case of railroad pensions,
however, twenty-five and thirty years of service is generally
160specified or implied. This difference may be explained
by the fact that the labour turnover is much greater in the
case of industrial firms and also because railroad lines are
more anxious and better adapted to retain employés for
longer periods.
With the exception of the Baltimore and Ohio Railroad,
practically all the railroads have an identical method of computing
the annuities awarded. Most railroads provide for a
pension computed upon the basis of one per cent. of the average
monthly wages for the ten years next preceding retirement,
multiplied by the number of years of service. Incapacity
annuities whenever provided are computed in the same manner.
Although a great number of establishments do not provide for
either maximum or minimum pensions, two hundred and fifty
dollars per month seems to be the highest limit set, while five
dollars per month is generally the lowest.
Only few railroads make provisions, by means of pensions,
for employés who have been injured and have become totally
disabled while performing their duties. These few concerns
state that an employé, in case of injury or total disability, may
be pensioned regardless of his age or length of service. The
majority of companies, however, make no provisions for such
employés before they have completed the required period of
service.
The transportation companies, as was indicated in the case
of the industrial concerns, generally specify that the granting
of a pension does not debar any employé from engaging in any
other business, but state that he cannot re-enter the service
of the company. The pension funds of the great majority
of railroads are fixed at a certain amount. It is also provided
by practically all of these concerns that “when basis of pension
allowance shall create demands in excess of the sums fixed, a
new basis, ratably reducing the pension allowances may be
established.”
Additional characteristics generally typical of these pension
161systems may be summarized as follows: In computing the
length of service it is usually specified that “leave of absence,
suspension or dismissal followed by re-instatement within one
year or temporary lay-off is not to be considered a break in the
continuity of service.” Practically all companies “reserve the
right to terminate pensions for gross misconduct” and “reserve
the right and privilege to discharge from service at any time any
employé without liability to a pension.” Some provide that
“employés who are dismissed from or voluntarily leave the service
of the company for any cause whatsoever relinquish all
claims to consideration or pension allowances.” Others specify
further that “employés’ forfeit claim to pensions when leaving
service under strike orders.” The objections offered against
the pension systems of industrial concerns are of course applicable
also to railroad pensions.
The efficiency of railroad pensions in the relief of the problem
of aged dependency among railroad employés may be judged
from the following figures which need no further comment. The
Pennsylvania Railroad with its nearly 300,000 employés had
retired on pensions from January 1, 1800, the time of the inauguration
of the plan, to December 31, 1818, a total of 8,128
employés. The Philadelphia and Reading Railway Company
pensioned from 1802 to 1820, a total of 876 employés. The
New York Central, and all its associated railroads, pensioned
2,828 employés during the first ten years’ existence of the fund—1810–1820.
From October, 1884, to March, 1820, a period
of 36 years, the Baltimore and Ohio Railroad retired on pensions
only 2,758 of its employés.
162
The problem of the aged government employé is of paramount
importance, especially from the viewpoint of the tax-payer.
There can hardly be a greater waste of the tax-payer’s
money than to retain on the pay rolls of our Federal,
State, and Municipal services, men and women who have long
outlived their usefulness. Furthermore, the continuation in
the employ of our government at full wages of old men and
women who are no longer capable of rendering efficient service
is not only a waste of money but is demoralizing to the entire
service. The burden of this “dead weight” carried on government
pay rolls becomes especially pernicious as the volume of
work continuously increases and as newer methods and higher
standards of efficiency are introduced into the administration
of our governmental departments.
The full extent of the government’s burden in this respect
cannot be definitely determined. That there are few governmental
departments, however, whether Federal, State, or Municipal,
whose efficiency could not be greatly improved by replacing
the older and less able employés with younger men who
are more adaptable to the newer methods of work, is a fact
known to all. In one Federal department it was estimated
that 250 people could do the work at present performed by
1,000 superannuated employés. “Some of these were said to
be working at only 80 per cent., 50 per cent., 25 per cent., and
even nearly as low as zero per cent. efficiency.”[210]
163Former Secretary of the Treasury W. G. McAdoo in 1817
declared: “The Treasury Department bears upon its rolls a
large number of aged employés whose efficiency is gradually
waning.” Former Secretary of Commerce Redfield also corroborated
this by stating: “that the efficiency of the executive
civil service is seriously impaired by reason of its superannuated
employés, is a fact conceded by practically all persons
who are at all familiar with the problems of the service.” The
burden of dead wood carried on the pay rolls of the different
States and municipalities, where civil service requirements are
less strict than that of the Federal government, or do not
exist at all, is doubtless even greater. The Massachusetts
Commission on Old Age Pensions, in co-operation with the
Mayor of Boston, made a study in 1808 of the aged employés
of that city and the results found, as given in the report of
the above Commission, were as follows:
“The total number of employés over 65 years is 481; over 70
years, 168. The amount of compensation paid to employés over
65 is $418,888.45; over 70, $273,888. The number over 65
reported as inefficient is 286. The compensation paid to this group
is $200,184.35.
“The percentage of inefficient employés among the employés
over 65 years is strikingly large in many departments. For example,
in the cleaning and watering division of the street department
35 are employed, of whom all are reported inefficient; in the
cemetery department 16 persons over 65 years are employed, of
whom all are reported as inefficient; in the park department 27
are employed, of whom 24 are inefficient.
“The period of service is over 30 years in the case of 118 employés
over 65, or 25 per cent. of the total. Only five per cent.
or 42 persons, have been in the employ of the city less than five
years.
“The leading departments, in respect to number of pensionable
employés, rank as follows: (1) paving division of street department,
108 over 65 years; (2) water department, 65; (3) Sanitary
department, 47; (4) cleaning and watering division, street
164department, 35; (5) park division, 27; (6) ferry division, street
department, 26; (7) cemetery department, 16.”[211]
As an employer of labour, however, the government can
least afford to set the example of discharging outright and
turning adrift, or carting off to the poorhouse those employés
who have grown old in the service and who have spent the best
years of their lives and have given of the best they possessed
to the service of the Nation, the State or the Municipality.
It has long been the policy of nations to provide relief in old
age to soldiers and sailors who hazard their lives in the defence
of the nation in times of war. Is it not obvious also, that the
work done by the armies of the various government employés in
maintaining the orderly process of government, so essential to
the peace and welfare of the country, as well as to the protection
of life and property of their fellow-citizens in time of
peace is no less important and essential a service to the nation,
and as such, merits some sort of protection against the days
when they are no longer able to render efficient service or to
provide for themselves? In the case of our municipalities especially,
where many thousands of common labourers are
employed who in many instances, are paid a lower rate of
wages than that paid in local private industries, the problem
of retirement seems most pressing. These men who are known
to do the “dirty work” of our cities which is essential to the
health and welfare of all residents, are obviously least able to
provide for old age. That these men who are responsible for the
maintenance of sanitation and of the manifold other comforts
furnished by our modern cities, and who loyally and faithfully
serve the municipality under all sorts of conditions through
the best period of their lives, should not be left helpless in
their old age is so manifestly a matter of justice that it would
seem superfluous to stress it further.
165The problem of the superannuated government employé must
not, however, be considered solely from the viewpoint of justice.
Evidently, what is recognized as “a good business policy” for
private employers ought to prove of profit also to our national,
state and city administrations, in their respective capacities
as employers of labour. The advantages of retiring
aged workers on pensions are now recognized by all progressive
employers of labour. This is witnessed by the rapid
development of these systems within recent years as was shown
in the preceding chapter. Their small number may be accounted
for by the fact that only large employers are able
to establish regular pension plans. The establishment of such
a system for government employés would afford an opportunity
not only to raise the standards and enhance the quality
of service rendered, but would also act as an incentive to attract
better ability to the particular line of work. The heads of the
executive departments of the government have long recognized
the importance of a retirement provision for civil service employés.
Urging the adoption of such a plan before the U. S.
Senate Committee on Civil Service and Retrenchment,[212] former
Secretary of War Newton D. Baker said:
“The effect of such a law would be to give an assurance of
a competent and comfortable old age. It would relieve the employés
from the fear of loss of occupation and of livelihood, would
further inspire them to loyalty to the Government as an employer,
thus improving the general quality of the service rendered by
the Government employés, and would permit the replacement of
some employés in the various departments who have long and
faithfully served the Government and reached venerable but enfeebled
years without having had an opportunity to accumulate
any competence upon which their retirement can rest.”
Secretary of Commerce Redfield declared:
166“Efficient service and justice to the employés demand a comprehensive,
wide-reaching, and effective scheme of retirement pensions,
the advantage of which is being more and more widely recognized
by progressive commercial establishments and by foreign
governments.”
Former Secretary Wm. B. Wilson, of the Labour Department,
wrote in his Annual Report:
“In a previous report of the department attention was drawn
to the difficulties confronting executive officers of the Government
impelled in the interest of a good administration to dispense with
the service of employés whose efficiency has been materially impaired
by advanced years. On the other hand, they are met with
the fact that the business of the Government could be more
efficiently handled by active persons, whereas on the other hand
there looms up before them the spectre of hardship and in many
cases absolute want, which would be enforced upon faithful servants
if they were thus to be summarily removed from the only
means of gaining a livelihood for which through years of training
they are qualified.
“It is inevitable, therefore, that until such times as heads of
departments can accomplish this change in the personnel without
visiting undue hardship upon their subordinates they will be deterred
by a consideration of the humanitarian phase of the matter
from taking such action as the situation seems to demand.
“The department accordingly reiterates its recommendation that
there be provided through legislative enactment an equitable system
of retirement—a system which will best subserve the interests of
efficiency and economy and at the same time insure fair financial
provision for those who through long and faithful service are entitled
to some consideration in their declining years.”[213]
Former Secretary of the Treasury W. G. McAdoo also
stated:
“The need for an adequate civil-service retirement law is becoming
more imperative each year. The introduction of new and
167improved methods of performing the constantly increasing volume
of work in the department has served to emphasize the need for
making some provision for the older employé who is unable to keep
step with progress. It does not seem humane or fair to discontinue
arbitrarily the service of superannuated employés who have given
their entire energies and spent the best years of their lives in the
service of the Government. To do so would in most cases leave
the employés without any source of income and result in serious
hardship. To reduce aged employés does not entirely meet the
need of the case, as it leaves the employé on the rolls of the department.
“I believe that the enactment of an equitable retirement law
for superannuated and disabled employés of the civil service in
the Treasury Department would result in actual economy and
increased efficiency in the handling of the business of the department,
and I therefore recommend this subject to the Congress for
its serious consideration.”[214]
During the past two decades practically every Congress
has had presented to it a bill providing for retirement of the
employés in the United States Service. Furthermore, Presidents
of the United States, Cabinet officers, the United States
Civil Service Commission and heads of executive departments
have repeatedly advocated and pleaded for the adoption of
some such measure. Among the chiefs’ of the government departments,
as was seen, there has been unanimous agreement
on the necessity for a pension provision for Federal employés
by means of which the continuously serious growing problem
of superannuation could be remedied to some extent. Notwithstanding
the pleas of high government authorities, as well
as the energetic campaigns carried on by the organized employés
of the United States, and by other social agencies, it
was not until the end of the sessions of the Sixty-sixth Congress—in
the spring of 1820, in the face of a presidential election—that
168the national legislature finally saw the necessity
of adopting such a plan. For many years the government
employés bitterly complained against the inactivity of Congress
and accused the members of the Federal legislature of
fear that such a measure would be unpopular among their constituents
at home.
The need of finding a solution to the problem of superannuation,
in order to preserve at least some standard of efficiency
in government departments, was becoming graver day
by day. At the same time many of the employés of the government
who had faithfully given the best part of their lives
to the service of the nation were, when they had become too
old, mercilessly separated from the service. These employés,
broken in body and spirit, were turned adrift penniless in
their old age to shift for themselves as best they could, and
stand out as inspiring examples for the future loyalty of service
on the part of their fellow workers who were on the threshold
of old age. No pen picture can accurately visualize the
sufferings of such men who have been turned adrift in their
helplessness and compelled to face the poorhouse as the only
place of refuge. A glimpse of the fatalism of some such men
and the bitterness of feeling developed by others may be
gleaned from the following letters:[215]
Washington City Post Office,
Office of the Postmaster,
April 18, 1814.
Mr. John B. Lerch,
Clerk, Mailing Division,
Washington City Post Office,
Dear Sir: In view of the fact that your services are of little
value to the office, due to your impaired efficiency, on account of
169advanced age and physical infirmities, I regret having to inform
you that your name is under consideration for separation from the
service. Any statement which you may desire to make in the
premises will receive careful consideration if submitted within five
days after the receipt of this letter.
Very respectfully,
Otto Praeger, Postmaster.
To Mr. Praeger’s communication Mr. Lerch made the following
reply:
Hon. Otto Praeger,
Postmaster, Washington, D. C.
Dear Sir: Yours received, and in reply I have to say that by
the recommendation of Abraham Lincoln, President of the United
States, I was appointed a clerk in this office April 1, 1865.
It is not my place to defend my ability to do my work; for this
you please must inquire of my superior officers.
I am 81 years old, but my record will show how little time I
have lost on account of sickness in all these years, and I firmly
believe that I am still able to perform work to the satisfaction of
those over me. Furthermore, I have to inform you that, through
misfortune, I am penniless, my wife having been a helpless invalid
for the last 15 years.
One thing is sure, if I have to go out of this office I do so with
a clear conscience that in all my service I have done my duty faithfully.
(signed) John B. Lerch.
Another post office clerk, in San Francisco, noticed the
following item in the Union Postal Clerk:
“Rodney, a faithful Army horse, who has served the Government
steadily for 20 years is to be retired from active duty and
cared for by Uncle Sam for the rest of his life. This will be
done on recommendation of Capt. C. D. Mortimer, Third Field
Artillery. Rodney was never sick a day, rendered signal battle
service in the Spanish-American War, was sold at auction as too
170old for service, was bought by a member of the Third Field
Artillery for $107, rendered hard service at Fort Myers, and is
now pensioned.”
And he writes to the Secretary-Treasurer of his Union:
My dear Mr. Flaherty: I see by the February number of the
Union Postal Clerk that after many years’ service the Government
has pensioned an old horse. All I can say is “Lucky old
horse,” and for the purpose of drawing a pension it would have
been better had I been born a horse than a human being. I have
been a “wheel horse” for the Government for the past 50 years
and can not get a pension.
(signed) John W. Perry.
And Mr. Flaherty adds some information, and comments:
“After 50 years a clerk in the San Francisco Post Office, entering
the service in 1861, and on the very day he completed his
golden anniversary of 50 years’ service he was told he was inefficient
and would have to take indefinite leave of absence, without
pay of course, and now he is unable to get back in the service.
He is 80 years of age, has devoted 50 years, 50 productive years
of his life, all this time devoted to the perfection and management
of the Postal Service. Only in the ranks, unknown and unheard
of, a minor cog; but I know that it is men like Perry who
made our Postal Service what it is today—the most efficient mechanically
of any government institution, and I emphasize mechanically.
It is not humanely efficient. It has not yet developed any
system whereby the dismissal of these old men can be eliminated.”
The reports in regard to the effects and the working out of
the recent Sterling-Lehlbach Act of Congress providing for
the retirement of employés in the classified civil service, are
expected to yield some very valuable data on the problem of
Old Age Pensions. As these lines are written, however, the
law has just become operative and predictions in this respect
would be of no value. The law provides for the compulsory
171retirement on a pension of all employés in the classified civil
service of the United States who have reached the age of 70
years and have rendered 15 years’ service. Mechanics, letter carriers
and post office clerks are eligible for retirement at 65,
while railway postal clerks may retire at 62 years of age after
they have rendered at least 15 years of service. An employé,
if he so desires, may, at the discretion of the head of his
department and approval by the Civil Service Commission, be
continued in his position beyond the retirement age for a period
of two years and at the end of that period may be continued
for another two years and so on until ten years after the act
has become effective when it is provided that no employé shall
be continued in the service for more than four years beyond
the age of retirement.
The Pension Law just enacted provides for a compulsory-contributory system of retirement. All employés are made
to contribute two and one-half per cent. of their income, which
is deducted from their monthly salaries or wages, by the Treasury
Department, and which goes to help make up “the civil service
retirement and disability fund.” This contribution, it is
estimated, will cover about one-third of the expenses of the act.
The remaining two-thirds will be paid by the government as
its contribution. The entire cost of this retirement provision
was estimated by Senator Smoot to probably amount to over
$2,000,000 for the first year increasing steadily to amount to
more than $18,500,000 in the 77th year of its operation.
The amount of the pension is generally based upon two per
cent. of the average annual salary multiplied by the number of
years of service. Thus Class A after thirty years of service
receive a pension amounting to sixty per cent. of their yearly
salary; Class B, twenty-seven years of service fifty-four per
cent. of salary; Class C, twenty-four years of service forty-eight
per cent. of salary, etc. The maximum amount of pension,
however, is set at $720 which is sixty per cent. of an
annual salary of $1,200 and which means that while the higher
172paid men contribute proportionately more for their annuities,
they can receive no pension on salaries above $1,200 per year.
There was little objection to this on the part of the higher
priced men as they were glad to forego larger annuities for
the sake of getting the needed pension system adopted. The
minimum pension is set at $180 per year.
The Sterling-Lehlbach Act also provides benefits for those
who become disabled before reaching the retiring age. This
must be preceded by proper medical examination certifying
that the disability is “not due to vicious habits, intemperance,
or wilful misconduct.” The amount of the pension is computed
in the same manner as provided for the regular pension.
No benefits are paid for less than fifteen years’ service.
In the case of withdrawal from the government’s service,
or death before the pensionable age, or if an annuitant dies
before he has received benefits equivalent to his contributions
and accumulated interest, his contributions or the difference
in his contributions is to be returned to him or his legal heirs
in a lump sum, together with four per cent. compound interest.
The Commissioner of Pensions under the Secretary of Interior
is charged with the administration of the Act. In case of a
complaint an appeal may be taken from the Commissioner of
Pensions to the Secretary of Interior.
In contrast with the, until recently, lamentably deficient provisions
for old age assistance, and the total neglect by the government
of its permanent and peace time employés, must be
considered the exceedingly generous care the government has
taken of those who had given it temporary service during times
of war.
“After all,” says Dr. Rubinow, “it is idle to speak of a popular
system of old age pensions as a radical departure from American
traditions, when our pension roll numbers several thousand more
173names than that of Great Britain. It is preposterous to claim that
the cost of such a pension would be excessive, when the cost of our
pensions is over $160,000,000, or more than three times as great
as of the British pension system. In the face of such a cost, it is
childish to consider the system of war pensions as a sentimental
problem only, and to speak of the millions spent for war pensions
as the cost of the ‘Civil War’. We are clearly dealing here with an
economic measure which aims to solve the problem of dependent
aged and widowhood. No state legislator will claim, unless it be
in a peroration to a fourth of July outburst of oratory, that the
constant pressure for extension of war pension benefits, and the
systematic political work which creates such pressure, which neither
party has had the courage to resist—is all the result of patriotic
enthusiasm only. It is necessary to face the situation frankly,
and apply to the system of war pensions the ordinary standard
by which any piece of legislation is judged, inquire how far it
meets the problems, how efficiently, economically, and justly it may
work for their solution.”[216]
The amounts spent on war pensions in the United States
are startling. Since the end of the civil war—1866 to June
30, 1818—the total amount paid out in pensions, exclusive
of the cost of maintenance of the Pension Bureau, was $5,521,074,858.16.
In 1866 there were 126,722 pensioners and the
annual expenditures on pensions amounted to $15,450,548.88.
The number of pensioners was highest in 1802 when it reached
almost the million mark. Since that time the number has been
steadily declining. The total number of pensioners in 1818
was only 624,427. The total amount paid out in pensions, however,
has risen from year to year. In 1802 when there were
888,446 pensioners the amount paid out in pensions was only
$137,504,267.88, but in 1818 the total amounted to $222,158,282.70.
Furthermore, although there were 22,368 pensioners
less at the end of the fiscal year of 1818 as compared with the
previous year, the amount paid out as pensions increased from
174$178,835,328.75 in 1818 to $222,158,282.70 in 1818, which is
an increase of $42,323,863.85 in one year.
Practically every Congress sees some new War Pension
legislation enacted, whether by the passage of general or of
special acts. At the close of the fiscal year ended June 30,
1818, the number of pensioners in each class under the general
pension law and special acts of Congress was as follows:
Classes
Number of Pensioners
Regular establishment:
General Laws
Special Acts
Invalids
14,128
527
Widows, etc.
4,104
458
Act Feb. 6, 1807, survivors
578
Act May 11, 1812, survivors
260,127
General Law, Civil War:
Invalids
6,288
4,180
Widows, etc.
38,552
4,585
Act June 27, 1880:
Invalids
267
Minors, etc.
2,205
Act April 18, 1808, widows
250,471
Act Aug. 5, 1882, nurses
81
38
War with Spain:
Invalids
21,881
1,481
Widows, etc.
3,488
316
Act July 16, 1818, widows, etc.
War of 1812, widows
1,065
8
War with Mexico
73
Survivors
207
8
Widows, etc.
2,577
164
Indian War:
Survivors
3,388
38
Widows
1,864
63
War of 1817:
Invalids
60
1
Widows, etc.
54
Total
612,528
11,888
During the same year the following pension amounts were
paid out on account of the different wars:
Civil War
$212,211,880
War with Spain
3,878,188
War of 1812
17,704
War with Mexico
758,156
Indian Wars
1,561,537
175Regular establishment
3,701,782
War of 1817
30,081
Total
$222,158,288
The average amount of the pension of the different wars
during the fiscal year 1818 was as follows: Civil War, $373.38;
War with Spain, $137.28; War of 1812, $218.57; War with
Mexico, $256.48; Indian Wars, $285.84; Regular Establishment,
$182.62. The average amount for all pensions was
$355.78 per year. In 1820, Congress further increased the
pensions of civil war veterans to $50 monthly and those of
widows of veterans to $30 per month. This was estimated
to add about $65,250,000 to the present pension budget. Veterans
of the World War are cared for by the War Risk Insurance
Bureau which is expected to prevent the burden of war
pensions from falling as heavily upon the taxpayers as in
previous wars.
That Congress in passing war pension legislation has practically
never taken cognizance of the economic necessity of
such pensions has been demonstrated so frequently and is so
generally known that there is little need for its lengthy discussion
here. The best indictment against the Congressional
policy with regard to war pensions is brought by Dr. Rubinow,
who comes to the conclusion that: “the most singular feature
of the American System is that it primarily rebounds to the
advantage of a class least in need of old age pensions.” He
states:
“The extensions (of war pensions) were based primarily upon
a more lenient attitude towards the requirement of past services
and records rather than upon any effort to adjust this annual distribution
of enormous sums to economic need. As a result the
preposterous situation is created that various sized portions of this
official melon are given to thousands of people who may not at
all require it. No satisfactory statistics on this point exist, but it
is a matter of common knowledge not only that pensions are obtained
upon fraudulent representation of past services, forged records,
176fictitious marriage certificates, etc.,—an aspect of the problem
sufficiently important in itself, which need not be discussed here at
any length however,—but what is economically much more important,
a large proportion of this amount goes to individuals who have no
economic need whatsoever of financial assistance.”[217]
It is a fact known to all that but few of those who are now
receiving United States Pensions are really in need of them; nor
do those who receive pensions represent the most needy class.
The present war pension schemes reach largely the native aged
who are generally representative of the middle class of this
nation. The great bulk of wage-earners, which is made up
largely of the foreign born Negroes, benefit little or nothing
from such pensions. War pensions as a method of relief
in old age for the great mass of aged wage-earners, despite
their tremendous cost, are obviously inadequate and ineffective.
As pointed out by Rubinow in conclusion:
“The economic effects of the war pensions have been so carelessly
treated in the pension legislation that it surprises no one to
find a war veteran drawing a substantial salary as a public employé
(after having obtained the appointment under privileged
conditions), and at the same time his war pension for disability; and
perhaps the most striking and ludicrous example of this was the
well-known case of a prominent veteran, who some years ago received
one month a high pension especially voted by Congress
because of total and permanent incapacity, and immediately
after that an important and responsible position in the Federal Civil
Service, which carried with it a salary of $3,500 per annum.”[218]
Massachusetts is practically the only State in the Union
which has established (since 1812) a system for the retirement
of State employés exclusive of employés of counties and municipalities.
A number of States, namely, Louisiana, Maine,
177Maryland, Massachusetts, Minnesota, New Jersey, New York,
Rhode Island, and Pennsylvania, have had pension systems for
State judges of the Supreme, Superior and other courts, as well
as for certain limited classes of State employés, for some time.
The New York provision for judges’ pensions applies also to all
employés of the supreme court of the first, second and ninth districts.
The latter also requires a contribution of one per
cent. of the annual salary of the employés. All the other state
pension provisions are non-contributory and the amounts of
the pensions vary from one-half to the full salary of the pensioner.
Most plans set the retirement age at 70 years but in
case of disability retirement is generally permitted at an
earlier age.
The Massachusetts Retirement Plan for state employés
enacted in 1811 represents a compromise between the contributory
and non-contributory principles. In the Bay State
system both the State and the employés share the expense of
the retirement system equally between them. The employés
are required to contribute regularly from their wages or salaries
in accordance with the rate set by the administering
board. It is provided, however, that this is to be not less
than one per cent. nor more than five per cent. of the annual
salary or wage.
The voluntary retirement age is set at 60, and at 70 years
the retirement is compulsory. An employé may also retire
after 35 years of continuous service, regardless of age. The
annuity is computed as follows; First, he receives an annuity
of such amount as his own contributions have earned for him,
and, secondly, a pension from the State which is equivalent
to his own annuity. The total amount of the retirement
allowance including the annuity and pension cannot be less
than $200 nor to exceed one-third of the annual salary.
The system is administered by a board of three members
which includes the State Treasurer, a second member elected
by the employés and a third chosen by the former two. Participation
178in the plan was made compulsory for all employés
who entered the service after the fund had been established,
but was left voluntary for employés who were in the service
at the time the law was enacted. More than half of the latter
class of employés, however, joined the fund when the act went
into effect.
The Massachusetts Retirement Act also provides that the
contributions of employés be refunded upon leaving the service
of the State before the pensionable age. Since the establishment
of this system, it is claimed by reliable authorities, it has
worked to the satisfaction of both employés and administrative
officials. It is stated[219] that it has brought about an improvement
in the efficiency of the service through the retirement
of inefficient employés and has created a feeling of greater
well-being and security on the part of employés of the State.
The movement for the pensioning of municipal employés,
such as policemen and firemen, although it came later in the
United States than in European Cities, has nevertheless, preceded
the entire campaign of old age retirement provisions
for all other classes of workers. In the United States this
movement is about fifty years old. Municipal employés’ pensions
being the earliest to be adopted in this country, it is
therefore, not surprising to find these funds the most haphazard
and unsystematic of pension experiments. In reviewing
these numerous pension funds one fails to detect any consistency
179with regard to either general principle, system, or
standard, and excepting the very recent ones, practically
none have given much thought or consideration to actuarial
principles. Almost every pension scheme in operation is the
product of a long process of amendments and modification which
it has undergone since its original establishment. To cite
a few instances: the Pittsburgh Firemen’s and Policemen’s
funds were amended a number of times since their establishment
in 1883 and new amendments are further considered.
In Cleveland, before the establishment of the city’s present
Police Fund, the latter was operated under three different
plans, with a total of ten amendments. In New York City
the Firemen’s Pension and Benefit systems were amended forty
times before the general consolidation with the funds of other
boroughs took place a few years ago. In October, 1820, a
new law went into effect creating the New York City Employés’
Retirement System, dividing the municipal employés
into three classes: labourers and unskilled workers, mechanical
and skilled workers, and clerical, administrative, professional
and technical workers, including heads of departments.
No less confusing and chaotic are the administration and
the classes of workers protected by these municipal funds.
Some of these are administered in connection with State or
County funds, while others are administered by the city alone.
Again, certain classes of city employés are well taken care of
and others neglected by some cities, while other cities act vice
versa. Only very few cities, however, make provisions for the
general municipal employés exclusive of firemen, policemen and
teachers. There is also a great difference to be found in
regard to the principles of contributory and non-contributory
schemes, and where contributions are provided, they generally
range from one to three and one-half per cent. of the salary.
The annuity paid also varies from one-half to three-fourths of
the salary at time of retirement. The retirement age is not
180specified in many funds, depending largely on the years of service.
Where age provisions are made they range from 55 to
70 years, and where the length of service necessary for retirement
is stipulated it is usually about twenty years. In a number
of cases benefits are also provided for widows and dependents.
In one-third of the 167 firemen’s and policemen’s funds analyzed
by the United States Bureau of Labour in 1810 the annuity
was an entirely gratuitous gift of the municipality, while in
the other two-thirds the funds were made up in part by the
municipality and in part by contributions from the employés.
In the funds studied by the above Bureau it was found that
in about 40 per cent. of these the sole qualification for pensions,
on the part of firemen and policemen, was permanent
disability incurred while in the performance of duty regardless
of age or service. The other 60 per cent. usually specified
the length of service at about 20 years, coupled in one-third
of the funds with qualifications of age 50, 55, 60 or 65 years.
In only about 40 per cent. of these funds were the employés
found to have representation in the management of the foundations.
Twenty funds were also found to pay benefits for
temporary disability; 36 paid a lump sum death benefit and
113 paid annuities to widows or to other dependents. Where
payment was allowed for temporary disability it was generally
half of the permanent annuity. Aside from these municipal
funds there are also to be found in most localities
mutual benefit associations which pay temporary and death
benefits and to which the majority of firemen and policemen
contribute.
In addition to the regular contributions to these funds made
by the municipalities and employés, there is also a miscellaneous
source of revenue such as: “fines on policemen” or
“fines on firemen,” which include not only fines imposed for
violation of duty or regulations but also deductions made from
pay for lost time, etc. Other revenues are such as “unclaimed
181property” and “unclaimed money” which include lost, stolen,
or abandoned property in the possession of the police department.
Many municipalities provide also that the city’s or
State’s contributions to these funds shall be secured from
a special revenue such as taxes on excise, insurance companies,
etc.
Complete municipal pension systems including policemen,
firemen, teachers and all municipal employés are in operation
in the following cities:
New York
Chicago
Philadelphia
Boston
Pittsburgh
Minneapolis
Oakland, Cal.
Lowell, Mass.
Lynn, Mass.
Yonkers, N. Y.
Waltham, Mass.
Brookline, Mass.
Harrisburg, Pa.
Pensions for policemen, firemen and teachers only, exclusive
of other municipal employés, exist in the following cities:
St. Louis
Cleveland
Baltimore
Detroit
Buffalo
San Francisco
Milwaukee
Cincinnati
Los Angeles
Newark
New Orleans
Washington
Jersey City
Seattle
Indianapolis
Providence
Portland
Rochester
Denver
Louisville
St. Paul
Columbus
Toledo
Worcester
Passaic
Charleston
Elmira
Syracuse
New Haven
Scranton
Paterson
Omaha
Hamilton
Auburn
Mt. Vernon
Dayton
Cambridge
Trenton
Albany
Duluth
Niagara Falls
New Rochelle
La Crosse
Utica
Troy
Hoboken
South Bend
Terre Haute
Watertown
The following cities have pension schemes for only one class
of municipal employés, i. e., either that of teachers, policemen,
firemen, or other municipal employés:
Atlanta (M. E.)
Fall River (P.)
Salt Lake City (T.)
Reading (T.)
Oklahoma City (F.)
San Diego (P.)
Malden (F.)
Berkeley (P.)
Chicopee (P.)
St. Joseph (F.)
Wilkes-Barre (T.)
Jacksonville (P.)
Jamestown (F.)
Bayonne (F.)
Fitchburg (M. E.)
Topeka (P.)
Allentown (F.)
Lima, Ohio (F.)
Altoona (F.)
Pawtucket (P.)
Binghamton (F.)
York (F.)
Montgomery (F.)
Joliet (F.)
182Quincy (P.)
Bay City (F.)
Shreveport, La. (F.)
Santiago (P.)
Woonsocket (P.)
Norwich, Conn. (P.)
Decatur, Ill. (F.)
Meriden (P.)
Kingston (P.)
Pensions for teachers and firemen or teachers and policemen
only are to be found in these cities:
Wilmington
Poughkeepsie
Lancaster, Pa.
Newburgh
Perth Amboy
Newport
Pittsfield
The following cities have pensions for policemen and firemen
only:
Birmingham
Spokane
Grand Rapids
Nashville
Bridgeport
New Bedford
Hartford
Camden
Tacoma
Des Moines
Council Bluffs
Zanesville
Richmond
Youngstown
Elizabeth
Waterbury
Akron
Peoria
Fort Wayne
Savannah
Brockton
Portland, Me.
Holyoke
Waterloo
Elgin
Haverhill
Kansas City, Mo.
Springfield, Ill.
Mobile
Sacramento
Saginaw
Sioux City
Atlantic City
Rockford
Augusta
Springfield, Ohio
New Britain
Chattanooga
Bloomington
Clinton, Iowa
Salem
Springfield, Mass.
Davenport
Racine
Newton
Superior
Dubuque
Galveston
East Orange
Cedar Rapids
Jackson, Mich.
Aurora, Ill.
Lorraine, Ohio
Colorado Springs
Madison, Wis.
Stamford
Chelsea
The cities of Memphis and Dallas have authorized the establishment
of retirement funds, but did not establish such in the
period studied. San Antonio had neither established nor
authorized one when this investigation was made.
As seen in the preceding enumeration, every one of the
eighteen cities in the United States with a population of more
than 300,000 inhabitants, in 1810, has a pension fund for its
policemen and firemen. The six cities with 200,000 to 300,000
inhabitants also pension their policemen and firemen. Nearly
all the cities with populations between 100,000 and 200,000
have some form of pensions for one class or another of municipal
employés. In addition, many of the smaller cities also
provide one form or another of retirement for particular groups
of their employés. Thus thirty-nine of the fifty-four cities
with populations from 50,000 to 100,000 have some sort of
183pension plan, thirty-one of them pensioning both policemen
and firemen. Of the one hundred and twenty cities whose
population in 1810 ranged from 25,000 to 50,000, only 68 have
any definite pension plan. Fifty-eight cities whose population
according to the thirteenth census was less than 25,000
also have either established municipal pension funds or have
been authorized to do so. While policemen and firemen are
thus fairly well protected in their old age, only a few of the
bigger cities—New York, Chicago, Philadelphia, Boston, Pittsburgh,
and Minneapolis—have thus far made provisions for
their other municipal employés, who constitute the great bulk
of city servants.
The two primary functions of old age retirement systems
are: First, the protection of individuals and their dependents
against the contingencies of old age and disability. Secondly,
the provision of a means of improving the efficiency and raising
the standard of the services rendered, by eliminating from the
service the superannuated and disabled who are no longer efficient,
and by attracting better ability into the particular service.
It is hardly necessary to point out, that nowhere are
these functions of greater significance than in our educational
system. It is of paramount importance that the best available
talent and ability, and that superior men and women
should be attracted to our schools for the development of the
moral character and ideals of our children. It is further evident,
moreover, that teachers living continuously in the dread
of old age are not the most desirable persons for the instruction
and inspiration of our younger generation. To provide
our teachers—the moulders of the future generation—against
the day when they are no longer able to provide for themselves,
becomes thus not only a matter of justice but an essential
factor in the welfare and high standard of our school system.
In the case of teachers the problem of relief from superannuation
184is even more aggravated. It is an admitted fact that our
teachers form one of the most inadequately remunerated classes.
In many instances, indeed, although their wages are on par
with the lowest compensated groups in the particular community,
a comparatively high standard of living is required of
them. Sufficient saving for old age under the circumstances
is thus out of the question. To this must be added the obvious
fact that many in the teaching profession—especially is this
the case with women teachers—remain unmarried, and ordinarily,
have no one to depend upon in old age, which aggravates
their problem of superannuation.
It is, therefore, rather surprising to learn that although the
United States led the world in establishing compulsory education
laws at public expense, it is one of the last to make provision
for the care and relief of superannuated and aged teachers.
While Russia, under the Czar, established a system of
relief for its aged teachers as early as 1818, the first legislative
interest in retirement systems for teachers in this country
did not come until 1884, when New York City teachers
secured the passage of a retirement law in the New York
Legislature.
According to Mr. Studensky,[220] the history of the movement
for teachers’ retirement pensions in the United States may be
divided into three distinct periods. (1) The period from
1868 in which there first began the establishment of teachers’
insurance and mutual aid associations. (2) The period from
1884 until approximately 1815. This was a period of retirement
legislation without regard to sound principles and is still
not altogether a matter of the past. (3) The movement just
beginning, tending to the reorganization and remodeling of
pension systems on a more sound actuarial basis. In the first
two periods the government and the public remained indifferent
to the voluntary funds established by the teachers themselves.
The funds were regarded as private teachers’ associations
185in which the public had no concern. Since 1815, however,
the government has taken an active and intelligent participation
in the protection of teachers in their old age, as it
has begun to recognize the value of such provisions both for
the welfare of our educational system as well as for the protection
of the teachers.
In the beginning, teachers’ protective associations were
formed largely for the purposes of securing burial or death
benefits. These loosely established organizations required no
regular assessments, but assessed their members from fifty
cents to a dollar whenever necessary. Permanent capital they
considered unnecessary and therefore had none. Later these
burial and death benefit associations branched out to include
also sick benefits for a limited period. This resulted in the
introduction of a regular system of dues payments which
ranged from one to seven dollars per year. As they progressed
they were still further extended to provide for old age
and disability annuities, and regular contributions based upon
one or two per cent. of the annual salary were introduced. The
teachers’ contributions were generally swelled by donations
from charitable agencies and incomes from “benefit entertainments”
arranged for the funds.
Government participation in teachers’ retirement systems
first began in 1884. By this time the teachers realized the
failure of their voluntary associations and requested the assistance
of the city government. They were encouraged and stimulated
to ask for this help by the fact that the city had
already established pensions for other municipal employés, such
as policemen and firemen. They justly called attention to the
benefits derived from such systems in removing the dead wood
of the school system, as well as increasing the efficiency of
teachers, which would result in such a plan. As a result of
this campaign the New York Legislature in 1884 provided
for the establishment of a teachers’ retirement fund. The
resources of this fund were to come, on the part of the teachers
186themselves, only from deductions made from the pay because
of absence. The teachers were not required to make direct
contributions. In the following year or two, similar funds
which, however, required contributions from teachers, were established
in Brooklyn, Detroit, Chicago, St. Louis, San Francisco,
Buffalo, Cincinnati and the State of New Jersey. Most
of these plans were compulsory in character and the teachers’
contributions amounted to one per cent. of their salary.
As practically none of these plans took any account of
actuarial principles of insurance, it soon became evident that
the teachers’ contributions alone were not sufficient. It did
not take long to discover that in practically all of these systems
no provision was made for permanent capital, and the funds
needed to meet obligations as they arose “were provided only
by hopes.” The teachers then began to ask for direct contributions
from the cities or states, pointing out the benefits
to be derived from such provisions by the school system and
to the fact that other funds of municipal employés were
already helped along by these cities or states. These arguments
were so successful, that for more than two decades
afterwards the government’s contributions continued to rise
steadily while the teachers’ contributions in most instances
remained stationary. Furthermore, from 1884 to 1817,
according to Mr. Studensky,[221] no less than six cities and five
states adopted teachers’ pension schemes in which the government
bears the entire expense of the fund. During the same
period sixty-four cities and fourteen states established systems
of joint contributions by the government and the teachers.
These funds, excepting those established more recently in
Connecticut, Massachusetts, New York and Pennsylvania, and
which are organized in accordance with sound actuarial principles
are, says Mr. Studensky:
“Insolvent in so far as they have failed to provide for adequate reserves
187with which to meet accrued liabilities as well as liabilities incurred
through service rendered since the establishment of the system.
It matters not that most of these systems are still able to
make payments, still have unexpended cash on hand, and are and
will for a few years continue to be able to meet their payments.
They are no less insolvent than the systems which are already bankrupt.
Only by shifting their huge deficiencies ahead year by year
do they continue their existence. By doing so they increase of course
these deficiencies because of the continued failure to discount future
liabilities. The longer they operate, therefore, the greater are the
deficiencies and the more insolvent the funds become.”[222]
The main features of these funds may be summarized as
follows:
Retirement age.—The retirement age is not specified
in the case of many funds, the former being dependent
entirely upon the number of years of service. Where provision
is made for the age of pensioning it is generally 60 years.
In some cases also it is set at 60 for men and 55 for women.
The period of service required before one can qualify for a pension,
ranges from 25 to 30 years, except in a few instances where
only 20 years or less, or 35 or more years of service are required.
In many systems the age attained and the number of years of
service are alternate conditions for retirement, i. e., a teacher
may retire upon completing a fixed period of service regardless
of age or, having reached the maximum age, may be pensioned
even though he or she has been in the service a smaller number
of years. In considering service years, credit is usually given—except
in the newer systems—for teaching experience in other
states or localities.
Pension amount.—The amount of the pension is usually set
either at a fixed sum of $500 or less per year, or is determined
by the number of years of service; or as provided in some funds
is entirely dependent upon the average salary received. The
annuity in these cases is based approximately upon one-half of
188the salary of the last few years or upon both salary and length
of service. In the new funds it is generally provided that the
benefit is divided into an annuity and a pension. The first is
based upon the contributions and age of the pensioner while
the pension equals that of the annuity and is given by the
government.
Contributions.—The contributions to the funds in most
cases are derived from three general sources. The contributions
of the teachers themselves; appropriations from the
different school boards; and whatever is derived from accrued
interest, donations, legacies, bequests, and so forth. In most
systems the teachers’ contributions to the funds amount to
from one to three per cent. of their annual salaries. These are
usually graded in accordance with the number of years in the
service, the contribution being highest for those longest in
the service. In the new systems the contributions of each
teacher depend upon the age at which he begins to contribute
and upon the number of years of prior service. The “pension”
is fixed at a certain proportion of the teacher’s salary and
increases with each year of service up to 35 years, when it
ceases to increase.
In case of mental or physical incapacity partial annuities
are generally provided in most funds. These are computed
by taking a percentage or fraction of a percentage of the
yearly salary multiplied by the number of years of service.
A minimum period of service is usually required even for the
granting of partial annuities. This latter period varies from
five years in most city funds to twenty-five years in a few
others. In practically all retirement systems, provision is
made for both compulsory and optional retirement age periods.
The latter is usually determined at the discretion of the Board
of School Directors, and may precede the compulsory retirement
age period by about five years.
Of the 24 systems analyzed in detail by Mr. Studensky, it
was found that while 18 of these exact contributions from
the teachers, only eight provide refunds in case of death. Of
189the latter a few provide for the refund of one-half of the contributions
without interest; in others, especially the newer ones,
the entire accumulation with compound interest is returned. In
case of dismissal or resignation most systems provide for the
return of all contributions, although a number make no such
provision.
In 1817 there were in existence in the United States 84
teachers’ retirement systems; 22 of which were State systems
and 74 local systems. These covered a total of 332,554
teachers. Fifty-seven of the 84 systems have been in existence
only since the last decade. The extent to which these
funds may be expected to take care of the superannuated
teachers may be appreciated from Professor W. F. Willoughby’s
summary in his introduction to Mr. Studensky’s book. To
quote Prof. Willoughby:
“Of the nearly one hundred teachers’ retirement systems now in
operation in the United States, only a few can escape total collapse
unless fundamentally altered. Some of these systems include ten,
fifteen, or even twenty thousand teachers each. Twenty-two of
them are state-wide in their operation. They apply to over three
hundred thousand public school teachers, i. e., to nearly one-half of
the total number of teachers in the United States and they have
liabilities in the neighbourhood of half a billion dollars, for the discharge
of which, in large part, there are no assured assets. Besides
the necessity for putting these systems upon an equitable and
sound financial basis, there is need for the establishment of retirement
allowance systems in those states and localities which as yet
have none. At present seventeen states have neither state nor local
pension systems for their public school teachers, and in twelve of
the remaining states there are only a few local systems. Approximately
one-half of all the public school teachers in this country are
not covered by any pension provision.”[223]
190
The earliest forms of mutual assistance and insurance
benefits organized by the middle and working classes were
through the agency of fraternal organizations. Many of
these had their beginning in the mediaeval trade guilds. The
industrial revolution, with its resultant hazards, spurred and
swelled these organizations tremendously until there have been
developed the numerous fraternal orders and secret societies
now in existence most of which have benefit provisions of one
form or another.
The fraternal organizations, as incorporated associations,
supply to their own members on a co-operative plan, various
forms of insurance—largely against sickness, death and disability.
When confronted with problems of old age relief,
these societies, ordinarily raise only sums sufficient to cover
contingencies as they arise. This usually results in the
younger generations granting aid to the older members with
the expectation that in their old age they, too, will be provided
for in a similar manner. The inevitable effect of this is that
as the burden of supporting the older members becomes heavier,
fewer younger members are attracted into these societies.
Furthermore, many of the younger group, when confronted
with heavy assessments, drop out and leave the older members
to hold on until the final collapse. It is, therefore, not surprising
to discover that the early history of these societies,
as insurance instruments, is strewn with financial wrecks.
191Few of these societies have even today adjusted their rates
on a scientific basis or upon actuarial principles, and many are
still insolvent.
Of the hundreds of fraternal societies in the United States
the number of those having benefits which may be classed as
old age pensions is insignificant. Only three out of 117
fraternal associations in Massachusetts in 1807 had such
benefit provisions. Still more negligible is the number of aged
who are actually in receipt of such benefits.
“A Circular of inquiry addressed to 60 of the leading fraternal
beneficiary corporations organized outside of the State of Massachusetts
brought 36 replies. Of the associations replying, 31 stated
that they pay an old age pension and annuity allowance, or gratuity
in some form. Five have no old age benefits. Some of
the latter, however, pay benefits for total and permanent disability.
The age of 70 is the usual age at which an old age pension is payable.
Twenty-four societies out of 26 answering the inquiry on this
point give the age 70, and two the age 75, as the pensionable age.
In many cases permanent disability is also required as a condition
for the receipt of an old age pension. The amount of the pension is
commonly one-tenth of the face value of the insurance certificate
carried by the member. It is usually provided that the one-tenth
shall be paid annually until the whole amount of the certificate has
been canceled, or for ten years, or until the age of 80. Twenty-five
associations pay this amount of benefit. Two societies pay only one-twentieth
of the amount of the certificate; one pays one-fifth in five
installments; and one pays one-half of the certificate upon its surrender.
The great majority of the societies have thus far paid nothing
on account of old age benefits, as they have been organized but a
short time and payments are not yet due. Fourteen societies report
payments on this account, as follows: $100 for two members;
$200 for one member; $200 for two members; $400 for one member;
$400 for two members; $3,886.40 for 12 members; $7,276.58 for 17
members; $2,642.73 for 24 members; $5,700 for 34 members; $5,125
for 56 members; $10,000 for 200 members; $14,800 for a number of
192members unstated; $48,021.85 for 385 members; and $104,788
for 748 members.”[224]
The Pennsylvania Commission also studied 155 fraternal
organizations listed in the Report of the Insurance Commissioner
of that State. The membership of many of those organizations
ran into the thousands. The report listed 85
fraternal corporations with charters from other States and
58 with charters from Pennsylvania. In the case of the former
only nine were listed definitely as giving old age benefits.
The number of Pennsylvanians receiving such benefits was 31.
A letter of inquiry addressed to all the Pennsylvania organizations
brought thirty-nine replies. None of these paid old
age benefits as such. Thirty-two paid no benefits which could
even be classified as superannuation allowances, although a
number paid disability benefits.
On May 11th, 1821, the Indiana State lodge of the Eagles
adopted the following resolution:—
“Whereas, Modern industry, with its intricate, swiftly moving
machinery, and rush for production, requires the steady nerve, ready
initiative, and exhaustless energy of youth, and places the elderly
workman at a serious disadvantage, even if it does not debar him
from employment; and
“Whereas, Experience has proved that the remuneration received
during his productive years is, in many cases, through no fault of
his own, utterly inadequate to enable the workingman to “lay by”
sufficient to provide for the non-productive years of later life—statistics
showing that in the United States, alone, there are 1,250,000
such old-age dependents on public and private charity; and
“Whereas, Such charity, with its brand of pauperism, inflicts an
unjust stigma upon those unfortunate victims of our industrial
system who have expended the energy of their vigorous years in
production for the benefit of society; and
“Whereas, The pension is not a form of charity, but an honorable
recognition of hitherto not fully rewarded service; and
193“Whereas, Among civilized nations, the United States is the only
prominent one that has not in some form or other recognized the
obligation of the state to the humble toilers whose labours are the
basis of its prosperity; and
“Whereas, The Fraternal Order of Eagles is particularly interested
in this question, not only because of the economic status of a
large portion of its membership, but also because of its fundamental
principle of upholding justice. Therefore, be it
“Resolved by the Indiana State Aerie, That we are in favour of
governmental old age pensions, and that we invite our sister State
Aeries and the subordinate Aeries of the Order to unite with us in
requesting the Grand Aerie of 1821 to take such action as will
awaken public sentiment to the wisdom of State and Federal provision
that shall remove from the minds of the labourers of the land
the haunting fear of want and pauperism in old age.”
Mr. Samuel Gompers, President of the American Federation
of Labour, stated in a letter addressed to the “Committee
on Miners’ Home and Pensions”: “The general purpose—that
the organization ought to take care of its aged and
indigent members, and to make some provision for their welfare
and protection—is a most worthy one. It is in accord
with the general fraternal concept that underlies the whole
organized labour movement. It has much in common with the
more sensitive social conscience that has led to general provisions
for those in want.” He further warns that “Many of the
proposals for social insurance are of a compulsory nature.
Wage-earners now find themselves confronted by this
alternative; either labour organizations must make more comprehensive
and more adequate provision for trade union benefits,
or else they will have forced upon them compulsory social
insurance under the control and direction of government agencies.
Compulsory social insurance will inevitably result in
supervision by the Government of the normal activities of trade
unions and in the delegation to governmental agents of all
194matters that vitally affect the interests, the rights, the welfare
and the freedom of wage-earners.”
It is also the general conviction of trade unionists, that
a pension paid by the union to its old members is of inestimable
value. Trade union experience, with established benefit
features, has proved these to be sources of strength. They
are “holding and binding the membership together in a bond
of human sympathy, winning the admiration and respect of
even those who are opposed to union organization.” As an
organizing factor, it is invaluable. It attracts and prompts
to identify themselves with labour organizations, members who
would perhaps otherwise remain on the outside. The fact
that a member is rewarded for loyalty to the union by being
provided for in his declining years not only promotes greater
promptness in the payment of dues, but reduces the lapses of
dues to a minimum. Furthermore, it causes many to consider
well before contemplating the severing of their connection with
the union for any but very serious reasons.
It would appear from the preceding that among trade unions
at least—where the principle of fraternal brotherhood is most
firmly established—there would be found complete measures and
comprehensive schemes for the protection of their members in
their declining days. This, however, is not the case; and thus
far, the American labour movement has done comparatively
little in the way of providing opportunities for protection
against old age. While it is true that the more radical element
in the labour unions abhor the idea of belonging to an “insurance
company” rather than to a class-conscious labour organization,
the influence of this group has as yet been comparatively
ineffective and the lack of old age provisions cannot
be credited to its opposition.
The 1808 Report of the United States Commissioner of
Labour lists 18 Trade Union organizations as paying benefits
for temporary disability and death. Four of these pay
benefits for temporary disability, permanent disability, and
195death; three pay benefits for temporary disability, permanent
disability, death and superannuation, and two pay benefits for
temporary disability, permanent disability, death and superannuation
and death of members’ wives. Of the 83 unions
that pay death benefits, 18 pay permanent disability benefits.
Only four were paying superannuation benefits. Four
other unions were at that time accumulating a fund for the
payment of superannuation benefits which are now in operation.
The first American Trade Union to institute an old age pension
system was the International Typographical Union. The
history of the pension system of this labour organization is
so interesting and indicative of the whole problem of fraternal
insurance that it is of value to discuss it at length. This
union, which began to take care of its aged workers as early
as 1882, has ever since been in the vanguard of the movement
to extend old age pensions to all persons. As early as 1884
the International Typographical Union opened its Union
Printers’ Home at Colorado Springs, Colorado, in order to
take care of the old and infirm members, “who through their
steadfast loyalty and many sacrifices to the I. T. U. have
made the present organization possible.” After several years
of experience with this Home—generally conceded to be a good
one—the I. T. U. became aware of the fact that many aged
and incapacitated members were unable to avail themselves of
the benefits of the Home because of family ties and long associations
in their respective communities. Once this was realized,
to further insure the members against abject poverty and
public or private charity, an old age pension system was
established at the annual convention of the Union in 1807.
This became operative in March, 1808.
The plan, as originally adopted, provided for the payment
of four dollars per week to members 60 years of age, having
196a continuous active membership in good standing of
years, unable to obtain sustaining employment at the printing
trade, and not earning more than $4.00 per week at the
trade. At the 1810 Convention the law was amended so as to
render eligible to pension, members 70 years of age, having
a continuous active membership in good standing of ten years.
Provision was also made in the law for members totally incapacitated
for work whose applications for admission to the
Home had been disapproved by reason of their affliction; such
members were required to have twenty years’ continuous active
membership in good standing.
In 1811, at its convention in San Francisco, the I. T. U.
finding that the preceding amendment still did not reach a
large number of men whom it was necessary to assist and
also that the experience of the first few years of its pension
fund warranted a further extension of the benefits, increased
the pension allowance to five dollars per week to the following
three classes of members:
First: Members 60 years of age who have been members
in good standing for a period of twenty years, including and
ante-dating the enactment of the pension law, and who find it
impossible to secure sustaining employment at the trade.
Applicants under this provision of the law must have been members
in good standing at the time the pension law became
effective and must have maintained active membership since
that time.
Second: Members who have reached the age of 70 years
and who have been in continuous good standing for a period
of ten years and who find it impossible to secure sustaining
employment at the trade.
Third: Members who are totally incapacitated for work,
who have been continuous active members for twenty years,
and whose applications for admission to the Home have been
disapproved because their afflictions are such as to render them
ineligible for entry to that institution. In January, 1820,
197the pension was further increased to six dollars per week.
The fund for the payment of pensions is provided by a
tax of one-half of one per cent. of the weekly earnings of all
members.
Since March, 1808, when the assessments were first made,
the total receipts of this fund up to May 31, 1820, were
$3,856,161.08, from the tax assessment, $204,833.58 was derived
from interest, and $1,378.50 from returned pensions.
The total receipts were $4,085,467.02.
The expenditures made during the same time were $3,022,448
paid to pensioners; and $86,158.26 for administration
and registration system. The balance of the fund on May 31,
1820, was $886,858.76.
The financial operations of this fund during the first few
years were declared eminently satisfactory. So much so that
when the receipts in the first year exceeded the amount expended
there was a temptation to reduce the amount of assessment.
Gradually, however, it was found that although the
assessments continuously increased, the expenditures on
pensions grew steadily until in 1817 the latter exceeded the
total income by nearly $20,000. At the 1817 Convention
of the I. T. U. it was, therefore, recommended that the provision
whereby a member at the age of 70 of but ten years
standing was entitled to a pension be repealed. This was done
the following year. During the year 1818, however, the income
from assessments exceeded the amount expended on pensions
by more than $200,000, although the number of pensioners
during the same year increased from 1,483 to 1,510.
The secret of this remarkable revival lies in the increased average
earnings of the members of the International Typographical
Union upon which the assessments are based. The annual
wages of the I. T. U. members increased, according to the
Secretary of the Union, from $1,264.88 in 1818 to $1,615.25
in 1818.
From the above conditions it is obvious that the future of
198the Old Age Pension Fund of the I. T. U. is neither stable
nor secure. Should there be a depression in business or a lowering
of wages the existence of the fund is threatened, unless
the accumulated revenue fund is sufficiently large to protect
it. Otherwise, it will necessitate either a reduction in the pensions
or an increased rate of assessment.
Up to May 31, 1820, 3,083 applications for pensions by
the I. T. U. were received. Of this number 82 petitions
were disapproved, 82 were withdrawn and 2,808 were approved.
Death removed 1,388, leaving 1,510 pensioners on May 31,
1820. The high death rate of 45.23 per cent. among these
pensioners is significant. This is doubtless due to the advanced
ages of the pensioners. The average age of all applicants
is 64.24 years. The membership of the unions having members
on pension in 1820 was 57,520. The pensioners’ represented
2.62 per cent. of the membership of these unions which
in return constituted over three-fourths of the total membership
of the I. T. U. During the fiscal year ending May 31,
1820, 156 pensioners were added.
The Order of Railroad Telegraphers has established a pension
fund for life annuities to old and faithful members of the
order who have reached an advanced age in life, as well as to
those totally disabled through physical and mental infirmities.
In order to be eligible to membership, one must be a
member continuously for at least five years, immediately prior
to the filing of application for membership with the pension
fund. Members 60 years of age and over are not eligible to
membership in the pension fund after January 1, 1816.
The fund is maintained from an admission fee of five dollars
from all applicants for membership in the pension fund and
from a semi-annual assessment thereafter “equal to an equal
division of $240 over the period ensuing between the age of
199the applicant at the time of admission to the pension fund and
his 65th birthday after which his or her assessments shall
cease.”
When a member of the pension fund attains the age of 65,
he is paid a monthly salary of $20 during the balance of his
or her natural life.
In order to obtain a total disability pension, eight years’
membership is required. The assessments cease as soon as
placed on retirement roll.
The pension fund is entirely self sustaining and can in no
way create any financial liability to the Order of the Railroad
Telegraphers.
The Secretary and Treasurer of the Order writes: “We
will probably discontinue our pension plan at our next convention,
due to the fact that this proposition has not received
the support of our members as was anticipated. If it is discontinued,
all money paid into the fund will be returned to the
members of this department.”
The Bricklayers’, Masons’ and Plasterers’ International
Union of America has an Old Age and Disability Relief Fund.
This Union provides that when a member has been in continuous
good standing for a period of twenty or more years, and
has passed the age of sixty and who through some bodily
infirmity is unable to secure sustaining employment at any
occupation and has no means of support, he is then entitled
to make application and receive five dollars per week benefit
from the Relief Fund.
A member who meets with some accident while working at
his trade on a building, during working hours, and is incapacitated
from work, and who has ten years of continuous standing
to his credit, is entitled to disability relief, of five dollars
per week.
200The widow of a member, entitled to old age or disability
relief, who is without means of support and who has reached
the age of sixty years at the time of her husband’s death, is
entitled to the five dollar weekly payment until she dies or
remarries.
It is provided in the by-laws, that each member shall pay
into the treasury of the International Union such relief dues
as may from time to time be levied by the International Union
in convention assembled. The present assessment to the fund
is fifty cents a month for each member.
This Union has jurisdiction over the United States and Canada.
The general average membership for the first five years’
existence of the fund was approximately 72,000. About 4.67
per cent. of the membership made application for relief, of which
only about two-thirds were approved. In May, 1820, the
union had on its rolls 1,387 old age beneficiaries; in addition
83 were receiving disability benefits and 248 widows were on
the relief list. Each of these was drawing five dollars per
week as a pension. The Secretary of the union states:
“Our experience shows that the number on the relief roll is
continually growing larger, although the last two years the increase
has been very small, but it will continue to grow larger for
the reason that the percentage of claims rejected are for the
reason that they lack a year or two from being old enough, or a
year or two from having the required number of years continuous
good standing.”
The Brotherhood of Locomotive Firemen and Enginemen
reports “an insurance feature in which every member must
participate if he is able to pass the required medical examination,”
but “has no Old Age Relief Fund.”
The Order of Railway Conductors of America has a relief
fund. All members of this Order are eligible to participate
and receive assistance from this Fund, provided they are totally
201disabled and without means of support for themselves and families.
It is encouraging to note that the labour organizations
which have established pension systems of late, have learned
somewhat from the experience of their predecessors and are
at least attempting to adjust their rates on a more sound
actuarial basis; and in addition they provide many other safeguards
for the stability of their funds which do not exist in
the earlier systems.
The Pension Association of the Brotherhood of Locomotive
Engineers was first authorized in 1812 and was revised and
readopted May 22, 1818. Its constitution provides that
after the passage of this law, no one 60 years of age and over
shall be admitted to membership. On and after June 30, 1816,
no application shall be received for membership to the Pension
Association from those who have reached the age of 50
years. And on and after December 31, 1818, no one can join
who has reached the age of 45 years, while after December
31, 1820, members who have reached the age of 40 years are
barred from membership. It is also provided that only such
members of the B. of L. E. who are earning at least $60
per month are eligible to membership in this Association; also
“no person who is out of employment temporarily caused by
sickness or injury, can become a member of this Association,
during such period.” In addition to these restrictions, “All
applicants for membership in this Association will be required
to pass a physical examination by a competent and reliable
physician, and those having physical or mental defects may
become members of this Association, provided that proper and
legal waivers be furnished by such applicants exempting this
Association from any and all liabilities resulting therefrom.”
Benefits are extended to the following: First: “Any member
of this Association in good standing, who was in active
service at the time of enrollment as a member, but who from
physical or mental cause is totally and permanently disqualified,
202or has been retired on account of old age, shall
from the funds of this Association a monthly pension as hereinafter
provided.
“Any member of this Association who voluntarily retires
from active service will not be entitled to receive a pension on
account of old age until he has reached the age of 65 years.”
Second: “Any member of this Association, in good standing,
who was not in active service at the time of enrollment as
a member of this Association, who from physical, mental, or
other cause, is unable to perform any kind of remunerative
employment, or who has reached the age of 70 years, shall
receive from the funds of this Association a pension as hereinafter
provided; provided further, however, that no member
shall receive a pension for disability caused by his use of
intoxicants, or unlawful acts.”
Third: “All members of this Association, who are 65 years
of age and are in active service, may if they so elect, voluntarily
retire permanently from such service, and thereupon
become eligible to a pension at once. All other members who
have reached the age of 70 years shall be granted a pension.”
The contributions and the pensions of this Association are
graded, and vary in accordance with the age and period of
contribution. The amount of dues paid by each member
follows:
“All active members under the age of 30 years shall pay 50
cents per month.
“All active members from the age of 30 to 35 years shall pay
$1.00 per month.
“All active members from the age of 35 to 40 years shall pay
$1.50 per month.
“All active members from the age of 40 to 45 years shall pay
$2.00 per month.
“All active members from the age of 45 to 50 years shall pay
$2.50 per month.
“All active members from the age of 50 to 55 years shall pay
$3.00 per month.
203“All active members from the age of 55 to 60 years shall pay
$3.50 per month.
“All active members from the age of 60 to 65 years shall pay
$4.00 per month.
“All active members from the age of 65 years shall pay $4.50
per month.”
The pensions allowed are based upon the following scales:
“Any member of this Association who has been declared a pensioner
by the board of Governors, who shall have paid dues for
60 months, or less, shall receive a pension from this Association
for the remainder of his life, of $25.00 per month.
“Those paying the dues from 61 months to 120 months, $30.00
per month.
“Those paying the dues for 121 months to 160 months, $30.00
per month.
“Those paying the dues for 161 months to 180 months, $35.00
per month.
“Those paying the dues for 181 months to 240 months, $40.00
per month.
“Those paying the dues for 241 months to 300 months, $45.00
per month.
“Those paying the dues for 301 months to 360 months, $50.00
per month.
“Those paying the dues for 361 months to 420 months, $55.00
per month.
“Those paying the dues for 421 months to 480 months, $60.00
per month.
“Those paying the dues for over 480 months, $65.00 per month.”
The Brotherhood of Locomotive Engineers also has in addition
an Indigent Fund and an Insurance Relief Fund.
The Pressman’s Union adopted a pension plan, by first
creating a sinking fund from the accumulations of a 25 cent
assessment per month for all members for five years, before
the payment of pensions became operative. This, it is believed,
will create a sufficient fund which when placed on interest will
204insure stability and prevent the gradual increase of the per
capita tax as was the case with other established funds.
Since 1813, District Number 21, United Mine Workers of
America, has had the following pension system:
Each member pays 40 cents assessment per month, which may
be raised or lowered when necessary.
All members, 60 years of age, when they have discontinued
work in the mines, or those physically disabled from performing
further labour in and around the mines, having no other means
of support, and who have been in good standing for five years
preceding January 1st, 1813, receive $3.00 per week. Those
joining the Union after January 1st, 1813, are not eligible to
benefits unless they have been members in good standing for
five years prior to making application for pension.
At the 1816 International Convention of the United Mine
Workers of America, a Committee was appointed “to investigate
and report on the advisability and possible cost, to the International
Union, of erecting and maintaining a suitable home
wherein to care for the aged, infirm and decrepit members.”
After a careful investigation of the Soldiers’ Home, and
Homes for the Aged, maintained by the different unions, and
fraternal organizations, in the United States and England,
the Committee reached the conclusion that “taking the estimate
of other homes, it would cost about $40.00 per month for each
resident for clothing, food, medical attendance and medical
supplies.”
The Committee further reported that “The question of pension,
with or without a home, was early called to our attention,
and as the different organizations with whom we came
in contact either had pension systems in active operation or
were preparing to adopt pension systems, we deemed it advisable
to gather all the data possible on the subject.” In comparing
the safeguards adopted by other organizations, and in
its “endeavours” to select such as are actually necessary, to
205make the plan a success, the Committee at the 1817 International
Convention of the U. M. W. A. recommended the
following plans for creating and maintaining a pension system.
“(1) An old age disability pension fund is hereby enacted
by an assessment of 40 cents per month per member, which
shall automatically be raised or lowered as necessary under the
direction of the board of trustees hereinafter provided for,
but in no case shall the assessment exceed 50 cents per month
per member.
“(2) Said assessment shall be in full force and operation
on and after April 1, 1818.
“(3) A sinking fund shall be created by the accumulation
of said assessment for a period of three years from and after
April 1, 1818.
“(4) That on and after April 1, 1821, all members in good
standing who have reached the age of sixty-five years and who
have been continuous members in good standing for a period
of ten years immediately preceding their application for pension
and have paid their regular monthly assessment to the
pension fund for at least three years, whose earning capacities
have been reduced to less than twenty-five dollars per
month, and who have no visible means of support other than
their labour, shall be eligible to receive a pension of twenty
dollars per month payable monthly.
“(5) That on and after April 1, 1821, any member who
has been a continuous member in good standing for ten years
immediately preceding his application for pension and who has
paid his regular monthly assessment to the pension fund for
at least three years and who is totally incapacitated for
work by reason of accident or sickness of a permanent character,
who has no visible means of support other than his
labour and who has been denied aid from compensation laws
or has tried and failed to recover reasonable damages for injuries
sustained, shall, upon satisfactory proof, be allowed
a pension of twenty dollars per month, payable monthly; the
206trustees to have the right to appoint a physician or physicians
to make an examination if they deem it necessary.”
From a canvass of 608 miners’ locals with a total membership
of 120,568 the Committee has learned that there were
4,188 members from 60 to 65 years old; 1,828 from 65 to 70
years of age, and 156, from 70 and over. In addition there
were also 1,487 incapacitated members under 60 years of age.
The Committee admitted that this was a very large per
cent., as compared with the membership of other organizations,
but recommended the adoption of 65 years of age as the minimum
age for the payment of pensions.
It accepted the experience of the International Typographical
Union as a safe guide for its own contemplated plan.
It stated that in the latter Union there is a fraction more
than 22 pensioners to each 1,000 members, which they assumed
would hold true of their own membership. Since that time the
miners have given up the plan of establishing their own pension
fund but have instructed their committee to work for
the passage of old age pension laws.
During the Convention of the United Brotherhood of Carpenters’
and Joiners of America in September, 1820, the officers
of the Union were instructed to formulate plans for an old age
pension system for the members of the organization.
The experience of even the firmly established and best intentioned
fraternal pension systems in this country has not
proved these to be very satisfactory instruments. It is,
doubtless, this recognition that has prompted the International
Typographical Union to adopt the following resolution
at its 1817 Convention:
“Whereas, The United States of America is the only great
nation in the world (excepting Russia) that does not provide old
age pensions for its worn out and worthy workers; and
“Whereas, The consequent necessity of American workers to provide
their own benefits is a gross injustice, and frequently ends in
failure through no fault of the workers; and
207“Whereas, The Government of the United States of America
has demanded that its citizens protect the honour of the nation with
their lives in a great war, while this Government has not in the
past been responsive to the demands of its workers to protect
their honour; therefore, be it
“Resolved, That the International Typographical Union, in
convention assembled, endorse and urge the passage of the old age
pension bill introduced in Congress by George I. R. Sherwood,
for the benefit of all American workers.”
And in May, 1820, the Pennsylvania State Federation of
Labour also adopted by a unanimous vote the following
resolution:
“Whereas,—The United States is now the only industrially
developed country that has as yet made no provision for the aged
and superannuated workers, and
“Whereas,—The recent Report of the Pennsylvania Commission
on Old Age Pensions shows conclusively that the problem
of old age is largely due to the industrial development of our
state as a result of which aged workers are relegated to the
industrial scrap-heap as useless and of no value as soon as their
pace begins to slacken, and
“Whereas,—It is now obvious to all that with prices soaring
skyward from day to day, and with wages never catching up with
the advancing prices, it is absolutely impossible for the wage-worker
to provide for old age from his own earnings, and
“Whereas,—The only present alternative facing the aged worker
is either that of going to the poorhouse or accepting charity, as
even when the worker attempts to save, by denying himself and
his family the most essential comforts, he often fails at the end
because of sickness or unemployment, which is not only an evil
and unjust, but ultimately works to the detriment of industrial
efficiency, as well as the welfare of the State, and
“Whereas,—It must be recognized that the worker who has
helped to create the wealth of this country and who has spent the
greatest part of his life in productive labour, has by his work,
made sufficient contributions to the progress of the state and nation
208to entitle him to a living when industry or exhausted health
longer permits him to work for a living, and
“Whereas,—The Pennsylvania Old Age Pension Commission
plans to submit a bill to the 1821 State Legislature providing for
a state system of old age pensions, therefore
“Be It Resolved,—That the Pennsylvania Federation of Labour
in convention assembled in Altoona, goes on record as urging the
above Commission to submit such a bill to the Legislature, and
the Federation further urges every State Senator and Assemblyman
to do his utmost in helping to promote this sadly needed and
humane Legislation, and be it further
“Resolved,—That the secretary of the Federation be instructed
to include in his questionnaire to candidates for the State Legislature,
a question regarding the candidate’s attitude to proposed
legislation on the question of Old Age Pensions, and no candidate
shall be endorsed by the State Federation who has declared
himself against such Legislation.”
That attempts made by the working classes to provide
against old age may frequently end in failure, is well borne
out from the preceding analyses and is generally recognized.
Labour organizations and labour leaders have therefore been
most active in agitating for governmental pension systems in
old age. Knowing the difficulties confronting them in establishing
their own provisions, labour unions have repeatedly
declared that “The responsibility of caring for the veterans
of industry who in times of peace have been the mainspring
in the work of material progress, and in times of war have
always been ready to sacrifice their all, either in the field
of active operations or in bearing the burdens of taxation and
support, should as a matter of right and justice rest upon the
Government.”
The inadequacy of the present means of protection in old
age is thus evident from the preceding three chapters. Under
the present conditions of costs of living and wages, thrift and
individual savings sufficient for old age cannot be seriously
considered possible for many wage-earners. Neither can the
209industrial concerns be depended upon to take care of their
aged workers, since they have no assured permanency and
take care of only a fraction of the workers they employ.
While the recent Federal Retirement plan will take care of
many a needy employé, there still remain thousands of other
Federal employés as well as employés of states and municipalities
who need to be protected. The fraternal and trade
union old age benefit funds are generally insecure and, at best,
the number that they can protect is inconsiderable.
The insufficiency of the present methods of aged relief in
the United States is succinctly summarized by the Pennsylvania
Commission regarding such provisions in that state.
The Commission states that:
“Of all the multifarious forms of industrial, municipal and fraternal
pensions in the State the number of Pennsylvania wage-earners
actually on pension lists in 1818 hardly reached ten thousand.
In the seventeen leading industries listed the number of
former Pennsylvania employés actually receiving old age pensions
was 2,152. The number of wage-workers receiving pensions
from concerns having no regular pension system would hardly
exceed an additional five hundred. Of all the railroad workers
in the State only about four thousand aged employés are receiving
old age support. However, even if these systems were
operated more extensively, it is clear that they are largely dependent
upon the arbitrariness of the employer, which makes the
receipt of a pension very uncertain for many employés. The
period of service required is often too long. These schemes, it
was apparent, discriminate unfairly against those who cease to
be employés. In a few cases in the contributory schemes, employés
either do not have their contributions returned or have them
returned without interest. Generally industrial pensions are considered
merely deferred wages. These industrial systems specify
that a pension may be terminated at any time; that the establishment
of such a system is not to be construed as conferring a contractual
right, and that the company reserves the right to discharge
an employé or terminate the system at any time.
210“Of the nearly fifty thousand public school teachers in Pennsylvania,
only a little more than 600 are receiving pensions from the
various pension funds. The number of policemen, firemen, and
other municipal and State employés in the State receiving old age
pensions did not exceed 1,700. The inadequacy of protection
against old age provided by trade unions, or fraternal organizations
has already been discussed. It was seen that most of these
are not established upon sound actuarial principles. Many have
become insolvent and many more are liable to dissolution at any
time. As a rule, all these pension funds are exempt from the
strict supervision required of private insurance companies. The
total number of pensioners in the State (not including pensioners
of the United States) constitutes three per cent. of the total
population over 65 years of age in the State. In other words,
only three out of every hundred or thirty out of every thousand
persons, 65 years of age and over, were protected by old age
benefits in Pennsylvania in 1818. This percentage is computed
on the total population 65 years of age and over as given by the
1810 Census. It is obvious that it would be still lower if the
increase in the aged population during the past eight years was
taken into consideration.”[225]
PART FOUR OLD AGE PENSIONS: WHAT THEY ARE AND THEIR OUTLOOK FOR THE UNITED STATES — CHAPTER XI THE PURPOSE AND NATURE OF PENSIONS — I. VOLUNTARY INSURANCE — II. COMPULSORY-CONTRIBUTORY INSURANCE — III. STRAIGHT OR NON-CONTRIBUTORY PENSIONS — IV. THE CASE FOR AND AGAINST UNIVERSAL PENSIONS — CHAPTER XII THE PENSION MOVEMENT IN THE UNITED STATES
211
213
A pension may be defined as a regular allowance or payment
made in consideration of past services. Pensions were
granted first by kings and other royalties to persons who distinguished
themselves in art, literature, and science, as well
as to feudal retainers for military or political services. It
was also customary to grant pensions to prominent jurists,
university professors, and well-known clergymen, who had rendered
distinguished public service. The grant of a royal pension
to an individual was usually taken as a token of gratitude
for valuable contributions made to the credit or benefit of the
crown, the country, or the public. In more democratic nations
the government still pensions soldiers and war veterans in recognition
of their devoted service in the defence and protection
of their country.
The more recent demands for the establishment of old age
pensions, as a social policy, applicable to all citizens, is merely
the natural extension of this principle to the veterans of industry,
to men and women who by brain and brawn have made
vital and essential contributions to the social welfare. To
extend this protection in old age to the working classes is merely
to recognize the changes wrought in our industrial system
which make the welfare, comfort and happiness of all the
people depend largely upon the labour of those who work for
wages.
The smug business man who takes his train in New York
after theatre hours at night, goes to sleep in his pullman-car
and upon awakening finds himself in Pittsburgh or Boston
214ready to transact his business there, doubtless never thinks of
the thousands of manual workers who toiled to make these
achievements possible. Neither does the self-sufficient citizen
think of these workers when he steadily speeds along at forty
miles per hour on a well-paved highway in his comfortable
limousine, or at any other time when he accepts all the modern
comforts and conveniences as a matter of course due to
him. Even those, who, like Carlyle, still hark back and sing
praises of the eighteenth century, do not fail to take advantage
of the comforts of the nineteenth and twentieth centuries,
such as the railways, telephone, telegraph, and even the talking
machine. Despite their condemnations of modern conveniences,
they never go back to the stage-coach when they
go from New York to Pittsburgh or any other city. Whatever
the evils and faults of the modern industrial order—and
its evils are legion—it cannot be denied that on the whole it
has worked to the ultimate good of most concerned. Only the
old and superannuated wage-earners derive little benefit from
industrial development. The immediate effect upon them is
their replacement by machinery and their inability to find
other employment. For it is known to all that aged persons
are not wanted in modern industry. With the introduction
of newer processes of production, the experience of the old
workers counts for little, and they are generally eliminated
from industry and are thus deprived of the only means by
which they can secure a livelihood. To grant pensions to such
workers, during the days when modern industrial development
permits them no longer to provide for themselves, would
be merely a recognition of their services and a compensation
for their losses, even as we compensate property owners for
disturbance to property when it is taken from them for the
general good.
In the preceding chapters the inadequacy of the existing
provisions against old age have been recited, together with
the difficulties which the old face in attempting to obtain
215security, under the conditions of modern life. It is obvious
that the lack of old-age provisions demoralizes the individual
and is harmful to society as a whole. Society’s loss, as a result
of this insecurity, is inestimable. Furthermore, from whatever
angle it may be examined, it is evident that the problem
of economic support of the aged is with us, and whether met
in one form or another, society ultimately bears the burden.
An old-age insurance or pension system would unquestionably
raise the general standard of living, as it would eliminate to
a great extent the dread and fear of old age which now affects
adversely the productivity and efficiency of a great many individuals.
That the granting of alms, either private or public,
is not only insufficient and unsatisfactory, but exercises
a degrading effect upon the recipients and is repugnant to the
self-respecting person, and can therefore not at all be considered
a constructive policy, seems evident from the preceding
discussions. As aptly expressed by a Committee of the
National Association of Manufacturers in a special report
upon this subject:
“While the social activities of the state are marked by humane
legislation in many forms, for the betterment of the individual,
its system of poor relief is antiquated. Poor relief makes no distinction
between the worthy and the unworthy; the social stigma,
the depravation of the citizenship and often the publication in
the town report of the name of the recipient and the amount
doled out to him, make the system onerous and the opprobrious
epithet of ‘pauper’ is the price the citizen pays for help.”
That there is a problem of old age which is largely the
creation of modern machine industry, is now recognized by all.
Practically all civilized governments now consider this an
important national problem which must be dealt with without
delay. Its solution is generally sought in a broad constructive
social policy rather than in the haphazard charitable
and individual methods of relief. There are few industrially
216developed nations at present that have not yet adopted
a definite course of social action in remedying the problems
faced in old age. Of all English-speaking peoples, the United
States is most backward in this respect, despite its high industrial
development.
In dealing with this problem European governments have
generally followed one or two of the following methods of
caring for their aged. A number of countries also adopted
plans which involve a combination of features of each scheme.
The methods generally followed may be classified under the
following headings: (1) A system of voluntary insurance.
(2) Compulsory-contributory insurance. (3) Gratuitous or
straight pensions by the Government. While the writer
has formed decided opinions upon the merits of each of these
schemes, it is the intention to present here an unbiased analysis
of the arguments in favour and against each of these systems.
The adoption of any one of them depends a great deal upon
the social and economic conditions of the particular State,
or Country, and an impartial discussion of each system is
essential.
Voluntary insurance against old age may be classified into
several types. (A) Private voluntary insurance. (B) Voluntary
insurance under Public Administration. (C) Voluntary
subsidized Insurance.
(A) Private Voluntary Insurance.—Under this head may
be included: (1) The old age mutual insurance as provided
by trade unions and fraternal organizations, (2) insurance
against old age by industrial corporations and (3) insurance
with private companies. All of these forms are business propositions
pure and simple. They involve no State action other
than supervision. The extent of old age insurance by means
of the above agencies, is very limited.
(B) Voluntary Insurance Under Public Administration.—With
217this form of insurance there is no state subsidy, but the
government sells annuities and insurance at cheap rates.
In addition to governmental guarantees, the State in most
instances bears the expense of administration. This is the
underlying principle in the State Savings Bank System in
force in Massachusetts and Canada and to a minor extent
in respect to insurance in Wisconsin. The aims of this insurance
is to facilitate savings against old age and to make it
attractive and accessible to wage-earners. The amount of insurance
is limited and opportunities are offered employers of
labour to co-operate with their employés either by making
contributions towards the payment of the premium or by collecting
it. The advantage of this form of state savings over
private insurance lies in the cheapening of the premiums by
the elimination of profit and the cost of administration.
(C) Voluntary Subsidized Insurance.—The object here is
to put a premium on savings for old age. The State, in this
case, subsidizes individual thrift by means of a State contribution.
These systems were practised for some time in France,
Belgium, Italy, and Spain and still exist in some of these
countries. They are devised with the special purpose of serving
the wage-workers. The amounts of the subsidies vary in
each country. The latter are not given to the insured but
deposited to his or her account and go to swell the amount
of the pension purchased.
The three preceding forms of voluntary insurance are the
evolutionary outgrowth of one another. The chief reason
urged in favour of voluntary insurance is that it encourages
thrift and maintains the self-respect of its beneficiaries. It
is pointed out however by all experts that in practice after
many decades of effort it has failed to accomplish its purpose.
Even generous subsidies do not seem to attract more than a
small part of the wage-earners, and in most countries these
systems have been partly or entirely superseded by other
methods. Reference has already been made to the Massachusetts
218experiment where after twelve years existence of the savings
system only about three hundred persons took advantage
of this form of insurance. Even subsidized insurance, according
to the experiences of the different countries, has at no
time or in any land accomplished its purpose. The working
people obviously either cannot or do not avail themselves of
such insurance. Neither is this fact surprising in view of our
previous analysis of the actual conditions of wage-workers. Dr.
Rubinow, after an exhaustive discussion of the voluntary scheme
in the several European countries concludes:
“1. That even a heavily subsidized system of voluntary old
age insurance attracts only a small proportion of the working
class, presumably of the better paid strata.
“2. That even of those who begin accounts, a large and growing
proportion fails to continue to make the necessary contributions
with any regularity.
“3. That usually only the minimum is contributed which is necessary
to acquire the subsidies.
“4. That the workingmen are forced to reduce their old age pensions
in order to safeguard the interest of their families, and
“5. That the pensions actually acquired are pitifully small.”[226]
The contributory form of insurance came about as a logical
result of the failure of the voluntary systems. The great
mass of wage-workers being either unwilling or unable to insure
themselves against old age, European governments sought to
overcome this by making it obligatory for certain classes of
wage-workers—whose yearly income did not exceed a certain
amount—to insure themselves against old age. The government
continued making it attractive by subsidizing the
insurance. Germany was the first country in Europe to
establish compulsory insurance for working people. A system
219patterned after the German one was adopted by France in
1810. Systems embodying the compulsory principles were
also established in Austro-Hungary, Chile, France, Greece,
Iceland, Italy, Luxemburg, Netherlands, Portugal, Roumania,
Russia, Spain, Sweden, and Switzerland.
Under the compulsory form of insurance all wage-workers
earning below a certain income are compelled to insure. Salaried
workers above a set amount are not obligated to insure
but may, in common with other classes, take out voluntary
insurance. Participation in the plan begins at an early age.
Contributions are generally made both by the employer and
employé in equal parts. The state’s contribution consists of
bearing the expenses of administration. In addition, the
latter also makes a direct contribution to the pension after it
has matured. In Germany the contributions of the workers are
graded in accordance with their income, while in France it is
uniform for all adult males, females and minors. The
employés’ contributions are collected by the employer who is
allowed to discount them from the wages of his workers. The
age when one becomes entitled to a pension is set at 60 years
of age in France, and 70 years, until 1817, in Germany. Before
a person, however, can receive a pension he must have
made a minimum number of contributions; this in Germany is
1,200 weeks, and in France thirty annual contributions. To
protect also those who cannot make the required number of
contributions, provisions are made in both countries reducing
the required period of contributions by 40 weeks for each
year of age over 40 in Germany and 30 in France, when the
law went into effect. The amount of the pension allowed
under these plans is very small, rarely exceeding $60 a year
previous to the war—an allowance which obviously could not
go very far. No country which has introduced compulsory
insurance has at any time attempted to raise more than fifty
per cent. of the necessary funds from the insured persons.
In Germany the contributions from the insured persons
220amounted to about 40 per cent. of the total disbursements,
while in other countries it amounts to about 30 per cent. of
the funds disbursed.
The advantages of the system of compulsory-contributory
insurance are as follows: (1) Its possibility of universality.
By means of compulsion, insurance not only can be extended
to all classes that need most the protection against old age, but
can also be made most effective.
(2) Compulsory insurance removes any suggestion of
charity. Under this system the worker gets his pension
a matter of right even when he is not poor. “It is not
a dead-level system. It preserves a normal relation between
the standards of life before and after the age of pension
and also preserves a just relationship between services
rendered and the rewards granted, for it is usually based upon
the length of contributions, which is the length of activity.”[227]
(3) It encourages thrift even though not of a voluntary
nature. (4) The need of old age pensions is largely a result
of the industrial problem and ought to be borne by industry.
“It is economically just, in so far as it exacts a contribution
from the industry, for superannuation is not less a factor
of modern industrial life than is the rate of accidents or of
sickness. If it be just that each industry should contribute
to the cost of accident compensation in proportion to the
number of accidents occurring, rather than that the entire
cost be forced back upon the national treasury, it would seem
to be equally just that an industry which uses up men by
45 or 55 years may be made to contribute to the cost of
old-age support in a greater degree than another industry
or occupation in which men can preserve their productive life
until 65. Looking upon it in another way, the justice of the
claim may be admitted, that a contribution on the part of the
industry to old-age insurance is but a deferred wage ... if,
under modern industrial conditions, it could be expected that
221the wage-workers themselves would be able to raise the standard
of wages to the necessary level so as to include the cost
of old-age support, and that they would use this additional
increment for that purpose, no compulsory system would be
necessary. But the compulsory system is necessary just because
these two conditions are found to be impossible.”[228]
(5) It does not burden taxation directly. (6) Compulsory
insurance is also urged because of the fact that more countries
have adopted this plan than any other, and because it has
proved successful in several countries where it has been in effect
for some years.
The objections to the compulsory principle of insurance
are: (1) It cannot be made universal, as it omits many who
may need such protection no less than wage-earners. It is
evident that it can only be made to apply to persons who are
in regular employment. It is next to impossible to collect
contributions from persons who are irregularly employed, from
agricultural labourers, from those who are their own employers,
from women who work at home not for wages, from small
merchants, and so forth. (2) Even through compulsion it is
difficult to reach the poorest classes of workers who are most
in need of old-age support. These people simply cannot save
enough to contribute to pension funds. Thrift among workers
who do not receive a living wage is a delusion, and even if
possible, is uneconomic and unsocial. (3) Compulsory insurance,
it is contended, lessens the quality of self-help and
reliance in the individual. Said the Chairman of the Massachusetts
Commission: “If this is the country of wealth it
is also the country of individualistic ideals and achievements.
It was founded to secure individual liberty of thought and
action with opportunities for working out one’s own salvation.
This is its peculiar destiny and its special mission, and
its greatest contribution to humanity will be in terms of character
rather than wealth. Not for any reason of sentiment,
222but because our national progress under the individualistic
ideal has been such as to demonstrate its wisdom and soundness,
do I believe we should take no steps calculated to take
us away from this path of development.”[229]
(4) Where the compulsory system is established the sums
contributed by the insured are practically insignificant. Not
only does the state make a direct subsidy to the insured, but
it also bears the expenses, which because of the inherent complexities
of conducting the administrative machinery and the
recording of facts for a long period of years with reference
to contributions, is enormously expensive. It has, therefore,
also been advanced that there is practically no difference between
the state paying pensions outright, and collecting the contributions
by the compulsory principle. (5) Compulsory insurance,
it is argued by some, is class legislation, as it places the
wage-earning classes under a special régime. It necessitates
the creation of a vast bureaucratic system. “It would
be nothing but taxation, and being exacted from unwilling
subjects, would carry with it none of the good influences of
voluntary thrift.”[230] (6) Old Age is not a problem of industry
alone, for people grow old despite all human efforts. (7) The
amount of the pension under the compulsory-contributory
system is small and the age set is too high. The pensions
as paid in European countries are, as is commonly expressed,
“too little to exist on and too much to die on.” (8) Compulsory
contributions, furthermore, are inelastic and cannot
be adjusted to the particular needs of the various industries
and localities. (8) The proponents of American individualism
also declare that it is un-American, distasteful and
contrary to the American spirit. The compulsory principle,
it is claimed, is intolerable and would not be accepted by the
American citizens. Mr. Arthur M. Huddell, a dissenting
223member of the Massachusetts Commission states the case as
follows:
“To my mind, compulsory insurance is un-American, and cannot
be considered in any way as a solution of this question. The wages
of the workman will not permit any compulsory assessments for
insurance. There is a vast difference between this and compulsory
sanitary laws, compulsory education and compulsory quarantine
laws. A poor man can comply with any of the above laws without
an expenditure of money or in any way reducing his wages,
which he could not do with a compulsory insurance law, as that
would be equivalent to a reduction in wages. There is not sufficient
margin between the living expenses and the wages of the
workman to permit that reduction in his wages.”[231]
(10) The compulsory principle is also believed to be unconstitutional,
as it obligates certain groups to set aside a certain
percentage of their earnings to provide for old age.
Just as the compulsory insurance principle was largely an
outgrowth of the failure of voluntary insurance the establishment
of straight pension systems may also be said to have
come about principally because of the complexities involved in
and the limited effectiveness of the compulsory insurance principle.
While straight or gratuitous pensions are comprehensive
and immediately effective, compulsory insurance forms require a
long term of years before they can become operative and capable
of coping with the immediate problems. State pensions
were first inaugurated in order to secure an immediate means
of relieving the pressing problem of the aged poor. This
form of outdoor relief is a marked improvement over the indoor
relief previously followed which involves the destruction
of the amour propre and independence of the recipients.
A straight pension is an economic remedy for an economic ill
224readily adapted to the needs created by the modern industrial
development. Under this system neither the employer nor the
employé make direct contributions. The funds are paid out
from the general treasury. Systems of gratuitous pensions
have been adopted in Alaska, Australia, Denmark, France,
Great Britain, New South Wales, New Zealand, and Uruguay.
State pensions are usually granted to all persons who have
complied with the requirements of the particular law. The
specifications usually provide that a person before receiving
a pension must have attained a certain age; that he must have
been a citizen with a long period of residence; that he must not
have an income from any source above the specified amount.
Sometimes it is also required that he must have fulfilled a certain
period of service. In addition to these, most countries
require also certain moral and character qualifications. In
many countries pensions are denied on account of family desertion,
neglect of minor children, drunkenness, or prison sentence.
It is generally specified that pensions are given to the
“deserving poor.” The first of these gratuitous systems was
established in Denmark in 1881. Due to the influence of Lloyd
George, a straight old-age pension system was adopted by
Great Britain in 1808. In 1815, the Territory of Alaska
and the State of Arizona had enacted similar systems, the
latter of which was declared unconstitutional by the Supreme
Court of that State before it became operative. Although
the principles involved are the same in all countries, the requirements
and qualifications are widely varied in the several
countries operating these systems of pensioning the aged.
The non-contributory form of old-age relief is one of the
most popular and most widely discussed plans. The particular
points in favour of this scheme as over the voluntary
and compulsory systems may be outlined as follows:
(1) Its simplicity. Straight pensions are given only under
definite and well defined conditions; the amounts are fixed and
little administrative expense is required.
225(2) Straight state pensions are just, as it is the duty of
the state to take care of its aged poor. This obligation of
the state, was recognized by the latter long ago in its distribution
of poor relief. Pensions in old age, while following the
same principle, remove the stigma and degradation of the present
system of poor relief. It is pointed out that the state
at present attempts to relieve most classes of suffering, except
old age. Pensions, are, therefore, simply an extension of the
duties of the state aimed to remove the suffering and terror
associated with old age. “It is compulsory now upon our
citizens to make a living, but if they wish to become criminals,
the state will support them. But the man who wants
to remain a law-abiding citizen and try to support his family
is compelled to provide for old age, when the facts are that
he is unable at the present time to secure many of the comforts
of life. Every law-abiding citizen has rendered to his
country some service, which entitles him to look forward to
a pension given in return; and as at present the premium
placed upon crime and poverty is un-American, something
should be done to provide for the law-abiding, self-supporting
citizen.”[232]
(3) Governmental pensions while nominally non-contributory,
have in reality been contributed by all in the taxes paid.
Mr. Lloyd George states this as follows:
“As long as you have taxes upon commodities which are consumed
practically by every family in the country, there is no such
thing as a non-contributory scheme.... Again, the worker who
has contributed by his strength and his skill to the increase of
the national wealth, has made his contributions to the fund from
which his pension is to come when he is no longer able to work.”[233]
It is thus evident that those who have given a considerable
part of their lives in useful service have already made those
226contributions to the state and are entitled to freedom
dread and anxiety over their needs during their declining years,
as well as from the disgraceful brand of pauperism.
(4) Non-contributory pensions by the state would stimulate
people to greater loyalty, ambition, independence and hopefulness;
and would give the individual a stake in his country,
thus increasing his patriotism and his interest in government
and national affairs. James T. Buckley, a dissenting member
of the Massachusetts Commission, argues that:
“Assurance through a pension, contributory or otherwise, that
one’s last days would be spent in peace and comfort, with no fear
of poverty and want, would have a strengthening influence upon
the individual, enabling him to go to his daily task with a calm
and contented mind, and would tend to increase ‘the sense of personal
responsibility and independence.’”[234]
“A pension in old age,” declared also John Metcalfe, “would
be no small gain and certainly a most conservative measure to give
the expression ‘my country’ some little material meaning, even if
that tangible something was but the security that after 65 years
of individual struggling with the tasks of life, the state provided
a small pension for every man and woman in the land. It
would be no small gain if this measure led the men and women
to look out on life with more hope and on national and commercial
affairs as something which affected them personally, and
in which they should take a deep interest.”[235]
(5) A pension to be secured in old age would encourage
thrift and savings. As the pension alone is rarely sufficient
to cover all the needs, the wage-earners would make an effort
to lay aside whatever possible, so that their savings together
with the annuity would assure them of a minimum of comfort.
The fact that they can never save sufficiently to provide for
old age is, perhaps, the greatest deterrent factor which prevents
people who could afford to do so from saving the little
227they can. When there is assurance, however, that one’s last
days would be spent in peace and some comfort with no fear
of want and the poorhouse, it would have an encouraging influence
tending to cause most persons to make some provision
for the future. Says Mr. Metcalfe:
“The principle which underlies the habit of saving, in my
opinion, is exactly the same as that which induces a hen to lay
its egg where there is at least one egg already—what I will call
the principle of the nest egg—and that just as you induce a hen
to lay its egg where you have placed one egg you would induce the
artisan and labourer to begin to put something by from his earnings
by providing him with a certain small sum in the shape of a
pension for old age.”[236]
Indeed, the savings accumulations of the countries which have
adopted this system of pensions such as Denmark, Great
Britain, New Zealand, etc., seem to bear out this contention.
(6) Pensions in old age would keep families intact. They
would increase filial affection and respect for parents. What
we respect and venerate in the aged is not old age as such,
but the superiority in judgment, experience and independence
of means. And one of the principle reasons why the aged
in modern society, especially as found among the lower paid
wage-earning classes, are less esteemed, is, doubtless, because
the aged wage-earner instead of having steadily improved his
position is compelled to steadily give way to younger men.
Unable to earn a living wage, in his regular employment, he
is compelled to do the work that needs little mental and physical
labour. This generally means accepting employment of
a menial nature. In this work he naturally loses his own self-respect,
and once that is lost, the loss of respect for him on
the part of his fellowmen and even of his own relations follows
soon. A pension in old age would not only protect his independence
and respect, but also would very often make him a
228welcome addition to the family of the son or daughter, where
without it he would be a burden.
(7) A non-contributory pension system is unquestionably
the most feasible plan to be suggested at the present time for
the United States. The Massachusetts experiment has shown
how futile and inadequate voluntary insurance systems are in
this country. As most of our social legislation was first originated
in the States and only later on followed by national
legislation, a system of compulsory insurance by the individual
States would, under our conditions of free labour migration
and mobility, necessitate an expenditure upon the accounting
and recording of statistics, an essential to the compulsory-contributory
principles, which would make it almost prohibitive
from consideration.
ARGUMENTS AGAINST NON-CONTRIBUTORY PENSIONS
The Massachusetts Commission on Old Age Pensions, Annuities
and Insurance, brought the chief arguments against a
non-contributory pension plan for the United States in its
report of 1810. The Commission concluded that: “The
adoption of any scheme of non-contributory pensions in Massachusetts,
or in any other American state, seems inadvisable
and impracticable.” The reasons given against this plan by
the Commission and other critics are as follows:
(1) The heavy expense involved in such a plan. The Commission
estimated that for Massachusetts to pay a pension of
$200 per year or four dollars per week for half the population
70 years of age and over, would cost that State not less than
$10,000,000 per year. The cost would, of course, be greatly
increased if the pensionable age is set at 65.
While this is true it must be remembered that a great deal
of this cost is already being paid by the citizens at present
through the different charitable and philanthropic agencies, as
well as public poor relief. To a considerable extent, therefore,
229the cost of the pension would be met by savings on the present
expenditures of public and private philanthropy.
Indeed, according to Prof. Woodbury,[237] the proportion of
paupers over 70 years of age in England fell from 23 per cent.
of the population of this age in 1805 to 18.6 per cent. in
1810, one year after pensions began to be paid. After the
1811 amendment, which entitled persons receiving poor relief
to pensions, the number of those 70 years of age and over who
were given outdoor relief in England decreased from 138,323
persons in January, 1810, to only 8,563 in January, 1813, a
decrease of 84.6 per cent. The number of indoor paupers
also showed a decrease of 18.8 per cent. from 1806 to 1812.
The cost of outdoor relief in 1810 dropped from 11¼ to 7½
pence per head of population. In New Zealand, also, the
expense per capita of the population on poor relief fell 10.5
per cent. from 1888 to 1801 as a result of a grant of 11,000
pensions. Moreover, as is advanced by a dissenting member
of the Massachusetts Commission, the argument of heavy expense:
“is fallacious, for the ultimate expense of any given project
is the same, whether that cost be levied directly upon those who
are to benefit by the scheme, as in the proposed contributory
scheme, or indirectly upon the same beneficiaries through the
medium of the State tax.”[238] Again Dr. Rubinow justifies the
increased cost on the ground that: “when an institution is to be
established, first its necessity, its usefulness, or harmfulness must
be considered, and only then the question of ways and means comes
into the foreground.”[239]
(2) Straight pensions, it is contended, is class legislation,
as they tax the rich for the benefit of the poor. “There is
no real ground for the assertion that because an industrious
230man has failed to earn a sufficiency, he has a right to be rewarded
for his industry out of the proceeds of a tax levied upon
his neighbours, to whom he has rendered no service, or none
which has not been paid for in wages.”[240]
(3) Gratuitous governmental pensions, some argue, would
destroy the habit of thrift, as it would lessen the sense of personal
responsibility and independence. The ultimate test
of a pension system, it is contended, is not the degree of comfort
and security bestowed upon the aged poor but its effect
upon the character and self-dependence of the workers. A
pension to all, it is claimed, puts no premium upon thrift and
would only demoralize the class it is intended to help. This
case is stated by a leading opponent of social insurance in
this country as follows:
“It (gratuitous pensions) will undermine and tend to destroy
the self-respecting character of our people as citizens of a democracy
where economic independence achieved by individual efforts,
self-sacrifice and self-denial, is, after all, the only aim worth while.
However much we may be inclined to permit ourselves to be
deceived by specious arguments of guesswork philanthropy into
believing the gift is to help the recipient and not to hinder, such
gifts, with rare exceptions, are opposed to principles of character-building
and of a character-maintenance throughout all the years
which constitute the span of human life.... Hold out the prospect
that such effort is not necessary, that earnings may be
squandered for a thousand and one needless purposes, that restraint
upon family expenditures is not required, and the most
powerful incentive which makes for character and growth in a
democracy is taken away.”[241]
President A. T. Hadley, of Yale University, also stated:
“We need measures which shall increase individual responsibility
rather than diminish it; measures which shall give us more
231self-reliance and less reliance on society as a whole. We cannot
afford to countenance a system of morals or law which justifies
the individual in looking to the community rather than to himself
for support in age or infirmity.”[242]
The moral level upon which the above arguments are based
is obvious. These critics who display so much apprehension
of undermining the much talked of habit of thrift with which
every working man is supposed to be endowed, ignore the fact
that the great majority of the people who reach old age and
who qualify for pensions in the countries having pension
systems, is in itself sufficient evidence that there was either
no habit of thrift to be destroyed, or that the conditions of the
wages were so low that savings were impossible, as was conclusively
shown in a previous chapter. Where was the thrift
habit of the 58.8 per cent. of the aged 70 and over who in
1812, when pensions began to be paid out, qualified for pensions
in England and Wales; the 68.4 per cent. who qualified
in Ireland; the 34 per cent. in rich Australia and New
Zealand; the estimated 16 to 26 per cent. in prosperous Germany;
the 35 per cent. in thrifty Denmark, and the 50 per
cent. of the aged who qualified for pensions in the land of the
most thrifty of peoples, France? It is preposterous to contend
that the habit of thrift can be destroyed by a pension,
which at best, is hardly sufficient to keep body and soul together—paid
at the remote and uncertain possibility of attaining
old age. On the contrary, it would doubtless prove an
incentive to saving, as the pension allowance meeting only the
bare necessities would enable a person with a little savings to
spend his declining days in comfort. The Wisconsin Industrial
Commission, in its report of 1815, points out that non-contributory
pensions do not discourage savings and cites the
example of Denmark, which was the first to establish such
a system, and where after twenty years of experience the number
of applicants for old-age pensions shows a tendency to decrease
232rather than the contrary, so that it cannot be said
habits of thrift have declined.
“I have found in Denmark that the people who had most right
to speak with authority on the subject maintain that the law has
not acted in a way detrimental to thrift. The Inspector General
of the Sick Relief Funds holds that they are more thrifty.” (Miss
Seller’s evidence before Aged Pensioners Committee, 1803, p 5).[243]
“Whether we take Germany, Australia or Denmark, the answer is
the same. Thrift, instead of vanishing before old age pensions,
has actually increased. There has been more money placed in the
German Savings Banks since 1881.”[244]
The Australian Royal Commission, in its report of 1807,
concluded that “The question as to whether thrift is discouraged
by old age pensions has been inquired into by your
Commissioners, and they have arrived at the conclusion that
the fact of a necessitous person being entitled to a pension
of 10s. a week at the age of 65 years will not have any appreciable
influence on saving habits at an earlier age.”
Mr. Miles M. Dawson, is quoted as saying: “I think there
has been an error about pensions checking the savings. In any
country where it has been adopted, in Denmark, Great Britain,
New Zealand, etc., the amount of savings has been continually
enlarging.[245]
In an article in the Survey[246] Dr. Rubinow very skilfully
inquires:
“What other explanation can there be for this over-emphasis
of the virtue of thrift, unless it be the old ascetic principle that
there is virtue in practicing self-denial, in getting along without
things which we need? Humanity’s progress is based upon efforts
233to get things which man wants. Has all human progress been immoral?
“Whose morals suffer therefrom? Even the unworthy old man
or woman over 70 is a weak, dependent, often decrepit, and helpless
person whose immorality represents no danger to society,
and who cannot be permitted to starve or freeze on the streets, if
we are to protect our own moral nature from destruction. And
as far as the young men and women are concerned, their conformance
or non-conformance to the recognized moral precepts will
scarcely be influenced by the chance of getting an old-age pension
at seventy. Whether it be the hope of rewards, or the fear of
punishment that must be relied upon to raise the moral level,
either seems too remote and problematic. When the fear of
eternal damnation fails, the hope of five shillings per week in the
dim and uncertain future can scarcely succeed any better....
“Why do we continue to worry so much about the morals of the
working class, disregarding the fact that if freedom from anxiety
as to the future must be demoralizing there is a perceptible
element in society outside of the working classes free from such
worries?
“Why can we not recognize the fact that the wage-worker
does not, will not, cannot be guided in his existence by the fear
of what will happen to him after seventy, if he lives so long?
We shall fail to make headway in our social insurance efforts
until we are able to recognize these obvious inevitable facts.
“And if it be true that the morals of the working class need
reform as much as the economic conditions of its existence, by all
means let us think of some more effective pedagogical method
than the threat of contingent punishment postponed until a day
when moral regeneration is both impossible and useless.”
(4) Non-contributory pensions would lower wages. This
argument is based upon the following assumptions: (a) Because
of the direct competition of the pensioned employé.
(b) The prospect of a pension in future years would lead
workers to accept lower wages than they would otherwise be
disposed to demand. This, it is claimed, is the case in some
of the industries where pensions are now established. (c) It
234would encourage undesirable immigration, as it would invite
immigrants from outside the state, and thus depress the wage
rates by over-crowding the labour market. The fallacy of
the first of these objections has already been pointed out in
another place, where it was shown that the number of people
still able to do work at the age when pensions are given is
very insignificant. These men at 65 and 70 years of age are
hardly a factor in the labour market. Moreover, this argument,
if true, would apply equally as well to any form of savings
or even to contributions from children. It is evident that
a man with no income whatsoever is a more dangerous competitor
in the labour market than the man with some means
of support. The second argument is obviously far fetched.
It requires considerable imagination to conceive the idea that
the prospect of a very meagre assistance in their old age
would alone be sufficient to make wage-earners work for lower
wages. It is known to all students and government experts
that the wage rates paid, at the present time, do not take into
consideration any savings and bear no relation to necessary
unemployment due to invalidity and old age. While there is
some truth in the contention that in the industries having regular
pension systems the wage rates of certain classes of
workers—especially those past their middle age—may be lower
than in other industries not having such systems, it is because
there is an incentive to work in the one particular industry
over the others which have no such benefits. A state or nation-wide
pension system would in the very nature of such a
plan eliminate this objection. As to the third contention of
encouraging immigration it is not borne out by the facts in the
countries where such systems are in operation. Long terms
of residence within the state are required everywhere, and immigration,
as is well-known, is not popular with men past middle
age. That a small pension given when reaching old age
would hardly be a sufficient inducement to young immigrants,
is self-evident.
235(5) Straight pensions, concluded the Massachusetts Commission,
would have a disintegrating effect upon the family.
“A non-contributory pension system would take away, in part,
the filial obligation for the support of aged parents, which
is a main bond of family solidarity. It would strike at one
of the forces that have created the self-supporting, self-respecting
American family. The impairment of family solidarity
is one of the most serious consequences to be apprehended
from an experiment with non-contributory pensions.”[247]
Mr. A. M. Huddell, in presenting a dissenting opinion
upon this point states:
“The facts that are before us as to the influence of pensions
on the American family have either been entirely overlooked or
misconstrued by the majority of the commissioners. We have
before us the pensions of the veterans of the Civil War, their
widows and orphans, and I fail to find the evidence that warrants
any statement to the effect that this pension by the United
States Government has disintegrated the family, or lessened ‘the
filial obligations’ for the support of the aged parents; or has in
any way impaired the family solidarity. On the contrary, the
pensions to the veterans of the Civil War have built up the American
family, and the filial obligations of the family have been
strengthened and its solidarity maintained. An old person living
with a married son or daughter that is striving to bring up
a family and provide for them as an American family should be
provided for, and give to the children a proper education, can find
a place for the old veteran or his widow who receives a pension
from the Government in the family, because they do not take away
from the family any of the necessities of life, or stop in any way
the education of the children. At the same time, the independence
of the veteran or his widow is maintained, because they have
enough to pay for their needs at that period of life.... With
this pension the old veteran and his widow are made comfortable
in their old age by living with their children, their friends, or in
236homes where they are paying their own way, and have a feeling
of independence that old people should have. They know they
are not taking away from the family any of the necessaries of
life, or hampering the education of the children through any
expense of their own support. Any extra expense in the workman’s
family directly affects the education of the child, compelling
him to leave school and seek employment to help maintain
the family.”[248]
The same argument is also answered by Mr. L. W. Squier
as follows:
“Fortunately or unfortunately, according to the standpoint of
religion and economics from which one views the matter, we
Americans have not that conception of the family as the unit of
society, as the Oriental in all his religious and economic training.
In China and Japan it is rare to find any individual in
want about sixty years of age, who has not some relative, no
matter how remote, whose ethics and religion command him to
make a place in his home for the indigent one, and provide for him
as if he were a member of his own immediate family. Almshouses,
private indoor or outdoor relief, for the old, are hardly known in
these Oriental lands, where high ethical regard for the aged is
instilled in the individual’s common mind from infancy. Unfortunately,
however, in this country no such esteem for the aged
prevails except among his near relatives and especially in agricultural
communities. In our manufacturing centres especially,
the helpless, destitute grandfather or grandmother is regarded
as a distinct burden to the household, the carrying of which oftentimes
forces the children out of school and into the streets, factories,
or shops, in order to provide for the added increment to the
household expenses which the taking on of an aged relative, no
matter how near he may be to the immediate family, entails.”[249]
Dr. Rubinow answers it this way:
237“There is a good, old-fashioned atavistic nobility of sentiment
about this argument which will greatly please all good men and women
except those who have to be supported by their children, and
those who have to support their parents and also their own families
on a wage-earner’s budget. Scientifically the argument is certainly
original, because it assumes the basis of the family to be the
support of the older generation by the younger, while it has always
been fairly well agreed upon by all students of society that the
shoe was on the other foot, and that the care of the children by the
parents was the proper function of family. It further seems to
assume that we love our burdens, and that when parents cease being
burdens the children cease loving them.
“It assumes that the standing of a superannuated parent in a
family is in an inverse proportion to the amount he is able to contribute
to the family budget. It is an appeal to an ideal of patriarchal
family which has been dead for a century in every industrial
country, and which really never had any strong hold upon
American life. Of course, its inapplicability to the aged single
man or the aged spinster aunt will be evident. For it certainly
cannot be claimed that the support of all spinster aunts is also a
fundamental principle of American family solidarity. Then again
even married people may not have any children, or may have lost
them. One must remember that New England was practicing
race suicide long before the term ever became popular. As a
matter of fact, the very data gathered by the Commission shows
that of the inmates of almshouses and benevolent homes over
twenty-five per cent. were single and of those receiving outdoor relief
fifteen per cent.
“Furthermore, these data also show how these almshouses and
homes do break down the solidarity of the American family. Of
their inmates forty-two per cent. had adult children living at
time of entrance, of the several thousand pensioners receiving outdoor
relief, sixty per cent. had adult children at the time of investigation,
and fifty-nine per cent. other near relatives. It is really
surprising that the Commission did not recommend discontinuance
of aid, both institutional and outdoor, because of the demoralizing
effect upon said children and relatives.
“However, the same table which conveys the information just
238quoted shows that while there were children in some 60 per cent.,
in only 22 per cent. were they able to render aid; that this proportion
was only some 10 per cent. in case of the inmates of homes, and
about 50 per cent. in case of persons receiving outdoor relief.
Moreover, it appears from another table that some 40 per cent.
were receiving aid from children or relatives, as outdoor relief is
seldom bountiful.”[250]
From the investigations of the Pennsylvania Commission on
Old Age Pensions it was disclosed that in the case of inmates
of both almshouse and benevolent institutions over sixty-five
and a half per cent. had no children living. Of the aged applicants
for relief, about forty per cent. had no children, and
among the general aged population, although the percentage of
those having no children at all was little more than 10 per cent.,
only 24 per cent. of the aged were actually supported by
children, while 43 per cent. had no other sources of income.
(6) Straight pensions are objected to also because they
resemble charity much more than a system of insurance in
which the worker makes a contribution. This, however, depends
largely upon public opinion. Considered in the light
of deferred real wages instead of poor relief, the receipt of
a pension would not involve any degrading effect.
Professor Coman, an opponent of the straight pension
system, stated[251] that in her investigation of the Danish old
age pension system every Dane interrogated—from tax-payer
to administrator—as to whether the pension was merely a new
form of poor relief answered “No.” In Great Britain also
it is declared old age pensions are not looked upon as poor
relief but as an annuity due them from the government.
(7) Non-contributory pensions by the state, argues the
Massachusetts Commission, will result in “mischievous political
239effects. It would open the door to political favouritism of various
sorts.” William H. Lackey contends that “Such a question
would infallibly pass into the competitions of party warfare.
It would become in most constituencies one of the most
prominent of electioneering tests. Rival candidates would be
competing for the vote of a wage-earning electorate who had
a direct pecuniary interest in increasing or extending pensions
and in realizing the conditions on which they are given. Can
it be doubted that in many cases their first objective would be
to outbid another, and that national and party politics would
soon be forced into a demoralizing race of extravagance?”[252]
These apprehensions of the Massachusetts Commission and
Mr. Lackey have so far, however, not been realized in the countries
that have established such systems. Even critics of
these schemes have so far made no contentions that party
politics has deteriorated or been affected considerably by the
pension plans.
(8) The constitutionality of a non-contributory scheme is
also questioned by the Massachusetts Commission. Strangely
enough, however, it admits that firemen, policemen and teachers
who “are not only rendering peculiarly hazardous meritorious
services to society, but also have deprived themselves
of the full opportunity of earning the largest returns for
their services in a competitive way ... have some claim upon
the State for special consideration in the matter of public
support in old age. This claim, however, cannot exist in the
case of persons employed in the ordinary competitive callings.”
The fallacious reasoning of the Commission at this point is
self-evident. Surely, those who toil in the bowels of the earth
mining coal for the industries of the nation, those who bring
the milk to the babies in the city, and those who provide us
with food, clothing, shelter, and other necessities are just as
essential to the public welfare as the classes enumerated by
the Commission!
240The basis of the Massachusetts Commission’s opposition
to the non-contributory system is summed up in its concluding
paragraph as follows:
“A non-contributory pension system is simply a counsel of despair.
If such a scheme be defensible or excusable in this country,
then the whole economic and social system is a failure. The
adoption of such a policy would be a confession of its breakdown.
To contend that it is necessary to take this course is to assume
that members of the working class either cannot earn enough, or
cannot save enough, to take care of themselves in old age. If
that be true, then American democracy is in a state of decay which
no system of public doles could possibly arrest, but would rather
hasten.”[253]
While the premises of the Commission are evidently true,
as was shown conclusively in the earlier chapters of this book,
it does not necessarily follow that its conclusions are logical.
Woe to the patient whose physician upon diagnosing his illness
throws up his hands in despair and rather than operate
or admit the origin of the illness permits him to die, because
he had discovered that the cause is a real one and not an
imaginary one!
In any discussion of the merits of the compulsory-contributory
or non-contributory pension systems, the question whether
it should apply universally or only to a partial extent is
always to be taken into consideration. As compared with the
present policy of poor relief, a universal pension plan means
a complete reversal of this method. It is based no longer upon
the theory of relief of destitution only. It aims to extend
pensions without any conditions to all, or almost all, the aged
above a certain age. The funds are to be drawn from the
241common purse. This would necessarily involve a steady increase
in both the number of persons and cost and would, as
stated by Sir Charles Booth, mean that “The policy of doing
so is the opposite of that adopted in savage states, where the
old, when incapable, are knocked on the head.” No such complete
system, however, is as yet in operation anywhere. The
principle of partial insurance or pensions is, as was pointed
out before, established now in many countries. Pensions as
established now by foreign countries are given only to men
and women belonging to certain wage groups or to persons having
fulfilled certain specified requirements.
The universal principle is advanced principally because, it
is argued, if pensions were offered to all aged persons, it
would remove entirely the savour of dependency or pauperism.
Charles Booth, the foremost advocate of universal pensions
in Great Britain, presented the case for such a system as
follows:
“The idea in the minds of those who think that poverty and
desert should be the conditions of relief, tend rather to an elaboration
of the Poor Law, which by classifying those who ask its
aid and varying the awards, shall make them as often a mark of
merit as a stigma of disgrace. I must confess that this, to me, appears
an impossible ideal. I can imagine no court of inquiry that
could be trusted. I believe that the selected poor who receive pensions
or were provided for in almshouses, to which only their poverty
and their good conduct entitled them, would still be considered
and consider themselves paupers, by whatever name they
might be called. If to obtain a certificate of merit involved a
searching inquiry into the past life of each applicant, it would, I
believe, be strongly resented and most of all by the most worthy.
Even the simplest form such an inquiry could take, limiting itself to
proof of thrift, would be unsatisfactory, as the best proof of thrift
would always lie in having no need to apply.
Mr. Booth further argues:
242“Indoor relief lacks humanity and outdoor encourages improvidence.
We are therefore justified in seeking some better plan.
Pensions at 65 are suggested, to be acquired voluntarily with state
aid. But to be effectual, the system must be universal, or the improvident
would still trust to the rates (outdoor relief), and their
treatment unceasingly oscillate between foolish kindness and unpopular
severity. If the system is to be universal, it must be compulsory;
and if compulsory, its cost, however collected, is taxation.
Moreover, to be satisfactory, the system must apply to the old of
our own time. We shall not tax ourselves for a benefit only to be
realized after 40 years have passed. But if this system is to be
universal, and to apply to our own old people, the forms of insurance
become absurd. Why ear-mark the payments and accumulate
funds at all? It is not insurance we require but the endowment
of old age.”[254]
In another connection he states:
“Benefits which all may enjoy carry with them no slur. Educational
endowments as enjoyed by the rich, free elementary education
as bestowed upon the poorer classes, the facilities offered by
free libraries etc., are cases in point. Pensions open to all and
paid for out of taxation would have nothing, either morally or
economically, in common with pauperism.”[255]
And again: “No other plan of selection is possible except at
sacrifice of independence. To select the poor is to pauperize,
to select the deserving is to patronize. To do either is to humiliate.”[256]
In favour of the universal plan is also urged its simplicity
and cheapness of administration. This system requires no
complicated or troublesome conditions of eligibility, nor does
it entail many details.
Many of the objections to the universal plan have already
been stated in the discussions of the compulsory and non-contributory
243systems. What has been brought against the former
systems may be applied equally well, and even more justly
to the universal scheme. Additional objections may be
summed up as follows:
(1) Its increased cost. A universal scheme is obviously the
most costly of all pension systems, and, to give a pension to
all people—well-to-do and wealthy who do not need them—is
a waste of money.
(2) There are also objections against the giving of pensions
indiscriminately to undeserving persons such as criminals
or paupers. “The inclusion of criminals and paupers
within the pensionable population is indefensible on any
ground of individual desert or public policy. Such persons
clearly have no claim to a pension, whatsoever may be true
of the deserving and respectable aged poor. Moreover, the
policy of pensioning the industrious and thriftless, the sober
and the intemperate, the deserving and the undeserving, indiscriminately,
would be in the highest degree pauperizing and
demoralizing. It would put a premium upon thriftlessness
and dependency.”[257]
(3) Any such state-wide scheme has no finality to it. Once
embarked upon this venture, there would always be the agitation
and temptation to reduce the age of pensioning and increase
the pension amounts.
(4) Under a universal scheme there would be even less
means of preventing fraud and imposition. This, it is pointed
out, is continually taking place in army pensions.
(5) The pensioner may dissipate his income on the day
when it is paid. The pension would benefit little those who
are too old or infirm to live alone and must reside in institutions.
(6) No country has as yet embarked upon such a broad
pension plan.
244
The movement for the inauguration of a definite and constructive
social policy in regard to the superannuated workers
in the U. S. is of comparatively recent origin. Aside from military
and municipal pensions, government insurance or pensions
in old age are not known in this country. Indeed, while in England
legislative committees were seeking a solution for the
problem of old age as early as the beginning of the 18th century,
the first study of conditions of the aged in this country,
authorized by a State Legislature, was not made until almost
a century later. The first such study in the U. S. was authorized
by the Massachusetts Legislature in 1807. Furthermore,
while practically every government in Europe has now in operation
a definite system of old age protection which has, in some
countries, been in existence for many years, legislative solution
of the problem of old age dependency in this country seems, as
yet, so distant that it is almost considered an utopian ideal.
Although much more consideration has been given this
problem by the different industrial organizations, who are confronted
by it as a pressing economic problem, it is surprising
to note that even in this field the movement has spread largely
within the last decade. As was pointed out in an earlier
chapter, the railroad concerns were the first to establish retirement
systems; but prior to the present century there was practically
only one railroad in the U. S.—the Baltimore and Ohio—that
had inaugurated a pension plan for its aged employés.
It is very likely that more than three-fourths of the pension
systems of industrial concerns now in operation, did not begin
245to appear until the last decade. In 1810, L. W. Squier
upon sending out over 1,000 letters of inquiry to the largest
employers of labour in the country, found only 28 systems
of old age pensions of one kind or another in existence at that
time. The Massachusetts Commission in the same year found
only four firms with regular pension systems in that State.
In 1818, also, the Pennsylvania Commission in canvassing all
concerns in that State employing 500 and more workers, found
only about 20 such concerns, exclusive of railroads, having a
regularly established pension fund. Half of these, however,
were not Pennsylvania concerns, but national in scope, such
as the packing houses, International Harvester Company, etc.
A thorough canvass made by the New York Merchants’ Association
in 1820, revealed only 142 regular systems throughout
the country. The negligible number of employés in the receipt
of such pensions has been already pointed out. Similarly,
the scanty protection against old age afforded the working
masses, by means of municipal pensions, fraternal and
trade union insurance has also been shown in earlier chapters.
Although, from a pragmatic viewpoint there is little to
point to tangible achievements along the line of old age insurance
or pensions in the United States, the first steps towards
a definite policy in regard to this problem have, nevertheless,
been made within the last fifteen years—especially during the
decade preceding our entrance into the European war. During
that period a remarkable interest in this problem was displayed
not only by numerous industrial concerns, business and
commercial groups, and students of social insurance, but the
first steps towards active governmental participation were
actually taken by the appointment of a number of State Commissions
to study this problem, through the endorsement of
this movement by many high Federal and State officials, by
the introduction of a number of bills in Congress providing
for such pensions and by the actual adoption of a straight
pension plan in the State of Arizona, the establishment of a
246savings bank system in the State of Massachusetts, and
selling of insurance by the State of Wisconsin. The State
Commissions, together with the pioneer students and advocates
of social insurance in the United States, have, during the last
fifteen years, created a formidable and exhaustive literature
upon the subject, which at least takes these discussions out
of the realm of speculation and ignorant controversy and
places the entire problem upon a sound basis of fact and
knowledge of conditions as they prevail in the United States.
As in the case of most social legislation, Massachusetts
was the pioneer in providing some legislation in regard to the
aged. Its savings bank system was authorized by the
State Legislature in 1807. Under this insurance system the
following forms of insurance are offered to residents of the
Commonwealth of Massachusetts, or persons regularly employed
therein: (1) Straight Life Insurance; (2) Twenty Payment
Life Insurance; (3) Twenty Year Endowment Insurance;
(4) Old Age Annuities; (5) Combination Insurance
and Annuities and (6) Immediate Annuities. The maximum
life insurance policy written is $4,000 and the maximum annuity
cannot be for more than $800 per year.
The expenses involved in the administration of the savings
bank insurance are borne largely by the State. In order to
reduce the expenses involved in this form of insurance, banks
are not permitted to employ paid solicitors or house-to-house
collectors of insurance premiums. In addition, dividends to
stockholders are also eliminated. As a result of this, it is
claimed that savings banks are able to offer insurance at considerably
lower rates than the rates formerly charged by commercial
companies. In addition, every policy holder at the end
of each year receives a check from the bank representing his
share of the net profits of the business. The different insurance
banks have agencies in large manufacturing and commercial
establishments, people’s institutes, social settlements
and trade unions.
247In 1807 the Massachusetts Legislature also adopted a resolution
providing for: “an investigation and report relative
to the adoption of a system of old age insurance and pensions.”
A Commission on Old Age Pensions, Annuities, and Insurance
was then appointed which, after bringing in a preliminary
report, was extended and given a larger appropriation, and
in 1810 brought out a very comprehensive report. This was
the first report of its kind to bring out exceedingly valuable
information in regard to the actual conditions of the aged in
the United States as well as valuable summaries of the
European pension plans.
For five years the Massachusetts Report remained practically
the only official report in this country which dealt
exhaustively with the subject of old age dependency. The
Massachusetts Commission declared itself against straight governmental
old age pensions, on the ground that any such legislation
whether on the subject of old age pensions or insurance,
would be premature at that time. Its arguments against non-contributory
pensions have already been presented in the preceding
chapter. In regard to compulsory insurance the
majority of the Commission declared:
“The adoption of any scheme of insurance in this State appears
to be inexpedient at the present time. The practical objections
to the principle of compulsion are weighty. The idea itself is
essentially distasteful to Americans. In England it was abandoned
as quite out of question, in view of the prejudice against compulsion.
In this Commonwealth this practical objection is reinforced
by constitutional difficulties. In view of these conditions,
it would be futile to recommend any compulsory insurance system at
this time. Whatever the outcome of American experiments with
social insurance may be, whether in the direction of the final establishment
of compulsory systems, or the extension of voluntary
schemes, the introduction of the former can hardly be seriously considered
now. In any event, long training in the development of
voluntary insurance agencies seems desirable, to furnish the preparation
248and foundation of any scheme of State insurance, if such
should be found ultimately necessary and desirable.
“It is conceivable, however, that the final solution of the problem
of old age insurance may be found in some system of obligatory
State insurance.”[258]
On the other hand, Mr. Arthur M. Huddell, one of the dissenting
members of the Commission concluded:
“I am convinced that the fact of being compelled to live in the
poorhouse or dependent upon private charity in old age has a more
degrading influence on character than anything else, and should be
eliminated from among working people. A non-contributory pension
system would stimulate the citizen and help to build up his
character. It would not discourage thrift, as the man who has an
opportunity is only too eager to save, and he would strive to save
over the long road of life to the pensionable age, so as to provide
for the breakdowns by sickness or disease that every man fears.
“The thrift habit is hard to build up among the poorer class of
people because they do not earn money enough to make even a
beginning.”[259]
The Massachusetts Commission also declared that it found
in Massachusetts “no alarming amount of old age destitution.”
It contended: “If any general system of old age pensions is
to be established in this country, this should be undertaken by
the National Congress.”
In 1815, the Industrial Commission of Wisconsin brought
out a concise and able report on old age pensions, though less
comprehensive on its informational side. The Commission,
besides presenting the pension systems abroad, also conducted
an investigation regarding the status of the aged population in
Wisconsin. Although the Commission stated that “the
present report is not to be taken as an endorsement of any
249plan or scheme of old age pensions, but rather a suggestive
advocacy of legislation, favourable to the idea,” the Commission
did present definite plans for old age relief, which combined
both the straight pension and the voluntary insurance
scheme. Its plan for a straight annuity provided for the
granting of a pension at the age of 65, or 60 years if permanently
incapacitated, to U. S. citizens after they had resided
ten years in Wisconsin. Before a person could qualify for
this pension the plan also stipulated that he must be of good
moral character and that he did not have property above debts,
valued at more than $500, exclusive of a homestead, nor more
than $2,000 inclusive of a homestead. The applicant could
have also no income more than $300 per annum if married,
nor more than $200 if single. The amount of pension was
proposed to be “such a sum which, when added to the applicant’s
other means of support, from whatever source derived,
will suffice for the reasonable comfort and well-being of the
applicant, but no pension shall exceed the sum of $150 per
annum per each person.” In order to raise the necessary fund
the Commission suggested that one-half of it be furnished by
the State and the other half by the county. The State’s
quota, it was proposed, “should be raised by a special poll
tax of $1.50 per annum, upon all citizens of the State between
the ages of 20 and 60.” The Commission also proposed a State
Insurance system which would sell old age insurance on weekly
or monthly premiums and should offer insurance to trade
unions, fraternal organizations and employers of labour.
The administrative expense of the fund, it was suggested,
should be borne by the State.
In 1817, the Ohio Legislature created a Commission on
Health and Old Age Insurance, which made an extensive report
on Old Age Pensions, giving a great deal of data on the conditions
of the aged in Ohio, the conditions of the inmates of
county infirmaries and a description of the general condition of
250these institutions. In addition, there is some discussion of the
European pension systems. The Commission’s final recommendations
were as follows:
“I. The State should provide for the payment of a weekly pension
not exceeding $5.00 per week to all persons 65 years of age,
but the combined pension and income of any such person shall not
exceed $350 annually.
II. The following shall be excluded:
1.
Aliens and persons who have been citizens for less than 15 years.
2.
Persons who have not been residents of the State for 15 years.
3.
Persons convicted of a penitentiary offense, within 10 years.
4.
Persons who have disposed of any property in order to qualify for a pension.
5.
Tramps and professional paupers.
III. A voluntary system should be established and administered
at the expense of the State so that individuals may purchase
annuities not to exceed $10 a week by regular payments or by
lump sum purchase.
IV. A person 65 years of age or over who qualifies for a pension,
but does not take his pension until later, should receive the deferred
pension, computed from the date of qualification as an annuity
when he does go on the pension roll. Such deferred pension
shall not be considered in determining the amount of income in
Section I.
V. The property in excess of $100 of any person who receives
an old age pension shall, upon the death of such person, be transferred
to the State for disposal and from the proceeds thereof shall
be deducted the amount which has been paid to the pensioner.
Any residue shall then be paid to the lawful heirs.
VI. The old age pension system should be administered by a
State Board of Pensioners, consisting of three members.
VII. A County Board of Welfare should be created to combine
all of the welfare work of the county, including administration of old
age pensions, mothers’ pensions and blind pensions. The board
should be unpaid and should employ a county welfare director
251selected from a civil service list without regard to residence or
political consideration.”
Shortly after the appointment of the Ohio Commission, the
Pennsylvania Legislature also created a Commission to Investigate
Old Age Pensions. This Commission because of its very
limited appropriation and short period of work could not
arrive at definite recommendations. It therefore asked the
Legislature to extend its life for a longer period. It brought
out, however, in 1818 a very comprehensive report upon the
subject. The Pennsylvania Commission’s investigations of
the aged in that State covered a wider scope and included
phases not previously dealt with by any of its predecessors.
It made exhaustive studies of the dependents in county poorhouses,
private benevolent homes, and aged persons who resided
in their own homes. It also made a study of the moral and
financial conditions, as well as the general management of Pennsylvania
almshouses. In addition, the report contains a summary
of a great many pension schemes for old age protection
as operated in foreign countries. The Commission summarizes
its findings in that State as follows:
“Aside from the aged dependents found in almshouses, benevolent
or fraternal homes, and those receiving public or private relief
there is a considerable proportion (43 per cent.) of the aged
population 50 years of age and over, in the State, who, when reaching
old age have no other means of support, except their own
earnings. Only a small percentage (38 per cent.) of the general
aged population in the State claim to possess personal property of
their own. This would indicate clearly that many of these aged
folk—when their power of earning is steadily declining with advancing
years—will fall dependent, in many cases through no fault
of their own, either upon the State or upon private charity. The
investigations also show that in most of the industries in our State,
many workers become unfit before reaching the age of 50, with the
inevitable result of steadily decreasing earnings. In certain
industries, like that of the railroads, for instance, it appears that
252more than half of the workers become impaired before their 50th
birthday. It is also shown that when the prime of life has passed,
many Pennsylvanians are compelled to change their occupations,
which ordinarily involves a decline in wages. This decline, with
the majority of aged people, appears to be due entirely to sickness
and enfeebled age. The increasing problem of old age stands
out even more significantly when it is remembered that while the
earning power of most wage-workers is steadily decreasing, after
a certain period of age has been attained, the expenditures on food
and rents, even under normal price conditions, remain the same,
while that on medicine is steadily increasing. The investigations
also disclose that as far as Pennsylvania is concerned, the problem
of support of the aged is largely a native problem, rather than an
imported one. The immigrant paupers all claim to have had a long
term of residence in both the United States and Pennsylvania.
“Regarding the aged paupers and the non-dependent aged classes,
the outstanding differences lie, it would appear, in the respective
family connections and physical conditions. In the almshouses
pauper group, 40 per cent. were found to be single, 38 per cent.
widowed, and only 16.8 per cent. married. Among the inmates of
benevolent homes for the aged, the percentages were 30.1 single;
58.3 widowed; and only 7.8 married. More than 65 per cent. of
both of these groups had no children living and of those that had
children, more than 80 per cent. were reported unable to help support.
On the other hand, among the non-dependent aged, only
5.4 per cent. were found to be single, 38.2 were widowed, while
55.1 per cent. were married and still living together. Only 10.6
per cent. of the latter group had no children living. Again, of the
paupers nearly 80 per cent. had never possessed any property,
while the percentage of the propertyless among the non-dependent
aged, was 62 per cent. With regard to the physical condition, it is
also shown that while 64 per cent. of the aged persons residing in
their own homes were still in fair or sound physical health, the percentage
of those in good health in pauper institutions was 35.8 in
the case of inmates of the benevolent institutions, and only 12.3
per cent. in the case of the almshouse inmates.
“That dependency in Pennsylvania is not entirely due to the personal
shortcomings of the individuals, is evidenced from the excellent
253recommendations given practically all the inmates of almshouses,
followed up by the Commission, by their former employers.
Giving due consideration to the fact that most humans will strain
a point rather than give a poor recommendation, the reliable qualities
of these inmates are evidenced nevertheless, from the fact that
most of these inmates have served for long periods of time with
one employer (30 per cent. serving for more than 10 years).
“The Commission’s investigations also disclose an exceedingly
confusing and bewildering system of management of our county
poorhouses. Not only do many of the officials connected with
these institutions have little knowledge of the problems involved
in the care of the aged, but there is obviously a laxity in the management
of these institutions and the distribution of county funds.
The State supervision of these aged homes is insufficient, loose and
hardly competent. Careful records are kept in only a few institutions.
There is no uniform method of accounting. Computations
of costs are made in almost as many forms and methods as the men
making them. Many of the per capita costs of almshouses given
in the report of the State Board of Public Charities do not represent
the actual cost. The latter do not include the interest on
farm products. According to the Commission’s estimate from records
submitted by the directors of the poor to the State Board of
Public Charities, the average cost per capita per inmate, in 1817,
was $5.87 per week. The cost in the private institutions was
even higher than that. It is also shown that in a few instances
the per capita costs were more than abnormally high.
“From the Commission’s study of the existing means providing
for the protection of the aged and superannuated, it is also apparent
that they are insufficient and can never be expected to meet
the situation to any extent. It is shown that with all the numerous
forms of aged benefits provided, only about 10,000 aged people in
the State are actually benefited. Of the numerous large industries
in Pennsylvania only about twenty make it a rule to care for
their aged employés after long and faithful service. While all
the large railroads in the State pension their faithful workers—after
a long period of service—the number of railroad workers actually
benefited, as compared with the total number of workers in
this industry is insignificant. It also appears that only the first
254and second class cities in Pennsylvania provide against
age of their various municipal employés. The number of persons
who may expect old age benefits, as such, from fraternal or trade
union organizations is hardly worth considering.”
In its bill, submitted to the 1821 Pennsylvania Legislature,
the Commission proposed a system of non-contributory or
gratuitous old age assistance. The system was to be administered
mainly by a state board created for that purpose,
although county boards were also set up for the purpose of
rendering local assistance in administering the plan. Pension
payments were proposed to commence at the age of 65 and
were to be granted to all men and women, citizens of the
United States, who have resided at least 15 years within the
State. The bill also suggested that in the case of a person
who has lived in Pennsylvania for 40 years, the residence requirements
immediately preceding application should be reduced
from fifteen to five years. Excluded from the receipt of pensions
were the inmates of charitable and correctional institutions;
and those whose income exceeded $300 per year, or
whose property was valued at more than $5,000, inclusive of
a homestead. The bill permitted the retention of a homestead,
when personally used, and provided for the deduction of the
total amount granted in pensions, from the proceeds of the
accumulated property upon the death of the pensioner. The
maximum pension was set at $25 per month and the funds were
to be raised by the State, either through a special tax, or by
raising the current inheritance taxes. The Commission estimated
that about 100,000 persons 65 years and over in Pennsylvania
would qualify for pensions which would involve an
annual cost of from $18,000,000 to $20,000,000.
In 1818, the Connecticut Commission on Public Welfare
while it made no extensive study of its own of the problem of
old age in that State concluded that:
“We may criticize the ineffectiveness and the cost of existing
255forms of voluntary insurance against the disabilities of age, just as
we may realize that a considerable burden is imposed on the State
by the maintenance of those who, for one cause or another, are
unable either to work or to find work and so become wholly dependent
on the State or on private charity. Notwithstanding this, it
is doubtful if the situation in Connecticut, with regard to the extent
of the disability or the necessities of those who become so disabled,
is so acute as to call for the initial experiment in this report
to be made by the General Assembly.”
Commissions to study the subject of Old Age Pensions were
also appointed by the States of California, Illinois, and New
Jersey. The latter Commissions, however, were instructed to
study both Health and Old Age Insurance and while they have
brought out reports on the health insurance question, have
given little consideration to the problems confronting old age.
In addition to investigating commissions upon the subject,
there have been several attempts at definite remedial legislation.
For several years past the Massachusetts Legislature
as well as the Legislatures of a few other States had a number
of bills presented which provided for old age pensions. In
the 1820 Legislature of Massachusetts five different bills providing
for old age pensions of one form or another were introduced.
So far, these have all met with little success. Definite
legislation on the subject in this country was first made
in Arizona in 1815. Through the initiative and referendum
a law was enacted in that year for the granting of old age
pensions to all needy citizens of the United States who have
been residents of the State of Arizona for at least five years
and who have reached at least 60 years of age. The amount
of the pension was set at $15.00 per month. The act, however,
was promptly declared unconstitutional by the Supreme
Court of Arizona, and no concrete legislation upon old age
insurance or pensions has as yet been adopted by any State in
the Union.
Even the National Congress did not escape the introduction
256of bills dealing with remedial legislation upon the aged problem.
The first bill was introduced by Congressman William B. Wilson
(ex-Secretary of Labour), in 1808. This bill provided
for the establishment of a national old age pension system of
$120 per year for all persons over 65 years of age whose
property possessions did not amount to over $1,500 or whose
income did not exceed $240 a year. This bill was drawn up
under a subterfuge of organizing an “old age home guard
of the United States,” in which the bill proposed men and
women of that age could enlist in order to receive a pension.
Nothing, of course, came out of this bill.
In 1811 Congressman Victor L. Berger—the first Socialist
representative—introduced a bill providing a pension of $4.00
a week or less to all persons 60 years of age and over who
do not possess an income of over $10 a week. The bill
required 16 years of citizenship, good and moral character and
provided for the pension to increase or decrease every twelve
months in accordance with a sliding schedule. This bill
attracted great attention and brought the problem of old age
pensions before the public at that time as never before. Another
bill was introduced by Congressman M. Clyde Kelly, on June
10, 1813. Mr. Kelly’s bill proposed to pension all persons
who have attained 65 years of age, who have been citizens for
20 years, and whose income during the 12 months next preceding
the application did not average nine dollars per week.
The bill excluded from the receipt of pensions, persons who
habitually refused to work, paupers and criminals. The
amount of the pension was graded according to the claimant’s
income, ranging from four dollars per week, if the income was
less than six dollars, to one dollar if the income did not exceed
nine dollars per week. The administration was to be in charge
of the Secretary of the Interior.
Since then several other bills providing for old age pensions
have been presented in the United States Congress. Before
the 66th Congress there was a bill providing for Old Age
257Pensions, patterned after Mr. Kelly’s bill, introduced by
Senator Charles L. McNary, of Oregon. This bill aimed to
pension all persons who have attained the age of 65 years, who
have been citizens for 20 years, and whose income from any
source for the twelve months next preceding the application
did not average six dollars per week. Pensions were not to be
given to persons who had habitually failed to work according
to their ability or who were being maintained as paupers or inmates
of correctional institutions. The bill proposed that
every person who fulfilled the required conditions, should be
placed upon the pension roll and be entitled to receive a pension,
which was to be provided by an annual appropriation from
Congress. The pension was to be graded according to the
following schedule: “four dollars a week when the average
weekly income of the pensioner, as calculated under the act,
does not exceed six dollars; three dollars when the income exceeds
six dollars but does not exceed seven dollars; two dollars
when the income exceeds seven dollars, but does not exceed eight
dollars, and one dollar when the average income exceeds eight
dollars, but does not exceed nine dollars. The bill further provided
that the pension may be increased or decreased every
twelve months, whenever the pensioner’s income increased or decreased,
according to the terms of the schedule. When both
husband and wife are pensioners and living together the pension
of each was to be three-fourths of the regular rate. The administration
of this act was to be in charge of the Secretary of
the Interior.
In tracing the movement for old age protection in the
United States notice must be taken not only of the interest
displayed by the State and national legislatures but also of
the important recognition given this subject by industrial experts,
business and commercial bodies, political and church
organizations and other associations of various kinds as well as
the demands for such legislation steadily and vigorously made
by the growing labour movement of the United States.
258The second industrial conference called by President Wilson,
in its report of March 6th, 1820, declared:
“There have been many plans of health insurance and old age insurance
elaborated in other parts of the world and advocated in
the United States. Without discussing whether such plans, when
based upon government subsidy or compulsory action, are consonant
with American ideals, the Conference believes that an extension
and simplification of the insurance principle as a means of
promoting thrift, saving and independence, would be advantageous
to the people. The alternative to such insurance against
sickness and old age lies in a wage adequate to cover these items.
The Conference therefore suggests that the Federal Government
should inaugurate a careful, authoritative investigation on the whole
subject.
“The problem of health and old age insurance, and its promotion
by some means consonant with national ideals, demands
consideration. If such means can be devised, they will furnish a
relief to the states in the care of the ill, the indigent and the aged.”
So far, the sentiment of the business and commercial groups
in this country has not been very sympathetic towards any
governmental action in regard to the aged. In 1817, the
Boston Chamber of Commerce selected a special committee to
study this problem, which, apparently influenced by the conclusions
of the Old Age Pension Commission of that State, declared
in its report:
“Your Committee has considered various plans for non-contributory
old age pensions and is unanimously opposed to any such
measure with the non-contributory feature for the following reasons:
“1. There is no such need for legislative provision for old age in
Massachusetts as there was in any foreign country in which legislation
has been enacted. Pensions in any case would be less necessary
than health insurance. Health insurance and accident compensation
lead to preventive measures and increase the earning
259power of workers, but old age pensions are remedial, not preventive
and are, therefore, less valuable socially.
“2. These foreign systems which involve contributions from employés
are, therefore, preferable to the English system of outright
payment. In France and Germany the worker gets his pension as
a matter of right even when he is not poor. In England and under
the proposed plan for Massachusetts only the poor may have
pensions. That is, the proposed plan has essentially a poor law
character and is not an industrial measure.
“3. Non-contributory pensions weaken the inducement to thrift.
“4. The inevitable effect of the establishment of a system of non-contributory
old age pensions would be a constant pressure to
lower the age limit and increase the amounts of the pension.
“5. The proposed Massachusetts law would tend greatly to increase
the taxes; and Massachusetts is at present making a radical
experiment with its tax laws. The pensions now proposed are low,
the age of eligibility is high, and few except the almshouse old are
recommended to be dealt with. The proposed tax burden will
therefore increase greatly in succeeding years.
“6. To raise the necessary money large extra taxes would have
to be levied on the capital and industries of the Commonwealth,
This would result in the first instance in a serious disturbance to
present industrial conditions. It might also have a tendency to
lower wages.
“7. Owing to the uncertainty of conditions due to the great war,
it would be unwise for the Commonwealth to assume a large increase
in its liabilities.
“8. The constitutionality of such legislation is extremely doubtful.”
The National Association of Manufacturers also had a committee
studying the problem. This Committee declared in its
report that:
“It is fair to state, however, that every able-bodied man who is
reasonably intelligent and industrious should through his own efforts
on reaching the age of 65, have this provision available.
This does not mean that every man should have set aside enough himself,
although many ought, but certainly should have set aside
something so that with aid from his children, he and his wife
260should have at least the means of existence and not become dependent
on the state or the community.
“Generally speaking, the people of the United States may be divided
into two classes in their means of support upon reaching the
period of superannuation, viz: those who have the means of support
and those who are the subjects of poor relief. This does not
include those who are mentally or physically deficient and who may
be the inmates of public institutions and not regarded as coming
under the category of poor relief.”
And it concluded, that: “After careful consideration of the entire
question of old age insurance and considering particularly the
importance of preserving the best quality of citizenship for the
United States and the maintenance of our institutions on the best
basis, your Committee recommends the following resolutions:
“We believe that evidence is lacking to prove a present necessity
for the enactment of old age pension legislation for the civil
population and we further believe that it is a moral responsibility
of the employer to encourage, assist and inspire his employés
with the importance and necessity of ways and means for making
provisions for contingencies of life, including old age.”
The merits of the above arguments have been discussed
earlier and need not be repeated here. To what extent these
conclusions are based upon facts has also been indicated in
the preceding chapters. However, a more sympathetic note
is struck by Alba B. Johnson, President of the Baldwin Locomotive
Works and of the Pennsylvania State Chamber of Commerce
in his introduction to a special report on Old Age
Pensions prepared for the latter organization in 1818. Mr.
Johnson states:
“A new principle is coming to be recognized, viz: that a large
proportion of those who are unfit for the competition of life are so
through no faults of their own, but because of faults in the social
system for which they have had no responsibility. Their incompetence
is part of the burden which should be carried by the more
competent and the more fortunate. In our complex civilization
there are also many who are rendered unfit by occupation or by accidents
261unavoidable in the processes of industry. The undeserved
penalty therefore should be borne by the community as an essential
part of the cost of production.”
Although planks on social insurance were not adopted by
the leading political parties in the last campaign, despite their
recommendation by the advisory platform committees, the
question has been before the American public as a political
subject by its inclusion in the platform of the Progressive
Party in 1812, while the demand for an old age pension plan
has been a permanent plank in the platform of the Socialist
Party since its beginning and was contained also in the platform
of the Farmer-Labour Party.
The importance of the problem of the aged is now also
recognized by the churches and their leaders. The Federal
Council of Churches of Christ has since 1811 included in its
social creed a plank for suitable provision for the old age of
the workers.
The administrative Committee of the National Catholic War
Council composed of four Catholic Bishops also declared in
their social reconstructive program in 1818:
“The State should make comprehensive provision for insurance
against illness, invalidity, unemployment, and old age. So far as
possible the insurance fund should be raised by a levy on industry,
as is now done in the case of accident compensation. The industry
in which a man is employed should provide him with all that is
necessary to meet all the needs of his entire life. Therefore, any
contribution to the insurance fund from the general revenues
of the State should be only slight and temporary. For the same
reason no contribution should be exacted from any worker who is
not getting a higher wage than is required to meet the present
needs of himself and family. Those who are below that level can
make such a contribution only at the expense of their present welfare.
Finally, the administration of the insurance laws should be
such as to interfere as little as possible with the individual freedom
of the worker and his family. Any insurance scheme, or any
262administrative method that tends to separate the workers into a
distinct and dependent class, that offends against their domestic
privacy and independence or that threatens individual self-reliance
and self-respect, should not be tolerated. The ideal to be
kept in mind is a condition in which all the workers would themselves
have the income and the responsibility of providing for all the
needs and contingencies of life, both present and future. Hence
all forms of State insurance should be regarded as merely a lesser
evil, and should be so organized and administered as to hasten the
coming of the normal condition.”
The demands made by the labour unions for such plans
have already been pointed out.
At the time of this writing there are a number of bills
providing for old age pensions before the various State Legislatures.
Their fate is as yet unknown. But whatever that
may be it is obvious to all students of the problem that the
movement for social insurance in the United States is growing
rapidly and must succeed eventually.[260] On the whole, one may
say, that social insurance in this country is being opposed
by practically the same groups who fought against the adoption
of workmen’s compensation laws, child labour regulations,
and similar social legislation, which are now on the statute
books of practically all states. It may well be that the
inauguration of old age pensions in this country will be preceded
by health and invalidity insurance provisions. But that
a complete program of social insurance cannot for long be
ignored or postponed is now evident to all who are willing to
face the facts as they are, rather than hark back to traditions
or prejudices which have no basis in fact at the present time.
PART FIVE OLD AGE INSURANCE AND PENSION SYSTEMS OF FOREIGN COUNTRIES AND VARIOUS STATES — CHAPTER XIII VOLUNTARY AND SUBSIDIZED SYSTEMS OF OLD AGE INSURANCE — BELGIUM — CANADA — JAPAN — SWITZERLAND — MASSACHUSETTS — WISCONSIN — CHAPTER XIV COMPULSORY-CONTRIBUTORY OLD AGE INSURANCE — AUSTRIA — CZECHO-SLOVAKIA — CHILE — FRANCE — GERMANY — GREECE — ICELAND — ITALY — LUXEMBURG — NETHERLANDS — NORWAY — PORTUGAL — ROUMANIA — RUSSIA — SPAIN — SWEDEN — SWITZERLAND — CHAPTER XV NON-CONTRIBUTORY OR STRAIGHT OLD AGE PENSION SYSTEMS — ALASKA — ARIZONA — AUSTRALIA — DENMARK — GREAT BRITAIN — NEW ZEALAND — URUGUAY
263
265
The first State efforts to relieve the problems of old age
were generally made by means of some form of voluntary or
subsidized savings insurance. The adoption of the compulsory
principle of insurance against old age was unthought of at
first. The States’ assistance was limited to encouraging and
helping the wage-earning classes to accumulate savings which
would protect them against old age. The Teutonic nations
were the first to inaugurate the compulsory principle of social
insurance. In the early days Latin speaking countries were
proud of the fact that they did not adopt the German principle
of compulsion and, instead, established voluntary systems of
savings insurance. English-speaking peoples, on the other
hand, have generally followed the non-contributory or straight
government pension plans.
Voluntary and Subsidized Old Age Savings Systems were
established as early as the middle of the last century.
Although practically all countries started out with voluntary
insurance plans the latter are in operation now in comparatively
few countries. Most nations were compelled to abandon
them as ineffective and substitute either compulsory insurance
or straight pensions. France was the first to follow Germany’s
example in adopting a compulsory old age insurance
system in 1810. Since the signing of the Armistice, Italy
and Spain have also changed from voluntary to compulsory insurance,
while a few other countries have either adopted compulsory
insurance plans or have been considering the adoption
266of such recently. The merits of these plans and the reasons
for their abandonment have been discussed in an earlier chapter
and need not be repeated here. In the chapters that
follow an account of the old age pension systems as they
exist abroad is presented. An effort has been made to bring
them up to date. However, on account of the war, and the
general difficulties of securing European data which resulted
from it, this aim has been only partly realized.
The Belgian “General Savings and Retirement Fund” was
originally founded in 1850. As in the case of all voluntary
insurance plans, it was created for the purpose of inducing
wage-earners to provide for their old age, by affording them
opportunities to save under the protection of the government.
During the fifty years that followed the establishment of this
fund many devices were employed to attract a greater number
of persons to make deposits. This was done by reducing still
further the minimum of deposits, by influencing children from
six to fourteen years of age to join the fund and by appropriations
for annual subsidies made by the national and provincial
governments to mutual aid societies and similar organizations
which induce their numbers to join the fund. In spite of all
these encouragements, however, there was little success made in
securing any considerable number of wage-earners to make
deposits and provide for their old age.
In 1800, a law was enacted which sought further to encourage
wage-earners to provide annuities for their old age
by adding state subsidies to their own deposits and by giving
special grants to the needy aged. The law permitted any
person over 18 years of age to pay into the fund for himself
or for another person. The depositors were not required
even to make regular payments either at fixed periods or of
a fixed amount. The minimum of deposit was one franc
(normally 18 cents). The principal aim of this fund was to
267attract the poorer classes, as the law excluded from benefits
those classes who paid above a certain maximum amount in
taxes or licenses, as well as state officials who were entitled
to old age pensions by virtue of previous laws. The annuities
were paid at the age of 65 and could not exceed 1,200 francs
($231.60). In addition to the regular annuity the government
made a contribution in the form of a premium which was added
to the sums paid by the insured. The government subsidies
ceased when the total credited to the insured person was sufficient
to secure him an annuity of 360 francs ($72.00).
The government subsidies granted under the law of 1800
were small and did not prove sufficiently attractive to the old
people. The amounts were therefore increased by an amendment
passed in 1803. The latter provided a government
allowance of one hundred per cent. on the first six francs
($1.16) deposited by a person who on January 1st, 1803, was
between the ages of 40 to 45; the subsidy increased to 150
per cent. for those who were between the ages of 45 to 50 on
that date, and amounted to 200 per cent. on the first six francs
for those persons who were 50 years old at the time the law
was enacted. These extraordinary subsidies naturally increased
the number of depositors tremendously. According
to Dr. Rubinow:[261] “In 1880 the number of insured was only
12,000 and under the influence of the subsidies began to grow,
though slowly, and by 1888 it amounted to 168,000. The
systematic granting of subsidies ordered by the act of 1800,
in one year doubled the number of depositors. In 1802 it
reached half a million. The increase in the rate of subsidies
in 1803 brought the number to 636,000 and by 1810 it was
well over 1,000,000.” There are no figures available in this
country to show the tendency of the savings fund since the
conclusion of the war. Savings in general, however, have
greatly increased in Belgium. During the last eleven months
of the year 1818, the Belgian postoffice savings banks received
268deposits amounting to 368,000,000 francs as against
262,000,000 francs in 1818.[262]
The savings fund could not meet the immediate problem
of old age. The Belgian government, therefore, in addition to
subsidizing savings, practically established a system of temporary
old age pension grants. These pensions were given to
all persons 65 years of age and over, provided they were Belgian
subjects and had been residing in Belgium at least one
year prior to their application for relief. These straight
pension grants were given only to workmen, i. e. “men and
women actually working with their hands for an employer, in
consideration of a wage, whether such work be performed on
time wage or piece wage, at home or away from home, and
whether it be domestic, agricultural, industrial or handicraft
work.” The claimant, the law also specified, must be in want,
which was defined as “a state in which the resources of the
person are insufficient to enable him to support himself and
his family in accordance with the standard of comfort prevailing
among workmen of his trade in the district in which
he resided.”
The amount of the straight pension given was very small,
namely 65 francs ($12.55) per year. The pensions were
originally intended to cease in 1811 and government subsidies
were to be given only to those who had made deposits in
the savings fund. However, in May, 1811, the law was further
extended to continue till 1814.
The experiences of the Belgian fund are sometimes pointed to
as indicating the success of voluntary insurance. However,
while it is true that the Belgian experience has proved quite
successful, it must be accounted for by the extreme measures
undertaken to attract depositors. It is obvious that subsidies
of 150 to 200 per cent. would attract a great number of
persons. But these are hardly different from straight pensions.
Prior to the war, it was also claimed by students of
269social insurance that in spite of all efforts, the average annual
payment per deposit in Belgium was steadily declining.[263]
The Canadian Parliament, in 1808, passed an act authorizing
the issuing of government annuities for old age. This
act was amended in 1808, in 1810, in June, 1813, and in 1820.
The law originally authorized the Minister of Trade and Commerce
to make contracts with any person domiciled in Canada
for the sale of an immediate deferred annuity, as follows:
“(1) for the life of the annuitant, (2) for a term of years
certain, not exceeding 20 years, provided the annuitant
shall so long live, (3) for a term of years certain, not exceeding
20 years, or for the life of the annuitant, which ever
period shall be the longer. Also for an immediate or deferred
annuity to any two persons domiciled in Canada during their
joint lives and with or without continuation to the survivor.”
The system of government annuities is at present in charge
of a Superintendent of government annuities in the Post Office
department. Payments are made in three forms: weekly payment,
yearly payment, and single payment. The rates for
females are somewhat higher than those for males. Premiums
may be paid to the department directly or to any postmaster.
Any person resident or domiciled in Canada may now purchase
an annuity. Plans are also provided by which employers
may co-operate with their employés in the purchase of
annuities.
No annuity can be granted on the life of any person other
than that of the actual annuitant. It cannot be less than
270$50 a year and the total amount payable by way of an annuity
cannot exceed $5,000 a year. The age limit of 55 years formerly
required at which an annuity could begin was abolished
in 1820. If the annuitant dies before the expiration of the
specified number of years, the annuity must be paid to his
legal representatives for the remaining number of years,
unless agreements to the contrary have been made between the
State and the annuitant. The rate of interest on moneys
returnable was increased from three to four per cent. by the
1820 amendment.
Up to Dec., 1820, there were a total of 4,857 annuities
issued in Canada. The total receipts up to the same date
were $4,751,677.17. The average amount of annuity purchased
was about $250.[264] This small number of annuitants
is exceedingly significant in view of the fact that the Annuities
Act “was passed in order to promote habits of thrift, and
to afford facilities whereby the people of Canada might be
aided and encouraged to make provision for old age by the
purchase of Annuities” and by the department’s advertising
the fact that under the recent amendment if “a man who began
at the age of 20, to buy an annuity of $500 to commence
at 60—which he could do at a cost of but little more than
one dollar per week—were to die just before the first payment
of annuity was due, his heirs would receive the tidy sum of
$5,181.83.”
In addition to the voluntary system of insurance against
old age, the government has also provided, for the benefit of
the employés of the Intercolonial Railways and Prince Edward
Island Railways, a separate fund which was established by an
act of March 27, 1807, and which was later amended in 1808,
and in June, 1813. Under this fund, the insured persons and
the state contribute equal shares; the latter’s contribution,
however, cannot exceed $100,000 per annum. The employé’s
271first monthly contribution is fixed at three per cent. of the
monthly wages and the remainder at one and one-half per
cent. Pensions are given, (1) to those who have attained the
age of 70; (2) to those who have become physically or mentally
incapacitated; (3) to persons who have attained the age
of 60 and wish to be retired from service (after 15 years of
service in all three cases); (4) to persons permanently disabled,
as a result of injuries while at work; and (5) to persons
who at the time when the act was passed have already
reached the age of 70 and who have been at least ten years
in the service. The amount of the pension is based on one and
one-half per cent. of the average monthly pay received during
the eight years immediately preceding the granting of the
allowance, multiplied by the number of years of service. The
maximum pension is limited to $20 per month, and cannot be
more than two-thirds of the average monthly wage. It is
also provided that before an employé can become entitled to
participate in any of the benefits he must serve six months on
probation, during which period he must contribute to the fund.
The Canadian Royal Commission on Industrial Relations in
its report of 1818 declared:
“We recommend the question of making some provisions by a
system of State Social Insurance for those who through no fault
of their own are unable to work, whether the inability arises from
lack of opportunity, sickness, invalidity, or old age. Such insurance
would remove a spectre of fear which now haunts the wage-earner
and make him a more contented and better citizen.”
A postoffice life insurance system was adopted by the Diet
of Japan in the 1815–16 Session and went into operation in
October, 1816. The business is under the Minister of Communications.
Each of the 7,000 postoffices in Japan acts as
an agency for the receiving of contract applications and the
collecting of premiums for life insurance policies. All persons
272between the ages of 12 and 60 inclusive, are eligible for
insurance.
Policies are of two kinds, whole life and endowment. The
latter are divided into 10, 15, 20, 25, 30, 35 and 40 year
endowment policies. Medical examination is not required but
in all cases individual applicants must have a personal interview
with a postoffice official. Provisions are also made for
group insurance.
On March 31, 1820, there were a total of 1,588,715 insurance
contracts in operation. The total premiums amounted
to $347,085 and the contracts in force to $76,355,222. Over
58 per cent. of the policies were whole life policies and 41.6
per cent. were endowment policies.[265]
In October, 1820, the government established a bureau in
the department of Communications to deal with the question
of State life insurance. Hitherto only a small section had
been engaged in this work. The new bureau with its increased
staff is expected to take up the matter of State life insurance
on much broader lines.[266]
There is no federal insurance law in Switzerland at the
present time. Each Canton makes its own insurance provisions.
As a result both the voluntary and compulsory-contributory
insurance plans can be found there. The two voluntary
cantonal insurance organizations are the Social Insurance
Fund of Canton Neuchatel and the Old Age Insurance
Fund of Canton Vaud. The former is a mutual organization
with optional membership which was established by the
cantonal law of May 15, 1806, and which enjoys a cantonal
subsidy. It provides straight life insurance policies as well
as combination and annuity policies.
273Of the total number of policies in Canton Neuchatel during
the year 1813, 6,620 policies, representing insurance to
the amount of $1,242,820, were straight life insurance policies,
and 7,707 policies representing $2,653,750, were mixed policies
and 545 policies, representing $50,180, were annuity
policies.
The Old Age Insurance Fund of Canton Vaud was established
by a law enacted in March, 1807. This fund combines old age
insurance with the various forms of savings deposits. The
premiums or deposits may be either definite or provisional.
In the latter case deposits may be withdrawn within ten years
after payment. The principal purpose of this fund is to enable
employers to provide for old age insurance for their workmen
without being compelled to risk losing such payments, in
case of the premature death or disability of the insured. The
insurance fund also makes special efforts to encourage deposits
by women and children, especially school children. In addition
the cantonal government makes very liberal contributions to
the premiums or deposits of citizens of the Canton, who are
industrial tradesmen or workmen, whose annuities do not fall
due before their 55th year, and whose annual premiums or
deposits range from six francs ($1.16) and do not exceed 60
francs ($11.58).
The total number insured persons in this fund during the
years 1812 and 1813 were 13,823 definite and 14,886 provisional.
The total premiums received during the same year
were $30,141 and $33,531 respectively, to which there was added
$15,052 and $16,664 cantonal contributions. The total payments
to the insured amounted to only $470 and $724 respectively.
The comparatively low payments are explained by the
fact that the fund has been in existence a short time.
A commission of experts appointed by the Swiss Federal
Assembly to study the problem of social insurance brought
in a comprehensive report[267] in regard to the problem in June
2741818. The Commission recommended the adoption of a Federal
compulsory insurance system against old age and invalidity.
The insurance, it suggested, should be made compulsory
either for certain classes of workers or for the entire Swiss
population. The Commission recommended that the pensionable
age be set at either 60 or 65 years. The contributions,
the experts suggested, are to be made by the insured persons,
the employers, the confederation, the Cantons and the Communes.
It made no definite recommendations in regard to
either the amounts of contributions or the pensions payable.
It left to the law givers to decide whether they shall be uniform
as in France, or shall vary in accordance with earnings,
contributions and age as in Germany and in a few other
countries. The Commission favoured a uniform rate of pension,
however, although it did not preclude a modest graduation
according to the length of time insured, or the taking
out of supplementary insurance.
To meet the immediate needs of the aged, the Commission
recommended the granting of straight annuities to those who
have passed the age limit at the time the law is enacted. This
to apply only during the period of transition, until this class
gradually disappears. The Commission also recommended the
continuation of the voluntary insurance plans now in existence
for purposes of supplementary insurance.
The Massachusetts system of Savings Bank Life Insurance
and Old Age Annuities was devised and sponsored largely by
Supreme Court Justice Louis D. Brandeis and the Massachusetts
Savings Insurance League which Justice Brandeis organized.
The plan first went into operation in June, 1808.
Under the State law, savings banks were authorized to establish
insurance departments, and to issue policies upon the lives
of persons, as well as to sell annuities in accordance with the
regulations provided by the State Insurance Commissioner.
275These savings banks insurance departments have no stockholders
and are established solely for the benefit of the depositors.
The Massachusetts system of Savings Bank Insurance is
a State aided plan in so far as the State largely bears the
expenses involved in the administration of the system, and aims
to give to Massachusetts wage-earners and their families all that
their money can possibly buy of real insurance. Justice Brandeis
stated that the purpose of the act was (1) “To give Massachusetts
wage-earners an opportunity to secure safe life insurance
at the lowest possible cost, as a substitute for industrial
life insurance; (2) To give to Massachusetts wage-earners
an opportunity to make provisions for their old age
by the purchase, out of current earnings, of annuities at the
lowest possible cost. (3) It is also designed to furnish
a partial solution of the problem of providing for the superannuated
workingman, by making the opportunities for saving
the workingman’s money as numerous as the opportunities for
wasting it.”[268]
In addition to purchasing straight life insurance policies,
residents of Massachusetts may, under the State’s Savings
Banks Insurance System, secure also (1) Twenty Payment
Life Insurance; (2) Twenty year Endowment Insurance;
(3) Old Age Annuities; (4) Combination Insurance and
Annuities; and (5) Immediate Annuities. The maximum
annuity is limited to $1,000. Agencies for collecting premiums
have been established by the Insurance Banks in large
manufacturing and commercial establishments, peoples’ institutes,
social settlements, and trade unions. In 1820 there
were more than 300 such agencies scattered throughout the
State. The amounts of the monthly payments for the different
policies are given in a table on the following page.
276
MONTHLY PREMIUMS OF SOME OF THE OLD AGE COMBINATION INSURANCE ANNUITIES IN MASSACHUSETTS
——Old Age Annuity——
Combination Insurance & Annuity
Beginning Annuity at Age
Annuity at Age 60
Annuity at Age 65
$250 Insurance and $200 Annuity at Age 60
$250 Insurance and $200 Annuity at Age 65
15
$1.68
$1.06
$1.88
$1.28
16
1.76
1.10
1.87
1.33
17
1.84
1.16
2.06
1.38
18
1.84
1.20
2.15
1.44
18
2.04
1.26
2.25
1.50
20
2.14
1.32
2.36
1.57
21
2.24
1.38
2.47
1.64
22
2.36
1.46
2.58
1.71
23
2.48
1.54
2.72
1.78
24
2.62
1.62
2.85
1.87
25
2.76
1.70
2.88
1.85
26
2.82
1.78
3.15
2.05
27
3.08
1.88
3.31
2.14
28
3.24
1.88
3.48
2.25
28
3.44
2.08
3.68
2.36
30
3.64
2.20
3.88
2.48
31
3.84
2.32
4.11
2.61
32
4.04
2.44
4.35
2.74
33
4.34
2.58
4.61
2.88
34
4.62
2.74
4.88
3.03
35
4.82
2.80
5.18
3.22
36
5.24
3.08
5.53
3.40
37
5.60
3.28
5.88
3.60
38
6.00
3.48
6.28
3.82
38
6.44
3.70
6.75
4.05
40
6.84
3.86
7.24
4.31
41
7.48
4.22
7.78
4.58
42
8.08
4.52
8.40
4.88
43
8.76
4.86
8.08
5.23
44
8.54
5.22
8.88
5.61
45
10.42
5.62
10.78
6.02
46
11.44
6.06
11.80
6.48
47
12.62
6.58
12.88
7.02
48
14.02
7.14
14.38
7.58
48
15.66
7.78
16.06
8.25
50
17.66
8.52
18.07
8.00
51
20.12
8.38
20.54
8.87
52
23.18
10.36
23.63
10.88
53
27.16
11.54
27.62
12.07
54
32.50
12.82
32.87
13.48
55
40.00
14.60
40.48
15.18
56
16.68
17.28
57
18.28
18.82
58
22.66
23.32
58
27.20
27.88
60
33.56
34.28
For the eleven years the system has been in operation there
were, early in 1820, over 20,000 policies written of all kinds.
277The number of old age annuities was less than 300. The
small number of old age annuitants may be taken as a fair
indication of the possibilities of voluntary insurance in this
country. With a population of nearly four million and after
eleven years’ experience, less than 300 persons are taking
advantage of this form of old age insurance in Massachusetts.
Miss Alice H. Grady, Secretary of the Savings Bank Life Insurance,
while admitting that the Massachusetts experience would
seem to show that the people are either unwilling or unable
to purchase old age annuities, contends, however, that:
“this inference is not entirely correct, the simple fact being
that the people do not know about them. For lack of funds
we have not yet been able to demonstrate what could be done
by means of an educational campaign to teach the people what
deferred annuities are and the advantage of this form of savings
against old age.
“We believe,” continues Miss Grady, “that if the time shall
come when we are able to bring home to our people, by means
of a systematic educational campaign, the knowledge and benefits
of this system, we shall find them both intelligent and responsive
to this form of appeal, and ready to make voluntary
savings against old age, as they are now learning to do against
sickness and death.”
That the Massachusetts experience with voluntary insurance
has proved unsuccessful seems obvious. To explain the
general apathy on the ground of mere ignorance is to ignore
the basic problems discussed in the preceding pages. The
difficulties of saving for old age are unquestionably more
fundamental and are indicative of the success voluntary old
age insurance systems may have in this country. Unfortunately,
the persons who need this insurance most cannot take
advantage of it. However, there are other advantages which,
it is claimed, have come about as the result of the adoption
of the Bay State plan. Miss Grady contends that: “Coincident
with the establishment of savings bank life insurance
278in Massachusetts, the big industrial companies not only improved
the conditions of their policies but also reduced the
cost of their weekly premium insurance about 20 per cent.
The great significance of this reduction has become increasingly
apparent as the years have come and gone. For instance,
during the year 1815, the wage-earners of Massachusetts
alone paid to the industrial insurance companies on weekly
premium policies the astonishing sum of $12,000,000. Had it
not been for the reduction in cost above referred to, it is a fair
assumption that the amount paid to the industrial companies
last year (1816) by our Massachusetts people would have
been not $12,000,000 but $15,000,000. Those $3,000,000
remain in the pockets of the Massachusetts wage-earners or
have been used by them to purchase other necessities of life.
Bearing this in mind it is not difficult to understand why the
State is willing to contribute the modest sum of $20,000 a
year toward the support of an institution which has been
instrumental in bringing about this immense saving to our
people. One might even go so far as to hazard the suggestion
that the people of Massachusetts are getting an extraordinary
good return on an exceedingly small investment.”[269]
In 1811 the Legislature of Wisconsin authorized the issuing
of policies of life insurance and annuity contracts by the
State. This was done by establishing a “Life Fund,” “to be
administered by the State without liability on the part of the
State, beyond the amount of the fund, for the purpose of
granting life insurance and annuities, to persons who at the
time of the granting of such insurance and annuities, are within
the State or residents thereof.”
Applicants must be between the ages of twenty and fifty inclusive.
These may purchase the following policies: (1)
Ordinary life; (2) Twenty payment life; (3) Ten year
endowment; (4) Endowment at age sixty-five; or (5) Term
279to age sixty-five. The advantages of this state fund are:
(1) Its soundness; (2) Its low cost of operation, as profits
are eliminated and no agents’ commissions to be paid; (3) No
great overhead expense, as it is under the State Insurance
Commissioner and only clerical help are being paid from the
Life Fund.
When the Wisconsin Life Fund was established its promoters,
among the many other advantages claimed for it, declared
that: “it is the stepping stone to annuities to protect old age
and perhaps to solving other economic and industrial problems.”
Unfortunately, the life fund in Wisconsin has been a
political pawn. It was sponsored and established during a
LaFollette State administration and the Fund was fairly
successful in its first few years. Then an opposing State
administration came in and efforts to develop the life fund have
slackened until it has become practically unknown in the State.
Today, it is said that the only persons who are maintaining their
insurance policies are the university professors at Madison.
280
A system of old age insurance for salaried persons and several
other classes, was advocated in Austria as early as 1888,
about the time the German Old Age Insurance plan was
adopted. The first bill providing for such insurance, however,
was not introduced until 1801. The first law enacted went
into effect on January 1st, 1808. This act provided a limited
system of contributory old age and invalidity insurance, restricted
to certain classes of salaried employés. On June 25,
1814, the law was’ amended in essential respects by an Imperial
decree, which was to become effective on the first of October,
1814. On account of the declaration of war, an order dated
August 24, 1814, provided that the benefits should be retroactive
as from the first of August, 1814.
Although the object of this insurance also was to build up
a right to an invalidity or old age pension for the insured
persons, the Austrian system differed from most other compulsory
schemes. For instead of being a system of working-class
insurance, it was established for the middle-classes and
the salaried employés. Under this plan only the following
classes were compelled to insure: (1) Employés working in
Austria, who have the character of officials by virtue of their
position; (2) Those engaged in duties of a preponderately
intellectual character, both of which groups must have at least
a total annual income under one and the same employer of
600 kr., (normally $121.80); (3) Those engaged in the managements
281of works or departments of works; (4) Supervisors
over the work of other persons; and (5) Those serving on the
staffs of offices and counting-houses. Salesmen and other
clerks were included under the compulsory insurance only if
they have received the required higher education. The law did
not compel those engaged in domestic service, to insure, or as
workers and apprentices in the production of goods, in industry,
mining, agriculture and forestry. Exempted from the
compulsory insurance were also persons who did not enter an
employment to which the insurance applies until they were
55 years of age; employés of the state, communes, etc., for
whom other provisions have already been made, but only in
case their pension is higher than the lowest provided by the
law. A number of other classes of employés were also exempted.
The obligation to insure under the Austrian law begins at
the end of the 18th year. The insured are divided into six
classes, according to their annual salaries which range from
600 kr. ($121.80), for the lowest class, to over 3,000 kr.
($608) for the highest class. Allowances, gratuities, etc., are
included in the total income. The premium paid monthly for
the six classes, prior to the war, ranged from six kr. ($1.22)
to 30 kr. ($6.08), and by the 1820 amendment was increased in
the same proportion for the various classes. The employer
was made to pay two-thirds of the premium in the four lower
classes and one-half of the premium in the two higher classes.
An amendment adopted July 23, 1820 increased the classes to
16, ranging from 600 kr. as originally required in the lowest
class to those earning salaries of 18,000 kr. in the highest class.
In case of an annual income over 7,200 kr. ($1,461.60), the
insured person was to pay the whole premium himself.
An old age pension was to be paid, in the case of insured
men, either after 40 years of contribution at any age, or it
was to be paid after five years of contribution on reaching the
age of 70. In case of women, only 35 years of contributions
282were required, when the age of 55 had been reached, or after
five years of contribution after reaching the age of 65. This
was changed by the 1820 amendment to 60 for men and 55 for
women. The amount of the pension varied with the salaried
classes and the number of contributions made. The pension
ranged from 180 kr. ($36.54) for the lowest class to 270 kr.
($54.81) the second class; 360 kr. ($73.08) the third class;
540 kr. ($108.62) the fourth class; 720 kr. ($146.16) the
fifth class, and 800 kr. ($182.70) for the sixth class. The new
amendment increased this pension to 645 kr. for the first class
and 5400 kr. for the sixth class. Pensions of half the amounts
were also paid to the widows of insured persons, who drew an
invalidity or old age pension during their lives or had acquired
a right to such a pension.
The administration of the insurance plan is under a central
pension institution and its local offices. In 1811 there
were 108,311 persons insured in Austria. Due to the Allies’
partition of Austria and its general state of bankruptcy, comparative
statistics at the present writing, even if they are
possible, would be of little value.
The State also has had a compulsory old age pension fund
for the government mining employés which was established as
early as 1854. The State paid one-half of the contributions
to that fund.
Compulsory insurance against invalidity and old age for
salaried employés was established in what is now Czecho-Slovakia,
as the result of a law of 1806, which was amended in
1814. The following forms of insurance are offered: (1)
Invalidity pensions in case of incapacity for work; (2) Old age
pensions to men after 40 years of membership, and to women
after 35 years of membership; (3) Pensions corresponding to
one-half of that granted the insured to the widow of the insured;
(4) Grants for the education of children until they reach 18;
283and (5) A grant from the total indemnity in case the insured
dies within the first five years. In the case of invalidity pensions
medical care is provided in addition.
As is the case with the Austrian system the insurance is compulsory
for those who are 18 years of age and upward whose
income exceeds 600 crowns but not over 3,000 crowns. The
contributions from both employer and employé as well as the
pensions are similar to those described in the Austrian
system.
In 1818 the following amendments to the law were to be
submitted to the National Assembly: (1) The age for
admission to be decreased from 18 to 16 years; (2) The minimum
salary conditions to be abolished and new salary levels
to be included in the compulsory law; (3) The invalidity and
old age pensions to be supplemented by grants for education
of children; (4) The provision of a burial benefit; and (5)
That the pension be increased up to the amount of 50 per cent.
if the health of the beneficiary requires the constant care of
outsiders.[270]
In February 1811, a law was enacted in Chile requiring state
railroads to establish an insurance fund for the retirement of
incapacitated salaried employés and workmen and for the
compensation of persons injured in the service.
The fund is made up from the following sources: (1) By
deducting five per cent. from the employés’ wages; (2) By the
retention of the first monthly increase in pay; (3) By the
accumulation of fines and penalties, unclaimed pay, etc., and
(4) By adding 54.8 cents to every $365 receipts.
Office employés who have been in the service for ten years
and who are completely incapacitated for work, may be retired
with as many fortieths of 75 per cent. of earnings
284as their years in service. Day labourers employed in the maintenance
of ways, etc., having ten years of service and totally
incapacitated for work may be retired with 50 per cent. of
wages. Persons engaged in the upkeep of rolling stock, 65
years of age, 30 years in the service and incapacitated for
work, retire with 50 per cent. of wages. The year’s work
must be of not less than 250 days.
Persons permanently incapacitated because of accident are
compensated by the payment of full wages.
For more than half a century France has experimented with
voluntary and subsidized old age insurance, but without success.
Finally in 1810 France was the first country to follow
Germany’s example, and adopted a national compulsory system
of old age insurance. The original act has since been
amended several times, especially by the acts of September
20, 1812; August 17, and December 25, 1815.
The present act provides that all workers and peasants
(salaried or wage-earners) earning less than 3,000 francs
(normally $578) must take out old age insurance. State
employés who do not come under the regulations of civil and
military pensions are also required to insure themselves. The
law exempts several large industrial groups who were already
protected by more liberal compulsory provisions. The insuring
of a person may begin from the age of 12.
The contributions to the insurance fund are of three kinds,
depending upon the age and sex of the insured person. Adult
males pay nine francs ($1.34) per year; adult females six
francs ($1.16) per year; and minors under 18 years of age
pay four and one-half francs ($0.87). The employer is required
to duplicate this contribution and is also made responsible for
the entire payment of the premiums. He is permitted to deduct
285the worker’s share from his wages, and receipts it by a
system of special stamps which are affixed to the employé’s
card.
The age when one may be pensioned is 60. Pensions may
be drawn, however, at 55 with a proportionate deduction in
both the amount of pension and the state subsidy. The amount
of a pension is based upon the number of contributions made
and the age of the insured. In order to obtain a regular pension,
30 payments are required. This is reduced to 28 for all
who have performed at least two years of military service; and
in the case of women, one annual payment for the birth of each
child is deducted from the required thirty years. The State
adds to each regular pension 100 francs ($18.30). This is
still more increased by one-tenth to those persons, of either
sex, who shall have brought up at least three children to the
age of 16. For those who have made less than thirty payments,
but more than fifteen, the state subsidy is computed on
a basis of 3.33 francs ($0.64) for each year of contribution.
No state subsidy is given in cases of less than fifteen annual
payments.
To meet the immediate problem of relief for the aged, the law
of 1810 also provided that all persons who were already 35
years of age at the time the law was passed, must insure. To
those between the ages of 35 and 40, regular state subsidy was
given. If 46 years old, in 1810, the subsidy was raised two
francs and thereafter it was raised two francs for every additional
year at which insurance began. Those over 65 years
of age at the time the law went into effect, were continued to
be given pensions in accordance with previous laws.
On January 1, 1814, the number of insured persons was
7,710,380, of which number 686,821 were voluntarily insured.
The figures given for 1815 were 6,722,332 compulsory insured
and 584,511 voluntarily insured. The year following,
1816, the numbers were 7,078,726 and 510,734 respectively.
286The smaller numbers in the war years are not due however to
an actual decline, as two or three provinces which were included
in 1814, were not included in the two following years, due to the
German invasion.[271]
That the declaration of war affected materially the receipts
of the fund is evident from the fact that while for the first
half of 1814 the receipts amounted to $3,665,833, the second
half of the year yielded only $1,588,135. Indeed a comparison
of the receipts for the pre-war and war years shows that
more than one-half of the persons insured have been unable
to continue their payments into the fund during the state of
war.
The amount of premiums paid into the fund in these years
was as follows:[272]
1812
8,483,740
1813
8,786,428
1814
5,264,858
1815
3,704,035
1816
4,611,287
Since 1811, when the law first went into effect, the number of
persons retired each year was as follows:
1811–12
186,082
1813
706,714
1814
220,825
1815
115,026
1816
87,842
Total
1,326,588
On December 31, 1816, there were 1,158,325 retired persons
under the Labourers’ and Peasants’ Retirement Fund.[273]
The principle of compulsory insurance against infirmity and
old age was applied to French miners long before the adoption
of the general compulsory insurance law. The former
287was established in 1884. An amending act dated February
25th, 1814, repealed the previous legislation and created an
Autonomous Pension Fund for miners, to be administered by
a council of 18 persons, the employers, employés and the government
to be represented by six members each. For the purpose
of forming a basic capital for these pensions, the act
provided that the mine owners pay every month into the fund
four per cent. of the wages of the workers. The regular
contribution is borne one-half by the employers and one-half
by the workers. The right to a pension begins at 55 years of
age. Miners who can prove that they have worked for wages
for at least 30 years or at least 7,820 days (absence on
account of sickness is not deducted) in French mines have
the right, in addition, to a state allowance of 100 francs and
a bonus from a special fund. In case of permanent incapacity
a miner is entitled to a pension regardless of age. The
state was to pay, according to the amended act, 2,000,000
francs annually towards the general administrative expenses
and certain other purposes.
On the ninth of March, 1820, the law was amended providing
for greater subsidies from the state. The state’s subsidy in
the future will be 860 francs per annum for miners, and 430
francs for their widows. The total annual pensions were raised
to 1,500 francs and 750 francs respectively. Another feature
of the amendment is the inclusion of persons, who, after having
worked as miners for ten years, become trade union officials.[274]
On October 21, 1818, a law was promulgated also providing
for a minimum retirement pension of 1,800 francs for each
male employé upon reaching the age of 60 years after 30 years
in the service of the state and 1,500 francs per each female
employé upon the age of 55, after she has been 30 years in the
state’s service. The state’s service includes the following industries:
Manufacture of tobacco and matches; manufacture of
288goods in transit; general bureaus of printing and engraving,
posts and telegraphs, and of mints and metals; military establishments
under the supervision of the ministers of war and
industrial reconstruction; and arsenals and naval establishments.
The pensions are subject to the regulations concerning
premium payments into the national old age retirement
fund.
The law also provides that an employé may be retired for total
disability after 15 years of service in which case the pension
shall be reduced by one twenty-fifth per each year not served
to 25. On the other hand, the pension is increased one-thirtieth
and one-twenty-fifth for those eligible to retirement after
the respective years of service for each year above their limits.
A widow’s pension is equal to one-third of that to which the
husband was entitled at the time of his death. The pension is
increased to one-half of that to which the husband was entitled
in case three or more children under 16 are left.[275]
The comprehensiveness of the French insurance system is
still further evidenced by the fact that in addition to the compulsory
insurance systems, the French law also provides a
system of voluntary insurance which is extended to private
persons with small incomes, small employers of labour, peasant
proprietors, independent workingmen and wage-earners,
with incomes of more than 3,000 francs ($578), but less than
5,000 francs ($865). The Act of December 25th, 1815, also
raised the maximum life annuity from 1,200 to 2,400 francs,
($231.60-$463.20).
Germany was the pioneer in the field of social insurance.
Insurance against old age was first established in that country
in 1888. In 1811 Germany adopted a most comprehensive
system of workingmen’s insurance, which included, besides the
payment of old age pensions, sickness, accident, invalidity and
289survivors’ benefits. Under the German law insurance was made
compulsory for all manual workers and those other wage and
salaried persons whose annual income did not exceed
2,000 marks (normally $476). The obligation to insure
begins with the 17th year.
Prior to 1816, the age of eligibility for an old age pension
was set at 70 years. An Imperial law of June 12, 1816,
reduced this age from 70 to 65 years. This law was made
retroactive taking effect as from the first of January, 1816.
In addition to the payment of old age pensions the German
system also provides for invalidity pensions which are granted
in case of permanent disability before the pensionable age.
The latter is given to all persons unable to earn one-third of
the normal wages in the same occupation and locality. As
would be expected, many more persons are receiving invalidity
than old age pensions. The former has steadily increased
while the latter has steadily declined. In 1814, there were
888,338 invalidity pensions paid, as compared with 87,261 old
age pensions. The comparative growth and decline of the two
forms of pensions may be seen from the following: In 1881
there were 31 invalidity pensions; this increased to 405,335 in
1800; in 1808 it rose to 868,086, and in 1814 it numbered
888,338. The aggregate expenditures for the old age and invalidity
pensions stood as one to two in 1884; it reversed to
two to one in 1800, eight to one in 1808, and eleven to one
in 1812. The reduction of the pensionable age from 70 to
65 reduced this proportion considerably. The consequences
of this reduction for the first complete year, during which it
was enforced, may be seen from the following: The number
of new pensions granted by the insurance offices of the various
States increased from 11,276 in 1815, to 82,120 in 1816.
Those granted by other offices of a special nature rose tenfold
in the same interval.[276]
The insurance contributions in Germany are made jointly
290by the State, the employers and the employés. The State
bears part of the expenses of administration by the payment
of pensions through the postoffices, and contributes, in addition,
a fixed sum each year toward every pension. The
amounts of the weekly premiums that are paid by the employers
and employés are in equal parts. The employer is
made responsible for the insurance of all his employés and
for the payment of their premiums. He is permitted to
deduct the latter’s contributions from their wages, and receipts
it by affixing special stamps to the worker’s receipt
card.
The contributions to the fund are not uniform but vary in
accordance with the annual earnings of the workers. For this
purpose, the insured persons were divided, until recently, into
five classes ranging from those earning less than 350 marks
($83.37) per year, in the first class, to those earning more
than 1,150 marks ($273.83) per year in the fifth class. Until
1817, the weekly contribution for these classes ranged from
16 pfennige ($0.038) to 48 pfennige ($0.114) per week. On
January 1, 1817, however, owing to the extra sums expended
as a result of the reduction in the age limit, the contributions
were increased to 18 pfennige per week for the first class, and
50 pfennige per week for the highest group. Another amendment
was adopted in April, 1820. The new law increased the
weekly contributions from 80 to 140 pfennige respectively
(normally .2104 and .3303 cents).[277] This enormous increase
in the weekly contributions, since the beginning of the war is,
of course, explained by the depreciation of the German money.
Participants of the war were exempted from payments during
the war.
In July 23, 1821, a new law was adopted increasing the
classes to eight and the weekly payments from 3.50 marks for
the lowest class to 12 marks for the highest. It is further
291provided that this law continue in effect until December, 1826.
The German law provides that in order to be eligible for
an old age pension, one must have at least 1,200 weekly contributions.
To meet the immediate problem of old age relief
the required number of contributions was reduced by 40 weeks
for each year of age over 40 at the time the law became operative.
Persons over 70 years of age at the time of the passage
of the law were thus pensioned outright, but they had to show
that they had worked in a trade coming under the insurance law
for three years.
The amount of the old age pension prior to the war ranged
from 110 marks ($26.20) per year to 230 ($54.78) per year,
according to the wage class the insured person was in. The
government’s contribution consisted of a uniform state subsidy
of 50 marks ($11.81) to all pensioners. The minimum annuity
was set at 60 marks ($14.28) for the first wage class. The
annuity was then increased by 30 marks ($7.15) for each succeeding
class until it reached 230 marks ($54.78). On account
of the increased cost of living during the war, a Federal decree
of January 3, 1818, introduced pension bonuses which provided
flat increases in the pensions in order to meet the high cost of living.
The amended law of April 28, 1820, established the following
bonus rates which are granted to recipients of invalidity,
old age, and survivors’ pensions. A monthly bonus of 30
marks ($7.14) is added to invalidity and old age pensions,
while a monthly bonus of 10 marks ($2.38) is added to
orphans’ pensions. By the end of 1820 there was a great demand
for a further increase in the pension rates, on account of
the continued increase in the cost of living.
The German invalidity and old age insurance system is
administered by approximately 50 territorial and special
“institutes” under the general supervision of the central insurance
office. The administration is in the hands of highly
trained experts. To each insurance office are attached several
292boards of arbitration which adjudicate cases in dispute. These
consist of an impartial chairman, a secretary and two representatives
of both employers and employés. In 1814, the total
cost of administration of the insurance system was 24,156,658
marks ($5,754,116). The government’s contributions to old
age, invalidity and survivors’ pensions amounted to 84,500,000
marks ($20,111,000), in 1816.
The German system, in addition to paying pensions, makes
also an effort to prevent invalidity whenever possible. The
invalidity institute has the power to provide a course of medical
treatment, such as would reduce or prevent the loss of
earning power. For this purpose, a chain of 65 or more
sanitoria are maintained, which before the war, treated annually
about 70,000 persons. The war has naturally increased
the work of these preventive institutions. It is claimed that
80 per cent. of the cases treated are discharged as cured.
The institutes are also authorized to invest part of their reserve
in such manner as will promote the social welfare of the
working classes. In order to improve the health and well-being
of the insured persons, the social insurance institutes prior
to the declaration of war, erected model dwellings for
workmen, as well as convalescent homes, people’s baths, labour
colonies, etc. The insurance institutes claim that this has resulted
in a considerable reduction in the death rate and sickness
rate in Germany.
Since the inauguration of the war, the German insurance
carriers have invested a great deal of their money in government
war bonds. Of the 120,000,000 marks net assets
of the Berlin Institution in 1818, nearly 70,000,000 marks
were invested in war bonds. As a result of this, and the continued
depreciation of the German mark since the signing of
peace, the insurance institutes have been in a desperate condition.
In 1818 the Berlin State Insurance Institute had to
borrow about 58,000,000 marks (normally $14,000,000). In
the same year the Institutes suffered a deficit of approximately
2934,000,000 marks. The deficit for 1820 amounted to about
20,000,000 marks.[278]
The average amount of an old age pension in 1814 was
167.88 marks ($40.02) or about $3.33 per month. Because
of the steady rise in wages which decreased the number of persons
in the lower wage groups, the average pension paid has
risen steadily. In 1881 it amounted to 124 marks ($28.54).
In 1800 it was $34.67, and in 1808 it was $38.58. The average
amount of the invalidity pension, increased from $41.60 in
1808 to $46.51 in 1813. In 1817 the average pension was
about $45.24 per year. In 1813 the number of persons insured
under the invalidity and old age insurance act was 16,323,800.
This represented 24.4 per cent. of the total population. From
1881 to 1813 the distribution of the contributions toward the
invalidity and old age pensions was as follows: The employers
contributed $418,026,865, representing 40.7 per cent. of the
total contributions. The insured persons contributed a similar
sum. The aggregate state subsidy during this period
amounted to $181,881,177, which represented 18.6 per cent.
of the total contributions. The total contributions for the
22 years amounted to $1,028,034,807.
In 1818, a German writer declared that it would cost much
more than 1,000,000,000 marks ($238,000,000) annually to
discharge all of Germany’s social insurance subsidies.[279] Representatives
of the German State invalidity insurance institutes,
at a conference in Berlin in May, 1818, declared that, in order
that the heavy burdens may be borne more easily the solvency
and efficiency of the insurance institutes must be assured by
the introduction of higher wage classes for insured persons with
earnings in excess of 1,500 marks ($357.00). It was also
urged that insurance be extended to persons 15 years of age
and to small business men as well as railroad employés with incomes
294of 2,000 to 5,000 marks ($476 to $1,180).[280] In July,
1821, this was increased to invalid persons earning up to
15,000 marks annually.
On January 1st, 1813, the act creating the salaried employés’
insurance system went into operation. This was primarily
for the payment of old age invalidity, and survivors’
pensions. A waiting period of ten and five years respectively,
for the payment of such benefits, is provided, but this period
may be shortened by the payment of extra premiums. Under
this insurance provision, pensions are paid if the earning capacity
of the insured has been lessened by 50 per cent. instead
of two-thirds, as required under the general insurance system.
The contributions here are made by the employers and
employés with no state subsidy. During the year 1816, the
total amount of contributions paid to the institute by the
employers and employés was, in round figures, 113,000,000
marks ($26,884,000). This insurance system was very unpopular,
and the obligation to insure was contested by many
people during the same year. While only few of these special
pensions were given during the year 1816, the insurance institute
for salaried employés granted such other benefits as provided
by law. First of these was the granting of medical and
curative treatments. This insurance is objected to by many,
as it is claimed that its creation was mainly for political
reasons, in order to separate the salaried employés from wage-workers,
as a special class.
The conference of insurance experts in 1818 already referred
to urged that the salaried employés insurance be discontinued
as a special institution, and that it be incorporated
in the general invalidity insurance plan. The conference declared
that: “While the exceedingly expensive salaried employés
insurance in its present form could be tolerated as a
luxury as long as favourable economic conditions prevailed,
this is no longer possible at present, when great economy in
295all spheres has become an imperative duty. It seems, moreover,
not possible to permit this insurance system to accumulate
and hoard a billion marks during the next five years, of
which not even the interest would be paid in benefits to the
insured.”[281] At the present writing there is a movement
supported by the Socialists and the institutes to combine both
systems. On May 31, 1820, the income limit of salaried
employés who are subject to obligatory insurance was raised
to 15,000 marks (normally $3,750) per annum,[282] and on July
23, 1821, was further increased to 17,000 marks.
A compulsory invalidity and old age insurance system for
Greek sailors was enacted in 1807. The cost is divided equally
between the insured, the employers and the State.[283]
Iceland established a compulsory system of old age and invalidity
insurance in 1880. In accordance with the law, “All
servants between the ages of 20 and 60, all day labourers, and
persons working with their parents must annually contribute
to this fund $0.27 for men, and $0.08 for women. The male
head of the household must pay this contribution for every
person who resided with him during the year, but he may
deduct it from the wages of his employés. For the non-payment
of these contributions, property may be attached. The
only persons exempt from paying contributions are those without
means who are responsible for maintaining one or more
dependents who are unable to provide for themselves; those
unable to earn wages on account of sickness or other cause;
and those who have provided for their old age by purchase
of an annuity of at least 150 kroner ($40.20).
296“Pensions are granted to persons over 60 years of age who
have received no poor relief during a prior period of ten years.
The minimum pension is 20 kroner ($5.36) and the maximum
pension granted may not exceed 200 kroner ($53.60).
“Funds are administered in cities by the magistrates, in
rural communities by the parish-council, and these officials may
set aside as their salaries four per cent. of all contributions
levied. They must also elect two persons who audit the annual
balance sheet of the respective funds.”[284]
Like many other countries, Italy first experimented with
voluntary and subsidized old age insurance. The National
Institute for Insurance of Workmen against invalidity and old
age was merely an institution for voluntary insurance and was
established in 1888. Its purpose was to offer protection against
old age to all Italian citizens who were engaged in manual labour
or who on their own account did not pay a tax exceeding 30 lire
(normally $5.78) per annum of any nature. In addition to
the regular annuity the government added a contribution not
to exceed 10 lire ($1.83) per annum. While other classes also
were permitted to insure, the latter were not given the special
subsidies.
The Italian voluntary insurance system was no more successful
than those of other countries. From 1888 to 1810 the
total number of accounts opened was about 300,000, which
constituted only two per cent. of the total population gainfully
employed in that country. During all this time the government
was continuously beset by the demands of organized
labour and social workers for the enactment of a compulsory
old age and invalidity insurance law. During the war the
government was compelled to comply in part with these demands.
Thus in April, 1817, a viceregal decree made it compulsory
for all auxiliary war establishments to insure their workers
in the National Insurance Institute. In accordance with this
297decree over 600,000 workers were insured in the Institute.
Shortly after the Armistice was signed the government introduced
a bill in the Chamber of Deputies, providing for compulsory
old age and invalidity insurance. As the bill was hailed
unanimously by both employers and employés, and in order to
secure speedy action, a decree was issued on April 21, 1818,
establishing obligatory old age and invalidity insurance. The
act went into effect January 1, 1820.
The Italian Insurance Act against disability and old age is
compulsory for (1) All Italian subjects of both sexes, whether
at home or in the colonies, between the ages of 15 and 65, who
work for an employer in any industry, trade or profession,
including “home industries,” agriculture and public service, or
who are occupied in domestic service or in any private employment;
(2) Aliens working at the same occupations, provided
reciprocal treatment is granted to Italians abroad.
The following are exempted from the obligation to insure:
(1) Non-manual workers whose average monthly salary exceeds
350 lire ($67.55); (2) all half-share and tenant farmers whose
annual income exceeds 3,600 lire ($684.80); (3) Men in the
merchant marine service employed on Italian ships who are
already insured in the merchant marine’s Invalidity Fund; (4)
State and public service employees for whom insurance schemes
are already in existence.
The new Italian old age and invalidity insurance law provides
for equal contributions from the employer and the insured persons.
The contributions are based, as in Germany, upon a sliding
scale in accordance with the daily earnings of the insured
person. The bi-weekly contributions are as follows:
Daily Earnings of Insured
Bi-Weekly Contribution of Employer and Employé
2 lire and less
0.50 lire
Over 2 to 4 lire
1.00 „
Over 4 to 6 lire
1.50 „
Over 6 to 8 lire
2.00 „
Over 8 to 10 lire
2.50 „
Over 10 lire
3.00 „
298As in Germany and France, the contributions are collected
by the employer, who affixes stamps to special cards provided
for that purpose. The employer is held responsible for the collection
of both his own and his employé’s shares. He is permitted
to deduct the worker’s contribution from his wages and
penalties are prescribed for incorrect deductions.
Pensions are granted to (1) persons 65 years of age who
have paid at least 240 fortnightly contributions; (2) at any
age in case of permanent incapacity to persons who have made
at least 120 bi-weekly contributions. A person is considered
disabled if his earning ability is reduced to less than one-third
of the current earning capacity of persons working in the
same occupation in the same locality. The pension may be
suspended when the person improves to such an extent as to
make the definition no longer applicable.
The pension amount is made up of two parts. (1) The part
corresponding to the contributions made by the insured person
and his employer, and (2) the part granted by the State.
The first amounts to 66 per cent. of the first 120 fortnightly
contributions, plus 50 per cent. of the next 120 contributions
together with 25 per cent. of the remaining contributions.
The second part is made up of 100 lire ($18.30) for each
pension each year.
The 1818 Decree provides that persons who have undergone
a period of active military service, and persons disabled
through sickness, not exceeding one year, are entitled to
credit of the lowest bi-weekly contributions, even though they
have not made such contributions.
In case of death of an insured person before he becomes
entitled to a pension, his widow or his children under 15 years
of age shall receive a monthly grant of 50 lire ($8.65) for a
period of six months.
When invalidity has been established, hospital treatment may
be provided for a disabled person with his consent by the National
Social Insurance Institute, which bears all expenses.
299The Italian scheme is administered by the National Social
Insurance Institute under the supervision of the Ministry of
Industry, Commerce and Labour. The council of administration
consists of six representatives of the employers, eight of
the compulsorily insured persons, two of the voluntarily insured
persons, five members selected from among social insurance experts,
and one official from each of the following departments:
Industry, Commerce, Labour and Finance, and the director generals
of the National Insurance Institute, the National Accident
Insurance Institute and of the insurance institutes in the
Ministry of Finance. In addition to the National Social Insurance
Institute, a Provincial Provident Institute was established
in each province, which is trusted with the administration
of the present law. The executive committee administering
these institutes is made up of an equal number of representatives
from the ministers of industry, commerce, labour and finance;
the insured persons and the employers. Arbitration boards
as well as boards of appeal are also set up by the decree.
The Italian law provides that insured persons may increase
their pensions through voluntary contributions. Voluntary
pensions may be secured by (1) Independent workers
whose yearly income does not exceed 4,200 lire ($810.60);
(2) Married women of compulsorily insured husbands and all
other women engaged in domestic work; (3) Small peasant
proprietors, shop keepers and professional workers whose annual
direct State taxes do not exceed 200 lire ($38.60);
(4) Those persons who at the coming in force of the present
decree were already voluntarily insured, even though they do
not come under one of the above groups.
The State is still seeking to encourage voluntary insurance
and for that reason contributes in the case of non-obligatorily
insured persons one-third of the annuity acquired through
voluntary contributions, and one-sixth of the total annuity
in the case of supplementary insurance taken out by those
compulsorily insured.
300The Decree provides for an annual contribution by the
State to the National Institute of 50,000,000 lire ($8,650,000)
during the first ten years of the operation of the plan. The
state subsidies are paid from these funds.[285]
A compulsory system of old age and invalidity insurance was
first established in Luxemburg in 1811–12. As in the case of
the Austrian Act, insurance was made compulsory for the higher
wage groups rather than those of the lowest wage groups. The
law compelled all persons to insure who were earning not less
than 3,000 marks ($715) annually. Persons who earned not
more than 3,600 marks ($858) could in addition take out voluntary
insurance. The act also provided for institutional care to
prevent incapacity as well as for the care of widows and dependents
in case of death.
In the beginning, the pensionable age was set at 68 years.
In June, 1814, however, the age was reduced to 65. In order
to receive a pension at that age one must have proved that he
has worked in the Duchy for at least 2,700 days in an occupation
subject to compulsory insurance. The law also provided
that “Luxemburg subjects who on January 1, 1812, are 65
years of age or more, and who prove that during the five years
which immediately preceded this date they have regularly exercised
in the Grand Duchy an occupation subject to compulsory
insurance, shall be entitled to claim one-third of the original
pension.” And further: “Insured Luxemburg subjects who
have completed the 65th year of their age within ten years
immediately following January 1, 1820 ... shall be entitled
to old age pensions, if they give proof that during the
five years immediately preceding January 1, 1820, they have
301regularly exercised in the Grand Duchy an occupation subject
to compulsory insurance, and that since that date up to the
completion of their 65th year they have worked on an average
of 270 days a year.”[286]
The contributions in Luxemburg, as in most countries, are
made by the State, the employers and employés. The State
subsidy, prior to the World War, was a fixed sum of 48 marks
($11.43) for every insured man and 38.40 marks ($8.15) for
every insured woman. In order to provide for these subsidies,
the Act of 1814 set aside a credit of 125,000 francs, to be
paid annually, for 50 years, to the deposit of the Invalidity
and Old Age Insurance Institution. The total contribution
of the employers is at the rate of 2.1 per cent. of the
wages earned. This is divided equally between the employer
and the employé. The former was made responsible for the
payment of the premiums, by the Act of 1811, and was authorized
to deduct the employés’ share from the wages. The Act
of 1814 modified this, so that by mutual agreement, the retention
of deductions corresponding to the contributions due,
may be postponed until the final settlement (this to be not
later than December 31, of each year); while the share of
contributions of agricultural workers, working partly on their
own account and partly for others, is collected direct from
such persons. The amendment also provided that the Managing
Committee of the Insurance Institution may require a security
to be deposited by contractors domiciled in a foreign
country, who temporarily employ in the Grand Duchy persons
liable to insurance.
The contributions to this fund in 1812, the first year of its
existence, were as follows: from industrial and miscellaneous
occupations, 1,338,000 francs, and from agricultural 53,777
francs. The benefits paid out during the fiscal year 1812–13
were 28,464 francs to insured persons in industrial and miscellaneous
302occupations, and 16,045 francs to agricultural
workers.
On the fifth of June, 1813, the Netherlands established a
system of old age and invalidity insurance. The act compels
the insurance of all workmen in the Netherlands over 13 years
of age, who are not in active military service, and whose annual
income is not in excess of 1,200 florins ($482). Compulsory
insurance applies also to seamen and workmen employed in
a foreign country by Dutch establishments. Exempted from
compulsory insurance are those who work for wages only
occasionally and for short periods; those already entitled to
a pension from the State or private establishments; and those
who pay a property or an income tax exceeding 2,000 florins.
The government, it is also provided, is to pay an annual subsidy
to the insurance fund of 10,000,000 florins ($4,020,000),
for a period of 75 years. Prior to 1814, the government also
paid to the districts a subsidy of 50 florins ($20.10) per
pension.
The insured person is entitled to an annuity in the event
of disablement or after the completion of his 70th year of age.
Incapacity is defined as the inability to earn one-third of
the normal wage. In the case of death the surviving children
receive annuities until the age of 13. In order to be eligible
for an invalidity annuity, every insured person must have paid
150 premiums. Persons convicted of crime, recipients of
public charity and those of immoral character are disqualified
for a pension. It is also required that one must have been a
resident of the country for at least 20 years and a citizen for
at least five years before he is entitled to a pension.
As in Germany, persons subject to compulsory insurance are
divided into five classes—those earning less than 240 florins,
the lowest ($86.48), and those earning 800 ($361.80) or more
florins, the highest. The weekly premiums paid vary from 20
303cts. ($0.08) for the first class to 48 cts. ($0.183) in the fifth
class. The premium is paid by the employer, who is entitled to
deduct from the weekly wages a sum ranging from four cts.
for the first wage class, to 24 cts. in the fifth wage group in the
case of adults, and half the amount of the premium for each
wage class in the case of minors. The employers bear a greater
share in the lower wage groups and bear an equal amount in the
case of the upper wage classes. Military conscripts, while in service,
are assigned to the second wage class and their premiums
are paid by the State.
The amount of the annuity is computed as follows: The
pension amounts to 325 times the total of the premiums paid
up, divided by the number of weeks during which the person
has been insured. To this is added 14 per cent. of the total
amount of the premium paid up, which must not be less than
one-fifth of the original pension. “In accordance with this
formula an insured person who has paid 48 weekly contributions
each year, from the age of 20 to the age of 70, and
whose wages were $5.00 a week up to the age of 25, $6.00 a
week up to the age of 30, $7.00 a week thereafter, would be
entitled to a pension of about $2.30 a week at the age of 70.
In the event of his becoming incapacitated at the age of 30,
he would from that time on receive about $1.25 a week.
Should such incapacity not occur until his fortieth year, he
would receive about $1.50 a week, and if it did not occur
until his fiftieth year, he would receive about $1.80 a week.”[287]
The Act also provides that in cases of persons subject to
compulsory insurance, and when permanent disability may be
averted by medical treatment, the “Labour Council” may
cause such insured persons to be subjected to such treatment
or placed in the proper institution at the expense of the State
Insurance Bank.
304In addition to the compulsory insurance system, Holland
also provides a system of voluntary insurance against old age
and disability for those exempted from the former plan.
In February, 1807, a Commission was appointed in Norway
to study the problem of invalidity and old age insurance. The
Commission finished its work in 1812, and submitted a draft
of a bill for a national invalidity and old age insurance
system. This bill proposed that all male and female persons
residing in Norway or belonging to the crews of Norwegian
vessels, Norwegian citizens in Norwegian employment in foreign
countries and Norwegian citizens employed by foreigners
in Norway, shall be compelled to insure themselves against
invalidity and old age. The insurance begins with the age of
16 years.
The proposed scheme provided for the payment of an invalidity
pension, invalidity existing when the earning power is
reduced to less than one-third the normal, after four years
of contributions and after a waiting period of 26 weeks from
the time of invalidity. If a person earns 1,500 crowns ($402)
a year, he is not to be considered disabled under any condition.
The old age pension was to mature at 70 years. An invalidity
pension was to cease as soon as an old age pension was
drawn. Medical and institutional care were also provided in
the proposed bill.
The bill provided that the cost of the administration of the
insurance should be borne by the state and the commune; the
cost of the insurance proper, however, to be met by the contributions
of the insured persons. In addition, it was suggested
that the commune pay 25 crowns ($6.70) annually for every
current invalidity pension. During the time of sickness or accident,
the commune was to pay also the contributions, in
case the insured person was unable to pay them himself.
305The premiums, the Commission proposed, are to be paid
for 50 years, but persons over 70 years of age when the law
goes into effect are exempt from payments. Contributions
were to be two per cent. of the earnings but not less than two
crowns ($0.54) a year. A fraction of one per cent. on the
property of an insured person was to be added to the contribution.
A deduction of five per cent. from the contribution
was made for each dependent of the insured person. No
child over 14, however, was to be considered dependent.
The bill proposed a rather unique system of computing the
amounts of the pension. The framers of the bill argued that,
“On the coming into force of the insurance, the sums at
present expended for public and private poor relief, which are
raised by taxation, will decrease considerably. This should
result in a saving to persons who for some reason or other are
exempt from insurance, and also to corporations, foundations,
and societies, the income of which is subject to special taxation.
If such individuals and incorporated bodies do not give
some equivalent for this saving, they would actually obtain an
advantage at the expense of the insured persons because expenditures
which would otherwise be borne by all persons subject
to taxation would in such case be borne exclusively by
the insured person. Since the national insurance system does
not intend to bring about such a shifting of the social burden,
the bill provides that all persons who have ceased to pay
regular contributions, all persons who are not subject to insurance,
and all taxable corporations, foundations, and societies,
the income of which has not been taxed in the assessment on
their stockholders, partners, or members, must pay to the national
insurance institution an equivalent for their savings in
taxes, the amount of which shall be determined on the basis of
statistical computations.” The Commission, therefore, suggested
that the total fund, in addition to the regular contributions,
should consist also of the insured person’s savings in
poor relief and private support, as well as the current invalidity
306subsidy of the commune. In order to make the pension
uniform, a basic pension of somewhat more than 53 crowns
($14.20) per year was to be paid to the insured person regardless
of the amounts of the premiums paid. The basic pension
was to be increased in accordance with the number of contributions
made, the economic conditions, and the number of the
dependents of the insured person. An additional grant of 15
crowns ($4.02) was provided for every child under 14. If
both husband and wife were receiving a pension, 20 crowns
($5.36) for every child under the age of 14 would be granted.
Contributions, it was recommended, would be collected along
with the Communal taxes. The employers were to pay the contributions
of their employés, as well as those of their employés’
families. The employer might deduct the cost from his employés’
wages. The Commission suggested that if the pension
granted by the usual method of computation were too small, the
commune might grant an increase.[288]
The Republic of Portugal, by decrees issued in 1818, established
a system of obligatory insurance covering sickness, invalidity,
old age and industrial accidents. Invalidity, old age and
survivors’ insurance is made compulsory for all persons from
15 to 65 years of age earning less than 800 escudos (the normal
value of the escudo is $1.08). The classes exempted from this
compulsory insurance include: (1) Public officials already entitled
to pensions; (2) soldiers employed as labourers; (3)
infirm persons who cannot earn one-third of their average
wages and entitled to free subsistence; (4) all other classes of
wage-earners who are already insured.
The insurance is administered by the State under the direction
of the Institute of Compulsory Social Insurance. The
307fund is made up from the following sources: (1) from a six
per cent. assessment on all salaries or wages up to 800 escudos,
which constitutes the employers’ contribution; (2) a similar
assessment of one and one-half per cent. constituting the
employés’ contribution; and (3) by an annual state subsidy
of 13.33 escudos for each soldier recruited. As in other
countries, payments are made by means of special stamps
placed in a book held by the insured. The proportions of the
contributions payable by employers, employés, and the State
may be revised every other year.
The invalidity annuity varies in accordance with the number
of premiums paid into the fund as follows: (1) 235
weekly payments entitle the insured to a pension equal to
one-sixth of the total deferred annuity which may be acquired
under the law; (2) 470 weekly premiums entitle one to a
pension equal to one-third of full annuity; (3) 705 weekly
premiums to one-half of full pension; (4) 840 weekly premiums
to two-thirds annuity; (5) 1,175 weekly contributions;
to five-sixths of full annuity; and (6) 1,410 premiums to
full annuity.
The full old age pension is paid when the insured has reached
70 years of age and has paid 1,410 weekly premiums.
In order to provide for those who were past the age
and who were unable to make the full number of contributions,
the law provides that those who were 45 years of age at the
time the act was instituted shall receive 75 per cent. of the
full annuity; those over 50 years of age, 50 per cent., and
those over 60 years old 25 per cent.
The 1818 Act established also annuities for dependents
which may be procured by extra payments. In addition, the
law provides that any mutual aid association which supplies
disability annuities to labour may become associated with the
Social Insurance Institute by transferring its invalidity, old
age and widows’ and orphans’ fund to the Institute.
Mutual sickness funds, parish councils and labour organizations
308are required to aid the institute in its supervision,
in order to carry into effect the provisions of this decree.[289]
In 1812, Roumania passed a law which established a compulsory
old age and invalidity insurance system in that
country. The Roumanian act follows both the German and
French systems. The contributions, as in France, are uniform
for all classes. They were set at 45 bani (normally 0.87) for
the first ten years from the date the act became effective.
The contributions are divided equally among the employers and
employés. In Roumania also the employer is made responsible
for his own and his employés’ contributions. He may deduct
the latter’s contributions from the wages.
The age of pensioning is set at 65. In order to be eligible
for a pension, one must, have made at least 12 weekly contributions.
The regular old age annuity amounts to 150 lei
(normally $28.85). Invalidity pensions of the same amounts
are paid to the insured persons only after 16 weeks of consecutive
illness. The incapacity annuity is increased by ten
bani ($0.02) for every weekly contribution in excess of 2,000.
Prior to the 1817 revolution there was no general provision
for invalidity and old age insurance in Russia. The only
classes protected against old age were certain groups of government
employés under separate funds. However, as the
Czar’s government controlled a great many industries these
government employés constituted a considerable number. An
old age pension fund granting pensions after 25 years of service
to employés of State mines was established as early as
1787. In 1804 this was extended to all employés of government
factories.
309The miners’ fund paid pensions after 35 years of service,
and required all over 18 years of age, engaged for at least one
year in the work, to become members of the fund. The Railroad
Employés’ Pension Fund required all employés of State
and private railroads to insure themselves. A pension was
paid after 15 years of service. A similar fund existed for the
employés of the State Liquor Monopoly. A separate savings
fund for old age also existed for the workers of factories and
harbour works operated by the ministry of marine. Another
fund against old age was operated for the members of the
volunteer fleet. A compulsory-contributory pension fund was
also established for all the employés of the Zemstvo. Practically
all these funds were controlled by the members of the particular
funds.
In 1814 the government’s contribution to these funds
amounted to 117,884 roubles (normally $60,684).
According to the meagre available information[290] a decree
published by the Russian Soviet government on March 8, 1818,
established a complete scheme of government protection against
sickness, invalidity, old age, unemployment, etc. Pensions are
given to workers having served at least five years in their enterprise
and who have lost their working capacity, and have no
other resources beyond the product of their own labour. The
amount of the pension, in case of complete disability, is equal
to the full wages received. In unhealthful industries a pension
is given regardless of length of service.
Provisions for the creation of deferred life annuities on a
voluntary and State subsidized basis were established in Spain
in 1808. The law enacted in that year provided for a system
of voluntary insurance for wage-workers and State employés
310who earned below 3,000 pesetas (normally $578) per year.
The maximum amount of the pension was limited to 1,500
pesetas ($288.50) per year. The State subsidy varied but
was limited to twelve pesetas ($2.32) per person, during the
first ten years of the institution’s existence. State subsidies
were given only to Spanish citizens living in Spain, provided
they had made some payments into the fund during the preceding
year.
On March 11, 1818, when Parliament was suspended because
of political disturbances, a royal decree made insurance
against old age compulsory, for all wage-earners between the
ages of 16 and 65 whose total annual income does not exceed
4,000 pesetas.
The National Old Age Insurance Institution, which was
established in 1808 is charged with the administration of the
compulsory old age insurance system. The National Institute
is also to be assisted by self-governing benefit societies
set up in each district or province as well as by other insurance
societies. In addition, an advisory committee from among
employers and employés is appointed by the National Insurance
Institution.
The decree divides the contributions into two periods, one
called the “Preliminary or Initial” period, and the other the
“Normal” period. For the first period (the duration is not
stated) the contributions are paid only by the State and the
employers. During the “Normal” period the workers also
are expected to make contributions, and the preliminary annuity
is to be converted into a standard pension, which will serve
to increase its amount.
The insured population also is divided into two groups; one
includes persons who have not yet reached their forty-fifth
year at the time the decree was put into force; the other includes
all those who are 45 years or more.
The initial pension for persons under 45, if there is no cessation
311of work, is fixed at 365 pesetas a year upon reaching
the age of 65.
The contribution of the workers may be used to increase the
pension, or it may be applied to a temporary pension before the
regular pension is due; or it may be applied to an indemnity
for dependents in case of the death of the insured person. The
insured may also increase his contributions so as to obtain
an annuity up to a maximum of 2,000 pesetas or to life insurance
capital up to 5,000 pesetas. The insurance fund is
derived from three sources—the employers, the State, and the
employés. The employer pays an average premium for every
worker, regardless of age, thus making it easier for employers
to calculate the amount of the premium they will be required
to pay and avoiding the possibility of preference for younger
men. The premium rate is fixed at 3 pesetas (58 cents, par)
monthly for each employé under 45 years of age who has been
in the employ of the same employer for one month, and 10 centimes
(1.8 cents, par) per day for shorter periods. The Institute
of National Insurance is empowered to change these
rates as needed. An additional tax of 5 per cent. on the premiums
is levied for administrative expenses. A supplementary
fund from inheritances and other sources is created for increasing
the pensions of those over 45 years of age when the
law took effect. The contribution from the State is fixed at
12 pesetas ($2.32, par) annually for each worker who has been
employed one year, or 1 peseta (18.3 cents, par) per month for
each of those who have been employed one month. The State’s
quota will be increased 25 per cent. after certain groups now
otherwise insured are included. Employés making voluntary
payments may apply their personal quota (1) to increase their
initial pension, (2) to form a temporary pension which advances
the age of retirement, or (3) to form a fund in case of
accident. Unless the applicant specifies, his payments are
used for the first purpose.
312The annuities may also be increased by regional, provincial
and municipal organizations, by employers, or by social insurance
organizations. If the insured person dies before having
reached his 65th year his heirs have the right to the capital
accumulated by his own and employers’ contributions, including
compound interest. In case of invalidity before the age of
65 he may be paid the same sum or may convert the pension
into an immediate life pension. If the pension is sufficient to
provide an annual life pension of 180 pesetas a year it is administered
by the Provident Institute. If the capital is not sufficient
for this, it is transferred to a charitable institution upon
whom the law imposes care of the old person until his death.
The decree offered special advantages to be extended in the
form of increased State grants to employers who had already
provided insurance for their workers or made arrangements to
insure their employés before the law became compulsory.
Greater subsidies are also provided to workers who make contributions
to increase the minimum pension provided during
the preliminary period at the joint expense of the State and
the employer. Employers who fail to make the required contributions
are penalized by being prohibited from taking part
in any contracts of the State, provinces, or communes; from
participating in the benefits of the law in the protection of
industry and from being an elector of, or eligible for, professional
bodies. Old age insurance may be carried through any
of the public or private institutions, provided they come up
to the specified regulations.[291]
The Swedish system of compulsory old age insurance is the
most comprehensive and universal of any now in existence. It
was enacted in 1813. The Swedish scheme is not limited to
certain wage groups, as is the case in practically all countries,
313but applies to every Swedish man or woman above the age
of 16 until the completion of his or her 66th year. The only
classes exempted are persons who are permanently incapacitated
for work; State employés already provided with pensions;
elementary school teachers; members of the army and
navy, clergymen and the wives of persons thus exempted.
The administration of the insurance is in the hands of a
pension committee which is made up as follows: The king
appoints a representative in every pension district in the country.
The latter appoints the chairman of the district pension
committee. Six other members and their substitutes are
elected by the communes.
In Sweden every man and woman from the 16th year on contributes,
in the form of an annual tax or premium, a sum
amounting to three crowns ($0.80). This contribution is increased
by two crowns for those having incomes from 500 to
800 crowns; the surtax is increased by five crowns for incomes
from 800 to 1,200 crowns and by ten crowns for incomes of
1,200 crowns and over. The law provides that the annual contribution
payable by each person shall be collected by the commune
in which the person is registered. The commune is held
responsible for all accounts, and must pay into the fund an
amount corresponding to the contributions that may not have
been paid. The wife’s contribution is to be paid by her husband.
The father is responsible for the pension contributions
for children under 18 years who are registered as residents in
his house. Should the employer pay a contribution on behalf
of his employés, he may retain the sum disbursed out of the
wages paid, within six months of such payment.
The insurance benefit consists in an invalidity pension in
the case of permanent incapacity for work, regardless of age,
and in an old age pension on attaining 67 years of age, even
if incapacity has not yet set in. The amount of the annual
pension for men is 30 per cent. of the total contributions paid,
and for women the pension amounts to 24 per cent. It is also
314provided that pensioners permanently incapacitated for work,
whose total annual income does not exceed 50 crowns ($13.40),
receive in addition to their pension out of the Exchequer 150
crowns ($40.20) per annum per man and 140 crowns ($37.52)
per woman. This State subsidy decreases to one-half if the
pensioner’s income is over 50 crowns ($13.40), and ceases
altogether when the income amounts to 300 crowns ($80.40)
per man or 280 crowns ($75.04) per woman. In the event
of fully paid up pension contributions, the government subsidy
is increased by .08 per cent. for every crown paid. The pension
additions are borne to the extent of three-quarters of the
amount by the State, while the remainder is divided between
the Landsting and the communes.
Excluded from the receipt of pensions in Sweden are those
in receipt of poor relief, habitual drunkards and idlers. If
institutional care is given, the institution may claim the right
to the pension in order to reimburse itself to the amount charged
for the care of the pensioner. Imprisonment or conviction
for more than one month stops the receipt of a pension during
that time. It may be claimed, however, by the dependents for
their support.
The law also provides that in order to become entitled to
a higher pension than that provided for in the act, every
Swedish subject who has reached the age of 15, may, by paying
contributions not to exceed 30 crowns ($8.04) per annum,
become entitled to a higher pension. To all voluntary contributions
paid within each year, an amount equal to one-eighth
of the contributions is added by the government. The amount
of the pension is one and one-half per cent. of the voluntary
contribution in the case of a man, and one-sixth less than
that, in the case of a woman.
To meet the immediate problem of old-age relief, a provision
stipulates that, for persons who during the years 1814 up to
and including 1818, have acquired the right of an addition to
their pension or support, or to an increase thereof, this benefit
315is to be calculated as from 50 to 80 per cent. of the sums
otherwise provided in the act; and for persons who, when the
act comes into force, are between the ages of 25 and 45 years,
27.5 to 20 per cent. for men, or 22 to 16 per cent. for women,
of the contributions paid. The increased cost is borne by the
government.
The total number of pensions granted under this law in 1814,
the first year of the operation of the plan, was 33,138. The
total amount paid was 1,875,457 crowns ($502,622). The
average pension was 56.6 crowns ($15.17). Of the pensions
paid 10,565 were granted to men, amounting to a total of
623,120 crowns ($166,886), or 58.88 crowns ($15.81) per
man; 22,573 pensions were granted to women, amounting to
1,252,336 crowns ($335,625), or 55.48 crowns ($14.87) per
woman. In the same year the total number of persons insured
under this act was 3,225,700. The contributions of the pensioners
amounted to a total of 14,571,000 crowns ($3,805,028),
more than seven times the amount disbursed during the same
period. The number of voluntary cases insured in 1814 was
628.
A system of obligatory state old age and invalidity insurance
was introduced in the Swiss Canton of Glarus by an act passed
in May, 1816. The system is very similar to the one in operation
in Sweden. This act made it obligatory for all persons
between the ages of 17 and 50 who have their legal residence in
the Canton to insure themselves against the contingencies of
invalidity and old age. In case of removal to another Canton
insured persons may retain their insurance by paying an increased
annual contribution. Persons who reside abroad leave
the insurance, but in case they return to Switzerland within
four years they may re-enter the insurance, by paying an increased
contribution for the period of their absence.
316The insurance contributions in Canton Glarus are made up
from the following sources: (1) By an annual contribution
from the Canton of 85,000 francs, and the interest derived
from the Old Age and Invalidity Insurance Fund and other
associations; (2) By an annual contribution from the Communes
of one frc. per head of the population; (3) By an
annual contribution of six frcs. from each insured person. The
annual contributions may be commuted by making a single
payment ranging from 125 frcs. at the age of 17 to 470 frcs.
at the age of 48. Invalidity pensions are payable to persons
who, having been insured for five years, become incapable of
work on account of illness or other infirmities for at least one
year, regardless of their age. Old Age pensions are payable
from the age of 65. Before one can draw an old age pension
to the full amount, however, he must have paid altogether at
least 400 frcs. (i.e. 33 years’ contributions plus interest).
Otherwise, the pension is reduced accordingly.
The amount of the annual invalidity pension begins at 150
frcs. and increases annually by ten frcs. up to a maximum of
300 frcs. for men and 250 frcs. for women. The amount of
the annual old age pension is:
Men
Women
At the beginning of the 66th year
180 frcs.
140 frcs.
At the beginning of the 67th year
210 frcs.
160 frcs.
At the beginning of the 68th year
240 frcs.
180 frcs.
At the beginning of the 68th year
270 frcs.
210 frcs.
At the beginning of the 70th year and upward
300 frcs.
250 frcs.
A claim to a pension is considered lapsed if the insured person
takes up his residence abroad after he had began to draw
his annuity; in this case the person concerned may demand the
reimbursement, without interest, of the contributions he had
paid. The insurance is administered through the State Old
Age and Invalidity Institution. Special provisions regulate
voluntary insurance, to which persons of from one to 17 years
of age may be admitted.[292]
317There are also in Switzerland a large number of special
government funds with definitely restricted membership, such
as the employés of the federal railways and of the postoffice
department. Membership in these funds is made compulsory.
The contributions are borne jointly by the insured persons and
the federal government. The plan suggested by a recent Commission
of experts for a Federal Compulsory old age and invalidity
insurance system has been discussed in the preceding
chapter.
318
In 1815, the Legislature of the Territory of Alaska passed
an Act providing for the payment of pensions to aged persons.
Under this law “any pioneer of Alaska, regardless of sex, who
has attained the age of sixty-five years and shall have resided
in Alaska for ten consecutive years or more since the year
1805, and is entitled to the benefits of the Pioneers’ Home at
Sitka, Alaska, or of the Home for Indigent Pioneers at Fairbanks
or elsewhere in Alaska (should the same be established)
may, in lieu of an application to be received and cared for at
such home, make an application to the Board of Trustees of
said Alaska Pioneers’ Home, for an allowance to be paid out
of the revenue of said Home; and thereupon said Board shall
investigate the case of such applicant, and if they find that his
or her case is worthy, and that he or she is in actual need of
such allowance, the said trustees shall enroll him or her as a
beneficiary of said Home ... and in conformity therewith, an
allowance shall be paid for his or her use.... Provided that
if any person pensioned under the provisions of this act, shall
be admitted to the Alaska Pioneers’ Home or other Territorial
Institutions, any pension granted hereunder shall be suspended
during the time such person shall be an inmate of any such Territorial
Institution, nor shall any pension be paid to any person
who has been absent from the Territory of Alaska for a
period not to exceed one year.”
The original bill provided for allowances not to exceed
319$12.50 per month in any case. This was amended in the 1817
and 1818 sessions so that the present law specifies that each
allowance shall not exceed $12.50 per month for men and
$25.00 per month for women as the Board of Trustees in their
discretion shall allow “having regard to the necessities of the
applicant.” Each allowance is paid quarter-yearly. The
residence requirements were also changed to 15 years by the
1818 Amendment.
The law forbids the granting of allowances to any person
who absents himself from the Territory of Alaska for a period
exceeding one year unless with written permission of the Board.
In case of lack of revenue and when allowance installments are
not paid, the amended Act stipulates that “it shall remain an
obligation of the Territory of Alaska to the beneficiary, the
arrears of which shall be paid as soon as funds shall be available.”
It is also provided that the applicant for assistance
“in consideration of the receipt of the benefit of this Act,
agrees that all property of which he or she is possessed or
seized, shall, after his or her death, vest in and become the
property of the Territory of Alaska.”
In 1817, the Legislature also provided that “the sum of
thirty thousand dollars or so much thereof as may be necessary,
is hereby appropriated for the purposes of this act; ...
provided that the Board of Trustees shall not grant allowances
calling for an expenditure in excess of fifteen thousand dollars
in any one year; and further provided, that any excess fund
not issued the first year shall be available for use the following
year.”
The first attempt to establish a non-contributory insurance
system in the United States was made in the State of Arizona
in 1814. By means of the initiative petition and a popular
vote of 25,827 in favour and 12,384 against, legislation
was enacted in that year providing for old age pension
320grants. The pensions were to be given to all needy citizens
of the United States who have been residents of the
State of Arizona for at least five years prior to their application.
Pensions were to begin at 60 years of age. The amount
of the pension was set at $15 per month and was to be given
so long as the pensioner continued to reside in the State. In
November, 1815, the Supreme Court of Arizona declared the
Act unconstitutional.
The separate Australian States of New South Wales, Queensland,
and Victoria had established old age pension systems prior
to 1808. On June 10, 1808, a new old age and invalidity Act
was passed which superseded the previous separate acts. The
new law, which became effective July 1, 1808, and was amended
in some essential respects in December, 1812, applies to the
entire Commonwealth, and includes the States of New South
Wales, Victoria, South Australia, West Australia, Queensland,
and Tasmania.
The Australian law grants pensions to all males over 65
years of age and to all females over the age of 60. In order
to receive a pension a person must have resided in Australia for
at least 25 years. In addition, the pensioner must also be of
good character and not have been imprisoned for four or
more months within five years immediately preceding the pensionable
age. No pensions are given to persons who are wife-deserters,
drunkards, etc. Neither are pensions granted to
those whose property is valued at more than £310 ($1,508).
Excluded from the pension grants are also Asiatics or aboriginal
natives of Australia, Africa, New Zealand, or the Islands
of the Pacific.
The Australian Act also provides for an invalidity pension
in addition to the old age pension. The former is payable
to any person above 16 years of age, who is permanently
incapacitated for work, and has resided in Australia for at
321least five years. The applicant for an invalidity pension must
have no claim upon an employer for accident compensation
and be without property or income in excess of the pension
amount. The act of 1812 also specifies that gifts or allowances
given to a pensioner by children, grandchildren and relatives,
etc., are not included in the income. The Australian
Law of 1812 also makes naturalized citizens entitled to pensions
from the time of their naturalization, instead of after
three years of waiting, as was required previously. The law
stipulates that permanently incapacitated persons include the
permanently blind. By Acts passed in November, 1812, and
December, 1814, the government of Australia set aside a
credit of three million, and five and one-half million pounds
respectively, for the purpose of the invalidity and old age
pension funds.
The amount of the pension is not fixed. The law requires
that, the amount of pension shall be “at such rate as, having
regard to all circumstances of the case, the commission which
determines the pension claim deems reasonable and sufficient.”
The pension must not exceed, however, £26 ($127) per year.
Nor may the pension be of such amount as to bring the pensioner’s
total income above £52 ($250) per year. In case
the pensioner has property, the pension is reduced to the
extent of one pound ($4.87) for every ten pounds ($48.70)
of the net property exceeding 50 pounds ($243) exclusive
of the home, or above £100 ($487) including the home.
When both husband and wife are pensioners, deduction in case
of each of them is one pound for every ten pounds of net
property above 25 pounds.
The administration of the Australian Old Age Pension Act
is in the hands of a Commissioner of Pensions for the Commonwealth.
The Commissioner is assisted by a deputy commissioner
in each state. Each state is further divided into
districts, each of which is placed in charge of a registrar.
The latter’s duties are to receive and investigate pension
322claims and in general to carry out the provisions of the law.
The Pension Commissioner and his deputies are empowered
to summon witnesses, receive evidence on oath and to require
the production of books and documents. The district registrar
after proper investigation makes a recommendation to a
local magistrate who makes a further recommendation,
whereupon the application is transmitted to the deputy Commissioner.
The pension certificate is then issued either by the
deputy or Commonwealth Commissioner.
The number of pensioners in Australia has been increasing
steadily; the following figures show the continuous rise:
Years
Number of Old Age and Invalidity Pensioners
Amounts Paid in Pensions
1808
60,432
1810
65,482
$7,286,007.78
1811
82,853
8,082,841.17
1812
88,834
10,452,333.44
1813
86,682
11,138,507.57
1814
104,645
12,544,377.68
1815
111,308
13,158,167.58
1816
115,222
13,815,621.36
1817
120,453
The cost of administering these pensions rose from
$180,752.44 in 1810 to $216,055.27 in 1816. This amounted
to $12.06 per 100 pounds distributed in 1810, and decreased
to $7.48 per 100 pounds in 1816. The average fortnightly
pension amounted to $4.64 in 1810 and $4.70 in 1816. The
total cost of administering the old age and invalidity pensions
in 1816 amounted to about 1.5 per cent. of the total money
actually paid in pensions. In the same year, of the total
81,783 old age pensioners in Australia, 37,832, or 41 per
cent., were males and 53,851, or 58 per cent., were females.
Denmark led the world in instituting a non-contributory
or straight pension system for the aged, just as Germany was
323the pioneer in establishing compulsory insurance. Old age
pensions were established in Denmark as early as 1881. It
was the purpose of the Danish system to provide respectable
old persons with some assistance without their becoming
paupers. The public authorities are required to help anyone
so long as he cannot provide for himself or for his dependents.
According to the Danish law, the age when one may become
entitled to a pension is set at 60 years. The conditions of
eligibility are many and rigorous. The claimant to a pension
must prove that he is unable to provide the necessities
of life for himself or his dependents. No pensions are
given to applicants who have ever been convicted of a crime,
unless subsequently restored to civil rights. The claimant
must also not have squandered his means. He must not have
received poor relief, except medical aid, during the five years
prior to his application for a pension. A pensioner must
also be a Danish subject and must have resided at least ten
years in a fixed locality prior to application.
The amount of the pension is not specified in the Act. The
law provides that the assistance granted and the pensioner’s
other income “must be sufficient for the person relieved and
for his family, and for the treatment in case of sickness.”
What is a sufficiency is decided by the local authorities. In
considering the total income no account is taken of any income
amounting to less than 100 kroner ($26.80) per year.
The nature of the relief given may consist either of money or
supplies, such as food, fuel and rent. Usually money grants
are given in the cities, while necessary goods are given in the
rural sections. Pensioners who are unable to care for themselves,
are cared for in special homes, which are in the form of
detached cottages, or in single large institutions. During
the years 1811–12 three per cent. of the pensioners were cared
for in these homes.
The pension is given to the head of the family, treating the
family as a unit, and is larger for heads of families than for
324individuals. In determining the amount of the pension, the
former social conditions and manner of living are taken into
consideration. Poor relief granted to the wife in the past
is considered as poor relief granted to the husband. Pensions
are continued until the conditions under which they were
granted have changed.
The contributions to the old age relief fund are made both
by the State and the communes in equal parts. The pensions
are administered by the municipal and communal authorities
who employ well trained men for that purpose. The entire
system is under the supervision of the Minister of the Interior,
to whom all appeals from local authorities are taken.
As in Australia and other countries, the number of pensioners
has increased steadily since the inauguration of the
system. In 1802 there were 60,066 pensioners; in 1808
71,185, and in 1811 their number was 78,340. Of the
78,340 pensioners in 1811, 16,710 or 21 per cent. were heads
of families; 20,085 or 25 per cent. were dependents; 8,356
or 12 per cent. were single men, and 33,034 or 42 per cent.
were single women. The cost of the pensions had increased
since the beginning of the system enormously. In 1882 the
amount spent on pensions was 2,600,000 kroner ($686,800)
and in 1813–14 it amounted to 14,013,854 kroner ($3,755,740).
The problem of the government providing some form of assistance
for the aged poor was in the foreground for half a century
in England. The question assumed a definite shape and
attracted an especially great deal of attention in the early
nineties of the last century, through Mr. Charles Booth’s investigations
into the causes of pauperism in old age. The
evils connected with the English Poor Law System were generally
known and an improvement of the conditions was desired
by all. An attempt to relieve the problem of aged dependency
325by means of voluntary savings and insurance,
through the postoffices, failed as in other countries. A number
of Royal Commissions and departmental committees to investigate
and to consider alterations in the system of English
Poor Law Relief were appointed during the two decades that
elapsed between Booth’s investigations and the adoption of
an old age pension plan. The deliberations and reports of
these commissions and departmental committees served to
focus public opinion on the problem of the aged poor. Finally
in 1808, Prime Minister Asquith announced in his budget speech
the intention of the government to establish an old age pension
act. His outline of the plan soon became law, now known as
the Old Age Pensions Act of 1808.
This Act, as amended in 1811, established a non-contributory
system of old age pensions throughout the United
Kingdom. Pensions, under this law, are granted to all men
and women, married or single, who have attained their 70th
year. The conditions required in the original law for the receipt
of a pension included the following: that the claimant
has resided in the United Kingdom for at least 20 years prior
to his application. That the applicant is a British subject.
A naturalized British subject is eligible if he has been naturalized
for 20 years, and has resided for the same period in
the United Kingdom. Previous receipt of poor relief or residence
in a workhouse does not disqualify; but the receipt of
poor relief, except medical aid, after the granting of a pension
disqualifies the pensioner from a further pension. Paupers
arriving at the age of 70 may, if they choose, give up their
outdoor relief or workhouse residence and receive an old age
pension instead. The act also specifies that a pensioner must
be so far of good character as not to have been a prisoner
during the preceding ten years, and not to have habitually
failed to work so that his wife and children became dependent
on public funds. The act also disqualifies from a pension
habitual drunkards, persons actually in prison or under detention
326as lunatics, as well as inmates of institutions, where the
board and lodging amounts to an income above the pensionable
limit. The property qualifications, as provided in the original
act, limited the claimant’s income to £31, 10s. (normally $153)
per annum.
The pension amounts vary in accordance with the total income
of the pensioner. The original act provided a maximum
pension amount of 5s. (normally $1.22) per week. The pensions
were paid as follows:
£.
S.
D.
Rate of Pension
When the yearly income did not exceed
21
0
0s.
5s.
When the yearly income did exceed £21 0s. 0d. and did not exceed
23
12
6s.
4s.
When the yearly income did exceed £23 12s. 6d. and did not exceed
26
5
0
3s.
When the yearly income exceeds £28 5s. and does not exceed
28
17
6
2s.
When the yearly income exceeds £28 17s. 6d. and does not exceed
31
10
0
1s.
When the yearly income exceeds £31 10s. 0d
Nil.
Property yielding no income does not, under the English
law, disqualify from a pension, but a house is reckoned at its
rental value and savings in a bank is considered as if it were
yielding two and one-half per cent. interest. The incomes of
husband and wife are added together and each is considered
as possessing half the total. Regular allowances, gifts, etc.,
from friends, relatives, or charity organizations are included
in the income. Pensions are paid to both husband and wife.
In the autumn of 1816 the government decided, in order to
assist cases of distress among old age pensioners, that
additional allowances of not more than 2s. 6d. a week should
be paid to pensioners who were suffering “special hardship”
through the war from the high prices of food and other economic
conditions. Additional payments began in August, 1817.
The additional allowances were not granted to inmates of infirmaries
or institutions of the poor. The allowances were
decreased if the pensioner’s income increased and vice versa.
327The extra pensions were originally intended to be payable
only during the continuance of the war.
Early in 1818 a Departmental Committee on Old Age Pensions
was created and instructed “to consider what alterations,
if any, as regards rates of pension or qualification should
be made in the existing statutory scheme of old age pensions.”
This committee held many hearings, studied the different
phases of the pension law in England and abroad, and finally
made the following recommendations:[293]
(1) Amount of Pension: “After considering the matter
with care,” the committee declared, “we recommend that the
pension should be increased to 10s. a week permanently as
against the actual 7s. 6d. of today, the additional allowance
of 2s. 6d. being absorbed in the new pension. This will
for the present roughly restore the pensioner to his pre-war
position, and we hope that there may be gradually such a fall
in prices that this 10s. will ultimately represent a substantial
increase in the value of the original pension.”
(2) Income Qualification: “We have been insistently
forced to advocate that the means limit be abolished altogether,
and that the old age pension be given to all citizens at
the age of 70. We are of the opinion that no other course
will remove the very serious objections to the present system.”
(3) Age of Pension: “The qualifying age shall remain at
70 pending inquiry as to the possibility of extending the scope
of the Insurance Acts.” The committee further declared:
“Our inquiries have indeed shown that such provision is wholly
inadequate. We are informed that only 23 per cent. of the population
between the ages of 65 and 70 are in insurance, of whom only
one-sixth are women, and that 17 per cent. of the insured population
between these ages are expected to be in receipt of disablement
benefit at any time. These figures suggest that there must be a
large mass of invalidity, especially among women in the years immediately
preceding the pension age, for which at present no satisfactory
328provision is made. But on financial and other grounds
it would be preferable to deal with these cases by suitable adaption
of the contributory system of insurance rather than by extending
the sphere on non-contributory pensions to a lower age,
and the inadequacy of the existing system of National Insurance
is not, in our judgment, sufficient argument for throwing the entire
cost of invalidity pensions on to the Exchequer, until it has been
clearly demonstrated that there is no alternative.
“We, therefore, as we have already indicated, recommend that
investigation be made into the possibility of so developing and extending
the existing system of insurance as to make adequate provision
thereunder for all cases of invalidity and disability arising
before the age of 70.
“Accordingly, we do not in this report and at this time recommend
a reduction of age, though we appreciate the facts which
lead to requests for this reduction. They disclose a state of things
which cannot be left as it is. There is a real problem, and we
feel bound to add that unless it can be met in connection with
National Insurance and met adequately, particularly in the case of
women, which seems to us the most pressing, some development of
the pension system or some substantial reduction in the pension age
will become imperative.
(4) “Outdoor relief, or home assistance should not be disqualification
for the receipt of pension. Pensions should not be
paid to inmates of public institutions for more than three
months.
(5) “Aliens should become eligible for pensions 10 years
after naturalization if they have been residing in the United
Kingdom for at least 20 years, and the possibility of reciprocal
international agreements should be considered. British-born
wives of aliens should be eligible for pensions.
(6) “The term of residence required to qualify for pension
should be 12 years after reaching the age of 50. Reciprocal
arrangements with regard to residence within the British Empire
are suggested.
329(7) “Disqualification for any period following a term of
imprisonment should be abolished save in the case of habitual
inebriates.
(8) “The ‘failure to work’ disqualification should be abandoned.”
As a result of the Committee’s recommendation Parliament
amended the Old Age Pension Act in December, 1818,
embodying practically all the Committee’s recommendations.
The amended act became operative Jan. 2, 1820.
In accordance with the amended Act, the maximum pension
was increased to 10s. per week. The yearly income above
which no pension could be granted was increased from £31,
10s. to £48, 17s. The provision which disqualified a recipient
of poor relief from pensions was abandoned. This
was done because it was believed that the latter was an artificial
disqualification and led to inadequate standards of living.
The condition as to residence was reduced to 10 years and
changes were also made in the qualifications of former prisoners,
the status of wives of aliens, etc.
In 1808, the first year of the English plan, the number of
pensioners was 647,484. This increased to 887,238 at the
close of the fiscal year 1814–15. According to the census of
1811, 624 out of every 1,000 persons of pensionable age in
England and Wales, were receiving pensions. In other words,
only two of every five persons 70 years of age and over, in
England and Wales had private annual incomes of their own,
amounting to at least £31 ($153). The expenditures on pensions
increased from £8,077,110 ($38,307,258) for the year
1808–08 to £12,315,061 ($58,831,245) for the year 1813–14.
In 1818, the amount reached nearly £8,000,000 (normally
about $80,000,000).
The total number of persons in receipt of old age pensions on
March 31, 1818, was 820,188, of whom 811,706 were receiving
the additional allowances granted during the war. The number
330of pensioners from the first year of operation to the present
were as follows:
Table showing the number of Pensions Payable on the Last Friday in March.
Year
England
Wales
Scotland
Ireland
Total
1808
368,037
24,663
70,284
183,500
647,484
1810
414,108
27,381
76,888
180,874
688,352
1811
575,788
38,084
81,805
201,783
807,461
1812
602,441
40,083
84,318
205,317
842,160
1813
626,753
41,880
86,238
203,036
867,821
1814
642,161
42,474
87,284
202,202
884,131
1815
648,868
42,537
86,885
188,830
887,238
1816
647,108
42,001
85,277
183,725
878,112
1817
628,787
40,606
81,656
185,731
847,780
1818
630,808
40,800
80,500
180,868
843,077
1818
618,845
38,873
87,681
173,688
820,188
The following table also shows the amounts paid in pensions
during each year since the adoption of the plan:
Year
Amount £
1808
2,026,385
1810
8,468,128
1811
8,683,442
1812
11,714,434
1813
12,138,108
1814
12,375,561
1815
12,560,565
1816
12,606,678
1817
13,732,207
1818
16,861,018
1818
17,728,000
The old age pension set is administered by the Local Government
Board which operates through local pension commissions,
and paid officers. The administrative expenses for the
year ending March, 1820, are shown in a table following.
Great Britain’s liberality in providing pensions for the
aged was explained by Lloyd George in 1817, in reply to a deputation
from the Parliamentary Commission of the Scottish
Trade Union Congress.[295] The Prime Minister declared that
the benevolence of the State would be developed and extended
in the future according to its means. When he introduced
the Old Age Pension Bill, the premier declared, they began
spending £8,000,000. The £8,000,000 grew to between £12,000,000
and £13,000,000, at the beginning of the war, and now
the £13,000,000 had grown into something like £18,000,000.
They now had 7s. 6d. for the old age pensioner, and they had
5s. for those who were incapacitated. That had made a
difference which it was very difficult to reckon or to portray in
words, in the lives of hundreds of thousands of old people who
deserved well of the community. “He hoped the State would
go on extending and recognizing the obligations it owed to
these people. He thought the worker in any rank of life ought
to be able to claim as a matter of right from the community,
the same security as the civil servant against indigence and
squalor and misery, when his strength had given out. The
war had opened people’s eyes. The sort of individual conflict
which constituted almost the life of the nation before the war
was merging into a sense of community and fraternity which
had come from common trials and burdens and sorrows. He
thought that after the war the country, shouldering the heavy
burden of the war, would be in a better temper and a better
332frame of mind to consider every cause which was righteous, and
the cause of the blind, the afflicted, the aged and the miserable
amongst us were of that kind.”
Bearing the above in mind it is significant to note that as
this book goes to press, the newspapers report that at the
National Old Age Pension conference held recently in Newcastle,
England, letters were read from thirty-two members of
Parliament favouring universal pensions.
A non-contributory old age pension system was established
in New Zealand in 1888. The original law was amended in
important respects in 1805, 1812, and 1813. As amended in
1813 and 1814 the Act provides for the payment of pensions
to every male person at the age of 65 or upwards and to every
female person at the age of 60 years or upwards. Pensions are
granted also to males at the age of 60 years and females at
the age of 55 years who have two or more children under the
age of 14, dependent upon them for support.
The eligibility qualifications for a pension are rigorous.
Pensions are granted only to those who have fulfilled the following
requirements: The pensioner must have resided in
New Zealand continuously for not less than 25 years immediately
preceding his claim. Occasional absences when the total
such period does not exceed two years are permitted. The
claimant must not have been imprisoned for four months, or on
four occasions, during the period of 12 years immediately preceding
the date of his claim, nor imprisoned for a term of five
years during the last 25 years. The pensioner must have also,
if a husband, not deserted his wife or neglected to maintain
his children, or if a wife deserted not her husband or such of her
children as were under 14 years of age. The claimant must in
addition be of good moral character and one who has for at
least the last year led a sober and reputable life. The law
333also forbids granting pensions to those whose yearly income
exceeds £60 ($282) and those whose accumulated property
amounts to over £260 ($1,265). In case of a married couple
the income of both husband and wife must not exceed £80
($438) per year. As in Australia, pensions are not given to
Asiatics, Maoris and aboriginal natives.
The amount of the annual pension is set at £26 ($127).
One pound from the pension is deducted for every one pound
of income over £34 ($165) and for every £10 ($48.70) of net
property in excess of £50 ($243). Where the pensioner is a
woman under 65 years of age the amount of the pension shall
be further diminished by one pound for every year or part of a
year by which the age of the applicant is less than 65 years.
An additional pension, the amount of which is left at the discretion
of the magistrate but which may not exceed £13 per annum
may be given to pensioners when young children are dependent
upon him or her.
Personal property is not taken into consideration in determining
the amount of accumulated property. It is also specified
that a pensioner may retain a home to the value of £650
($3,163). Provisions are made for the transfer of such property
to the Public Trustees. The pensioner, or his survivors
if entitled to a pension, are permitted to reside in the said property.
At the death of the pensioner the Public Trustee sells
the property and deducts out of the proceeds the total amount
paid in pensions since the transfer of such property together
with four per cent. interest.
In case the pensioner is married and living with his wife the
net capital value of all the accumulated property of each is
deemed half the total of both. The yearly income of each is
also deemed half the total annual incomes of both. The total
pension granted to both husband and wife living together must
not exceed, together with the total incomes of both, £100 for the
year. The law also provides for institutional care for those
who are unable to maintain homes for themselves.
334As in Australia, the pension system is administered by a
Commissioner of Pensions and district registrars. The colony
is divided into districts for this purpose. Pensions are awarded
for one year only, but may be renewed.
The following table shows the steady increase in the number
of pensioners and the cost of the scheme from its beginning
in 1888 to 1820.
Number of Pensioners and Amounts spent in New Zealand
each year since 1888 to 1820:
Year
No. of Pensioners
Amount Spent
1888
7,443
£3,124
1800
11,285
157,342
1801
12,405
187,282
1802
12,776
207,468
1803
12,481
210,140
1804
11,826
203,164
1805
11,770
185,475
1806
12,582
254,367
1807
13,257
314,184
1808
13,568
325,188
1808
14,386
336,780
1810
15,320
362,486
1811
16,020
383,383
1812
16,648
406,256
1813
16,508
415,761
1814
18,050
416,776
1815
18,352
460,814
1816
18,804
478,338
1817
1818
18,860
1818
18,872
482,458
1820
18,883
475,868
From 1888 to 1820, a total of 67,275 persons applied for
old age pensions in New Zealand. Grants were made to
54,062 persons. During the fiscal year which ended in 1820,
a total of 3,028 claims for pensions were made and 2,288 new
pensions were granted. In the same year 2,168 pensions were
cancelled either because of death of pensioner or for other
reasons, leaving a net increase of 121 pensioners. The average
pension during the last fiscal year amounted to £23, 12s.
The percentage of European pensioners to the total
European population was 1.6 in 1820. The total amount
335disbursed on old age pensions since the beginning of the
pension law up to 1820 was £7,828,788.[296]
On May 15, 1818, an old age pension law went into effect in
Uruguay. The act provides for the pensioning of all persons
upon reaching the age of 60 years, or other persons who have
become totally incapacitated and are indigent, regardless of
their age. Foreigners or naturalized citizens who have resided
continuously in Uruguay for 15 years are entitled to pensions.
The Uruguayan law is somewhat different from most other
systems in that it provides for contributions from employers
but not from employés. The fund for the payment of these
pensions is made up from the following: (1) A monthly tax of
20 centesimos (20.68 cents) payable by the employers for
each person employed by them: (2) A surtax upon real estate
valued at 200,000 pesos ($206,840) and over. The surtax
ranges from 1.05 pesos ($1.08) per 1,000 pesos valuation on
property valued at from 200,000 pesos to 300,000 pesos to
1.30 pesos ($1.34) per 1,000 pesos on property valued at
700,000 pesos and over. (3) A tax on playing cards of 20
centesimos (20.68 cents) if imported and ten centesimos
(10.34 cents) if manufactured within the country. (4) An
increase of twelve centesimos per liter (11.7 cents per
quart) of the present tax on imported liquors. (5) An
internal tax of 60 centesimos per liter (58.7 cents per quart)
on imported alcohol and domestic alcohol not destined for
denaturation. (6) The tax on imported brandies was
increased by 13 centesimos (13.44 cents).
The annual pension is to be not less than 86 pesos ($88.28)
and may be paid in cash or in supplies. In case a pensioner
is in receipt of any annuities or allowances in excess of ten
336pesos ($10.34) the pension granted under this Act is reduced
to 50 per cent of that sum in excess of ten pesos.[297]
On September 30th, 1818, the National Congress of Uruguay
passed another act providing for pensions for public service
employés which include the railroad, telegraph, tramway, telephone
and water and gas distributing companies.
The full pension is paid after 30 years of service, but a
right to a proportional pension is acquired after ten years of
service, continuous or not. Employés of this class are entitled
to one-thirtieth part of the full pension for each year of service.
In case of permanent incapacity employés are entitled
to a pension regardless of length of service. The pension
ranges in accordance with the average wages for the last five
years of service. Pensions are also paid to dependents and
survivors of employés.[298]
APPENDIX — (A) BILL INTRODUCED BY SENATOR McNARY IN THE SENATE OF THE UNITED STATES August 15, 1818. A BILL To provide old-age pensions. — (B) BILL PRESENTED BY THE PENNSYLVANIA OLD AGE PENSION COMMISSION TO THE 1821 PENNSYLVANIA STATE LEGISLATURE, AND WHICH IN ITS MAIN PROVISIONS HAS, IN EFFECT, THE ENDORSEMENT OF THE SOCIAL INSURANCE COMMITTEE OF THE AMERICAN ASSOCIATION FOR LABOR LEGISLATION — AN ACT — Administration — Allowance — Qualifications of Claimants — Property Qualifications — Calculation of Income — How Administered — Fines Punishment and Criminal Procedure — Funds and Expenses — Annual Report Hearings Etc
337
339
Be it enacted by the Senate and House of Representatives
of the United States of America in Congress assembled,
That every person in whose case the conditions laid down
by this Act for the receipt of an old-age pension are fulfilled
shall be entitled to receive such a pension as long as those
conditions continue to be fulfilled, and the receipt of an old-age
pension under this Act shall not deprive the pensioner
of any franchise, right, or privilege, or subject him to any
disability.
Sec 2. That the conditions for the receipt of an old-age
pension by any person shall be as follows:
(a) The person must have attained the age of sixty-five
years.
(b) The person must have been a citizen of the United
States for the twenty years next preceding the application
for a pension under this Act.
(c) The person must not have had an income from any
source, exclusive of the pension herein provided for, for the
twelve months next preceding his application, averaging $6
per week.
Sec. 3. That a person shall be disqualified for receiving or
340continuing to receive an old-age pension under this
withstanding the fulfillment of the above conditions—
(a) If before he becomes entitled to a pension he has habitually
failed to work according to his ability, opportunity, or
need for the maintenance and support of himself and those
legally dependent on him: Provided, That a person shall not
be disqualified under this paragraph if he has continuously
for the ten years previous to attaining the age of fifty-five,
by means of payments to fraternal, benefit, or other societies,
or trades-unions, or other approved steps, made such provisions
against old age, sickness, infirmity, or want, or loss of
employment, as may be recognized as proper provision for
the purpose; and any such provision, when made by the husband,
in the case of a married couple living together, shall, as
respects any right of the wife to a pension, be treated as
having been made by the wife as well as by the husband.
(b) While he is being maintained in any place as a pauper
or lunatic.
(c) While he is detained in prison after conviction for a
felony, and for a further period of ten years after the date
of release from imprisonment for such cause.
Sec. 4. That every person fulfilling the required conditions
shall be placed upon the pension roll of the United States
and be entitled to receive until death a pension from the
United States Government provided by an annual appropriation
from Congress. Such pension shall be graded according
to the following schedule:
When the average weekly income of the pensioner as calculated
under this Act does not exceed $6, $4 per week;
exceeds $6, but does not exceed $7, $3 per week; exceeds $7,
but does not exceed $8, $2 per week; exceeds $8, but does not
exceed $8, $1 per week.
Sec. 5. That in calculating the income of a person for
the purpose of this Act, account shall be taken of—
(a) The income which that person may reasonably expect
341to receive during the succeeding year in cash, excluding any
sums receivable on account of an old-age pension under this
Act, that income, in the absence of other means for ascertaining
the same, being taken to be the income actually received
during the preceding year.
(b) The yearly value of any advantage accruing to that
person from the ownership or use of any property which is
personally used or enjoyed by him.
(c) The yearly income which might be expected to be derived
from any property belonging to that person which,
though capable of investment or profitable use, is not so invested
or profitably used.
(d) The yearly value of any benefit or privilege enjoyed
by that person.
Sec. 6. That in calculating the income of a person being
one of a married couple living together, the income shall not
in any case be taken to be less than one-half the total income
of the couple: Provided, That when both husband and wife
are pensioners, except where they are living apart pursuant
to any decree, judgment, order, or deed of separation, the
rate of the pension shall be three-fourths of the rates given
in the above schedule.
Sec. 7. That if it appears that any person has directly
or indirectly deprived himself of any income or property in
order to qualify himself for the receipt of an old-age pension,
or for the receipt of an old-age pension at a higher rate than
that to which he would otherwise be entitled under this Act,
that income or the yearly value of that property shall be
taken to be part of the income of that person.
Sec. 8. That any assignment of or charge on and every
agreement to assign or charge an old-age pension under this
Act shall be void and on the bankruptcy of a person entitled
to an old-age pension the pension shall not pass to any
trustee or other person acting on behalf of the creditors.
Sec. 8 That the said pension shall be paid in thirteen
342equal installments in each year in advance. It shall begin
on the date the claim is filed, and the arrears from that time
to the time of allowance shall if the claimant be then living,
but not otherwise, be paid in a lump sum.
Sec. 10. That the said pension may be increased or
decreased every twelve months, whenever the pensioner’s income
increases or decreases, according to the terms of the
schedule.
Sec. 11. That wherever in this Act the masculine pronoun
is used it shall be held to include the feminine pronoun
also.
Sec. 12. That all claims for old age pensions under this
Act shall be filed with the Department of the Interior, together
with affidavits containing such statements as may be
prescribed by the Secretary of the Interior, who shall make
such rules and regulations as may be necessary to carry out
the provisions of this Act.
Providing for the protection and assistance of aged persons
under certain conditions in the Commonwealth of Pennsylvania
and prescribing penalties for violation of its provisions
and making an appropriation therefor
Section 1 Be it enacted by the Senate and House of Representatives
of the Commonwealth of Pennsylvania in General
Assembly met and it is hereby enacted by the authority of
the same That beginning January first one thousand nine
343hundred and twenty-three subject to the provisions and under
the restrictions imposed by this act every person (man or
woman married or single) shall while residing in the Commonwealth
of Pennsylvania be entitled to assistance in old age
Section 2 (a) The central authority shall be vested with
a State Old Age Assistance Board hereinafter called State
Board composed of three (3) citizens of the State who shall
be appointed by the Governor for a term of four years except
that of the members first appointed one shall be appointed
for a term of two years, one for a term of three years and
one for a term of four years. Each member of the Board shall
receive in addition to the necessary expenses incurred in the
performance of their duties ten dollars per diem while actually
engaged in the business of the Board Vacancies shall
be filled in the same way as the original appointment was
made
(b) The State Board shall appoint a State Old Age
Assistance Superintendent who shall be a person having had
experience and training in the problems of organized relief
who shall be familiar with the social and economic conditions
of the State of Pennsylvania and who shall in general be
qualified by training and experience for this work
(c) The State Board shall fix the salary of the Superintendent
which shall not exceed seven thousand five hundred
dollars ($7,500) per annum and the Superintendent with
the approval of the State Board shall appoint the necessary
number of assistants and fix their salaries and duties
(d) There shall be in each county a County Old Age
Assistance Board hereinafter known as the County Board to
consist of three citizens of the county who shall be appointed
by the Governor with the approval of the State Board on the
recommendation of the County Commissioners except that of
the members first appointed one shall be appointed for a term
344of two years one for a term of three years and one for a term
of four years. Vacancies shall be filled in the same way as
the original appointment was made. The members of the Board
shall serve without pay except that necessary expenses incurred
while in the performance of their duties shall be paid
to them
(e) The State Board as well as the County Board shall
perform all the duties imposed upon them by this act and
the State Board shall have authority to make the rules and
regulations required to carry out the provisions of this act
(f) The County Board with the approval of the State
Board and State Superintendent may appoint one or more
local investigators who shall be trained and experienced in
the problems of organized charity at a salary for each not
to exceed two thousand five hundred dollars ($2,500) per
annum. The County Board or its investigator or investigators
shall investigate all cases properly brought before them and
the recommendations of the County Board shall be forwarded
to the State Board for its approval provided that in case of
complaint or grievance a rehearing may be had before the
State Board which decision shall be final provided further
that the claimant may again apply for assistance in the same
manner to the County Board one year after date of first
application
(g) The State Board and the County Boards shall be required
to meet at regular intervals of not less than two (2)
months and at such times as may be fixed by the rules of the
Boards
Section 3 (a) The amount of assistance shall be fixed by
the State Board with due regard to the conditions in each
case but in no case shall it exceed twenty-five dollars ($25)
per month
345
Section 4 Old Age assistance may be granted only to an
applicant who
(a) Has attained the age of sixty-five or upwards
(b) Is a citizen of the United States
(c) Resides in the State of Pennsylvania and has so resided
continuously for not less than fifteen years immediately
preceding the date of application for assistance Provided
That continuous residence in Pennsylvania shall not be deemed
to have been interrupted by occasional absence therefrom
where the total period of all such absence does not exceed
two years or in case the person has been absent from the
State while in the employ or service of the State or of the
United States and provided further that a person who resided
in the State of Pennsylvania forty (40) years at least
five (5) of which have been immediately preceding the date
of application shall be deemed qualified in respect to residence.
(d) Is not at the date of making application an inmate
of any prison jail or workhouse infirmary insane asylum
county or district poorhouse or any other public reform or
correctional institution
Section 5 (a) The income of the claimant from all sources
at the date of application for relief shall not exceed three hundred
dollars ($300) per annum and also the net capital value
of the accumulated property of such person or the accumulated
property of husband and wife together must not exceed
five thousand dollars inclusive of a homestead
(b) The claimant must not have deprived himself or herself
directly or indirectly of any property for the purpose
of qualifying for old age relief
(c) The aged person must have no child or any other person
responsible for the support of such person under the laws
346of the State of Pennsylvania adjudged by the assistance authorities
fully able financially to support the applicant
(d) At the death of the person so assisted or the last survivor
of a married couple the total amount of the assistance
since the first grant together with three percentum interest
shall be deducted and allowed by the proper courts out of the
proceeds of the property as a preferred claim against the
estate of the person so assisted and refunded to the State
Treasury to the credit of the Assistance Fund leaving the
balance for distributing among the lawful heirs in accordance
with the law provided that the State assistance authorities
may demand the assignment or transfer of such property to
the State Board upon the first grant of assistance The State
Board shall establish such rules and regulations regarding the
care transfer and sale of such property as it deems advisable
and also provide for the return of the balance of the claimant’s
property in its hands whenever assistance is withdrawn
or the claimant ceases to request it
Section 6 (a) The annual income of any property inclusive
of a homestead shall be computed at five per centum of its
determined value
(b) In ascertaining the claimant’s income and amount of
assistance his income for the last preceding year shall be
deemed his annual income and the property owned at the
end of that year as his accumulated property provided that
when the claimant shows to the satisfaction of the assistance
authorities the loss of personal income derived from personal
earnings it shall be deducted from the income of the preceding
year in considering the assistance grant
Section 7 (a) A claimant for an assistance grant under
347this act shall deliver his or her claim in writing to the County
Board of the county in which the claimant resides in the
manner and form prescribed by the State Board All statements
in the application shall be sworn to or affirmed by the
applicant setting forth that all facts are true and correct in
every material point
(b) After proper investigation a copy of the application
for old age assistance with the decision of the County Board
and recommendation of the amount of assistance if any and
the material reasons for such decision shall be promptly forwarded
to the State Board In case the State Board decides
against the grant or reduces its amount upon demand of the
claimant it shall set a date for a hearing before the County
Board which shall be attended by the State Superintendent
or his assistant with full powers of investigation The claimant
shall be notified sufficiently in advance of the date of the
hearing on which he may attend to support his claim whereupon
the recommendations of the Board with the report of
the Superintendent or his assistant shall be forwarded to the
State Board whose decision thereon shall be final
(c) For the purpose of such investigations the boards both
State and county shall have the power to compel by subpoena
issued by either board the attendance and testimony of
witnesses and the production of books and papers All witnesses
shall be examined on oath and any member of the State
or county boards may administer said oath
(d) In the investigation of any claim for old age assistance
and any renewal thereof the State board shall investigate and
determine all cases by such means and in such manner as it
deems proper
Section 8 (a) When the claim is established and the rate
of the first year’s grant is fixed the county board shall in the
manner prescribed certify the same to the State board which
shall issue the claimant an old age assistance certificate stating
348the amount of the monthly or quarterly payment and
which shall be good for one year
(b) An assistance certificate shall be required for each subsequent
year to be renewed or issued after satisfactory investigation
Section 8 (a) The assistance shall commence on the date
named in the old age assistance certificate which shall be the
first day of the month within which the certificate is issued
provided that in case of assistance granted the assistance certificate
shall be issued not later than three (3) months after
application has been made
(b) All installments shall be paid in monthly or quarterly
payments as the county board shall recommend the payments
to be made in such form and manner as may be prescribed by
the State board
Section 10 (a) If at any time during the currency of an
old age assistance certificate the recipient or the wife or husband
of the recipient becomes possessed of any property or
income in excess of the amount allowed by law in respect to
the amount of assistance granted the county board may on
inquiry and with the approval of the State Board either cancel
the assistance or vary the amount thereof during the
period of the certificate And it shall be the duty of the
recipient to immediately notify the county board of the receipt
and possession of any such property or income
(b) If on the death of any recipient of an old age assistance
grant it is found that he or she was possessed of property
in excess of the amount allowed by law in respect to the amount
of the assistance granted double the total amount of the relief
granted in excess of that to which the recipient was by law
entitled may be recovered by the State board as preferred
claim from the estate so found in excess The Attorney General
at the request of the State board shall take the necessary
proceedings to recover such claims and the amount recovered
shall be paid into the State Treasury
349Section 11 On the death of a recipient of old age assistance
the installment then accruing and such other reasonable
funeral expenses as necessary for the burial of such person
shall be paid to such persons as the county board directs
provided that these expenses do not exceed one hundred dollars
($100) and provided further that the estate of the deceased
is insufficient to defray these expenses
Section 12 (a) When an old age assistance recipient becomes
an inmate of any charitable or benevolent institution
the amount of assistance shall be paid to the governing authorities
of that institution and shall be applied toward defraying
the actual expenses of such person in such institution provided
that the State board has approved and is permitted freely
to visit and inspect said institution and provided further that
any surplus assistance moneys remaining after defraying such
cost shall be paid to the recipient It shall not be lawful however
for the authorities of any charitable institution receiving
public moneys to refuse admission as an inmate of such institution
or to refuse to grant relief on the grounds that the
person is an old age assistance recipient under this act
(b) During the continuance of the assistance no recipient
shall receive any other relief from the State or from any
political subdivision thereof except for medical and surgical
assistance
Section 13 All old age assistance grants shall be absolutely
inalienable by any assignment sale charge on execution or
otherwise and in case of bankruptcy the assistance shall not
pass through any trustee or other persons acting on behalf of
the creditors
Section 14 If at any time the State board has reason to
believe that any old age assistance certificate has been improperly
obtained it shall cause special inquiry to be made by
the county board and may suspend payment of any installment
350pending the inquiry It shall also notify the county
board of such suspension If on inquiry it appears that the
assistance certificate was improperly obtained it shall be cancelled
by the state board but if it appears that the certificate
was properly obtained the suspended installment shall be payable
in due course
Section 15 (a) Any person who by means of wilfully false
statement or representation obtains or attempts to obtain
(a) An assistance certificate not being justly entitled to
(b) An assistance of a larger amount than he is justly
entitled to
(c) By any means of personation or any other fraudulent
device whatsoever obtains or attempts to obtain payment of
any forfeited installment grant
(d) By wilfully false statement or representation he aids
or abets any person to obtain an old age assistance certificate
or any installment payable thereunder
(e) Aids and abets in buying or in any way disposing of
the property of an old age assistance recipient without the
consent of the State board shall be guilty of a misdemeanor
and upon conviction thereof shall be sentenced to pay a fine
not exceeding five hundred dollars ($500) and to undergo
imprisonment not exceeding three years or both in the discretion
of the court
Section 16 (a) Any person who violates any provision of
this act for which no penalty is specifically provided shall
be subject to a fine not exceeding five hundred dollars ($500)
and to undergo imprisonment not exceeding three years or
both in the discretion of the court
(b) Where an old age assistance recipient is convicted of
an offense under this section the assistance authorities may
cancel the assistance certificate in respect to the issue of
which the offense was committed
Section 17 If any recipient under this act is convicted
of any crime misdemeanor or felony or any other offense
351punishable by imprisonment for one month or any longer
period the county board shall direct that payments be not
made during such periods Furthermore if the recipient is
found incapable of taking care of his money or himself on
the testimony of at least three witnesses the county board may
direct the installment of his assistance be paid to any other
reputable person for his benefit or may recommend the suspension
of same to the State Board for such period as it
deems fit
Section 18 In case of forfeiture of an assistance certificate
the person whose assistance is so forfeited shall be disqualified
to make any application for a new assistance certificate
until the expiration of one year from the date of forfeiture
Section 18 The funds for the payment of old age assistance
shall be furnished by the Commonwealth of Pennsylvania
Section 20 (a) All expenses incurred by the State Board
in administration investigation and salaries shall be borne by
the State and a sum of $50,000 for the next two years is
hereby appropriated for this purpose
(b) All expenses incurred by the county boards in administration
investigations and salaries shall be paid by the county
treasurer from the moneys of the county
Section 21 Within ninety (80) days after the close of each
calendar year the State Board shall make a report for the
preceding year stating
(a) The total number of recipients
(b) The amount paid in each
(c) The total number of applications
(d) The number granted assistance the number denied and
352the number cancelled during that year and such other information
as the State Board may deem advisable
Section 22 All methods of procedure in hearings investigations
recording registration and accounting pertaining to
the old age assistance under this act shall be in accordance
with the rules and regulations as laid down from time to time
by the State Board
Section 23 Every assistance granted under the provisions
of this act shall be deemed to be granted and shall be held
subject to the provisions of any amending or repealing act
that may hereafter be passed and no recipient under this act
shall have any claim for compensation or otherwise by reason
of his assistance being affected in any way by any such amending
or repealing act
Section 24 Within ninety days of the signing of this act the
Governor shall appoint the members of the State Board
1. (F. L. Hoffman, “American Statistical Association Publications,”
March 1808, pp 368–8).
2. The reverence shown aged persons is clearly illustrated from the
following incident given by Dewey & Tufts in their “Ethics” (pp 17–18):
“A Chinese aided by his wife flogged his mother. The imperial order
not only commanded that the criminals should be put to death; it further
directed that the head of the clan should be put to death, that the
immediate neighbours each receive eighty blows and be sent into exile;
that the head or representatives of the graduates of the first degree (or
B. A.) among whom the male offender ranked should be flogged and exiled;
that the granduncle, the uncle, and two elder brothers should be put to
death; that the prefect and the rulers should for a time be deprived of
their rank; that on the face of the mother of the female offender four
Chinese characters expressive of neglect of duty toward her daughter
should be tattooed, and that she be exiled to a distant province; that the
father of the female offender, a bachelor of arts, should not be allowed
to take any higher literary degrees, and that he be flogged and exiled; that
the son of the offenders should receive another name, and that the lands of
the offenders for a time remain fallow.”
3. Rowntree, B. S. and B. Lasker. Unemployment, Macmillan 1810, p 38.
125. Report of the Tariff Board on Cotton Manufactures. 62nd Congress,
2nd Session, House of Document 643, Government Printing Office, 1812,
Vol. II, 637–651.
143. Thirty-Third Annual Report, Statistics of Manufactures, p 11, 1820.
144. War Time Changes in Wages, Sept, 1814, March 1818, National Industrial
Conference Board 1818.
145. The Cost of Living Among Wage-Earners, Lawrence, Massachusetts,
1818; National Industrial Conference Board, Boston.
146. Labour Review, April 1820, p 100–104; March 1820, p 33–36; Feb.
1820, p 106–113; May 1820, p 82–107; and June 1820, p 82–84.
147. Industrial Survey in Selected Industries in the United States in 1818,
Bulletin No 265, p 37–38, May 1820. United States Bureau of Labour
Statistics.
148. Women’s Wages Today, Feb. 1820. Consumer’s League of N. Y.
State & N. Y. City.
149. Current Facts, Jan. 1821, National Consumers’ League, New York.
167. The most recent figures as to what constitutes a minimum “health
and decency budget” for a family of five have just been made public by the
Labour Bureau, Inc., New York City. As a result of cost of living surveys
conducted in 1821 in New York City and Philadelphia, the above
bureau estimates the annual minimum standard necessary for a family
of five as $2,233.88 in New York City, and $2,338.20 in Philadelphia.
The bureau’s estimate is based on the “quantity budget” used by the
United States Bureau of Labour Statistics. They estimate that $688 a
year is needed for food, $388 for clothing, $443 for rent, $83 for light
and heat, $58 for household equipment and $650 for miscellaneous expenses.
“The family is allowed no expenditures for books and magazines,”
says the bureau’s statement, “only one daily paper is included. The doctor’s
bill cannot exceed $80 a year for the whole family, and the boy
of 12 can get but eight hair-cuts a year. The husband is allowed one-half
and the wife one-third of an overcoat each year. The only amusements
permitted are an occasional cheap movie show. No allowance is made
for a trip or vacation outside the city.”
169. Even in December, 1820, according to the bureau, the total cost of
living was six-tenths of one per cent. higher than in December, 1818, and
only 7.4 per cent. less than in June, 1820—the peak of high prices.
(Labour Review, Feb. 1821, p 61).
170. L. W. Squier, Old Age Dependency in the United States, pp 28–30
and 36.
190. G. R. Miller, Social Insurance in U. S. p 111.
191. According to the New York Times of April 22, 1821, W. Jett Lauck,
economist for the railway labour organizations, declared before the Railroad
Labour Board that “authoritative government reports state that
five million workers are idle, at least three million of them having been
without work throughout the winter. It costs these five million workers
nearly one billion dollars a month to supply their families with the barest
necessities of existence. This situation means acute distress to approximately
25,000,000 persons. The cost of maintaining these five million
families would absorb each month approximately one-fifth of the total
savings deposits of the country. The entire savings bank deposits of the
country could support them only five months, as they amount to only
$5,186,845,000.”
192. Report of the Comptroller of the Currency, vol. 2, p 807, 1820.
193. Abstract of Reports of Condition of National Banks No. 125, p 11,
Aug. 30, 1820, Treasury Department, Washington.
194. House Document No. 460, Sixty-sixth Congress 2nd Session.
195. Mabel Louise Nassau, Old Age Poverty in Greenwich Village, pp
16–17.
199. A recent inquiry addressed to corporations who have established
pension systems is of interest. Of 58 answers to the question “Have
your workers shown appreciation of benefits of pension system?” fifty-one
answered in the affirmative. To the question whether the pension
system has had a material effect in promoting efficiency, “particularly
in that it has eliminated their worries concerning their future,” 36 out
of 58 returns replied in the affirmative. Thirty-three out of 57 replies
also answered yes to the question, “Has your pension system increased
the average permanency of employment of your employés, i. e. has it
reduced labour turnover materially?” In regard to the questions whether
industrial pensions have decreased industrial unrest on the part of employés,
or prevented strikes, 20 of 44 replies stated that it did to a certain
extent, while 23 others declared that it did not.
200. Report on Industrial Pensions, The Merchants’ Association of New
York, New York, 1820.
201. Bulletin No. 212 U. S. Bureau of Labour Statistics, 1817, p 736.
219. On January 12, 1821 a Massachusetts joint legislative Committee in a
report on pensions submitted to the Legislature declared: “The contributory
system has proved to be a success in the case of those State employés
and teachers who have been brought into it. It places a reduced
financial burden on the State and provides through the employé’s contributions
a savings account which is payable to the employé or his estate in
case of his resignation or death; it fixes an age at which all must retire,
thus safeguarding the public service against inefficiency resulting from
superannuation; it establishes a co-operative partnership between the
employés and the public;—each shares in the management, each shares in
the expense and each derives benefit from the system.”
220. Paul Studensky, Teachers’ Pension Systems in the U.S. 1820.
260. In 1821 bills providing for old age pensions were introduced
following states: Illinois, Indiana, Iowa, Kentucky, Massachusetts,
Montana, New York, Ohio, Pennsylvania, Washington, and Wisconsin.
263. According to the latest information available, Belgium has apparently
abandoned its voluntary system and has adopted instead a straight pension
plan. The December, 1820, American Labour Legislation Review (page
230) states that on Aug. 20, 1820, a new old age pension law was enacted in
Belgium. “Persons born before 1858 upon reaching the age of 65 are to
receive an annual pension of from 600 to 720 francs. This amount will be
reduced if the claimant has an independent income, but certain sources of
income are exempt. The cost of the pensions is to be shared five-eighths
by the state, one-eighth by the province and two-eighths by the commune.”
264. Figures supplied by S. T. Bastedo, Superintendent, Canadian Government
Annuities.
285. The Labour Gazette, January 1820, p 10, London; Monthly Labour Review,
December 1818, pp 348–358.
286. Bulletin of International Labour office, Vol. 8, no. 7, p 310, 1814.
287. Report of a special inquiry relative to aged and dependent persons
in Mass., Boston, 1816, p 102.
288. Proposed scheme of National Social Insurance for Norway, by Nicholay
L. Bugge, Secretary in the Norwegian Ministry of Finance. (Manuscript
copy in the Library of the U. S. Bureau of Labour Statistics.)