Foreword
8
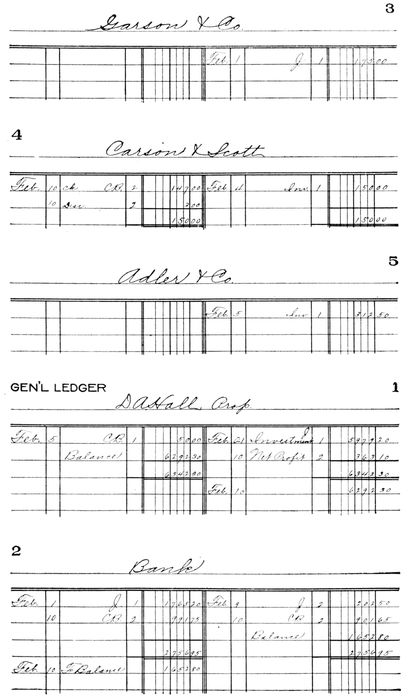
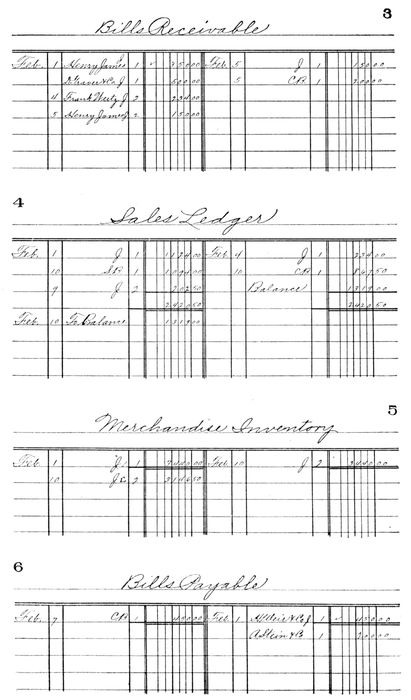
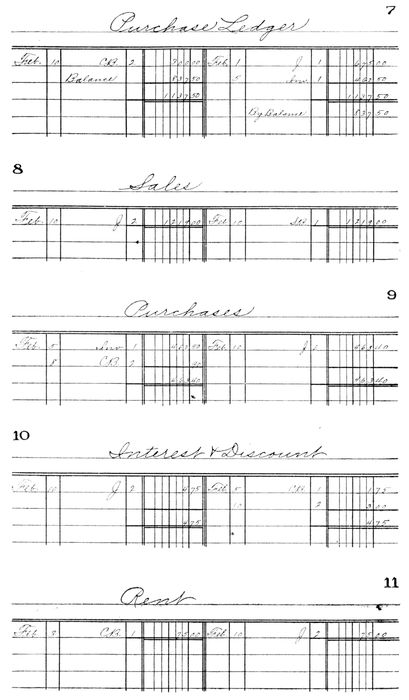
With the unprecedented increase in our commercial
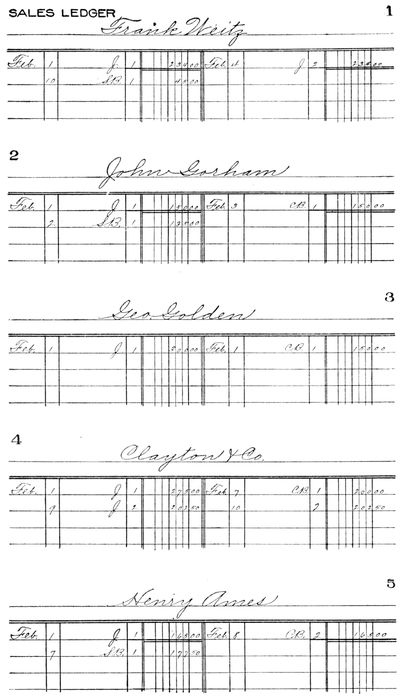
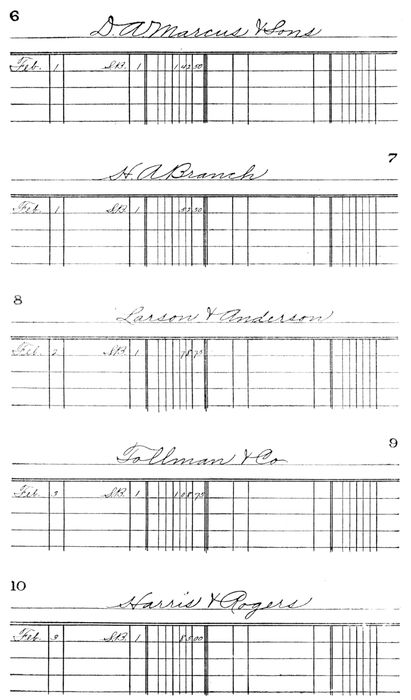
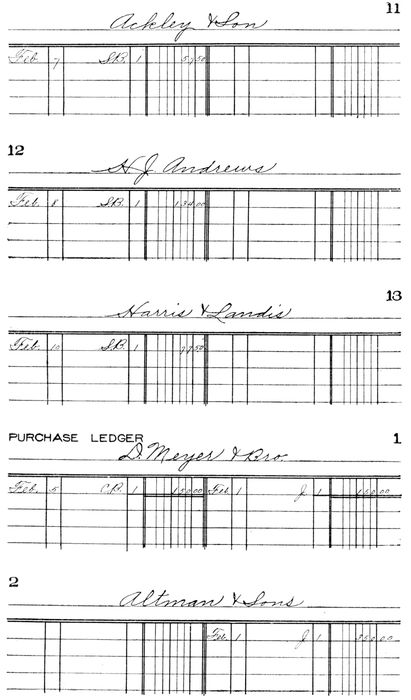
activities has come a demand for better business
methods. Methods which were adequate for the
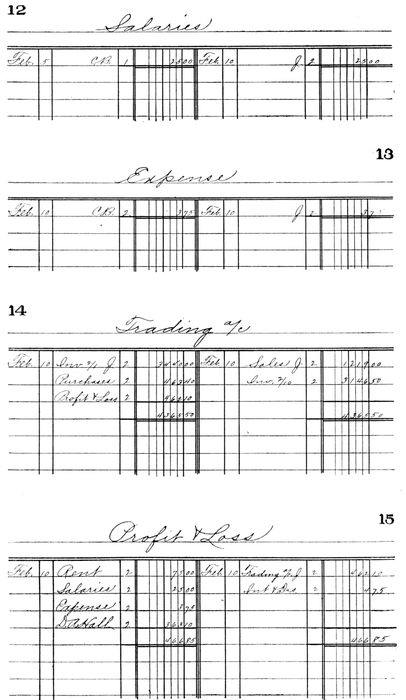
business of a less active commercial era, have given way to
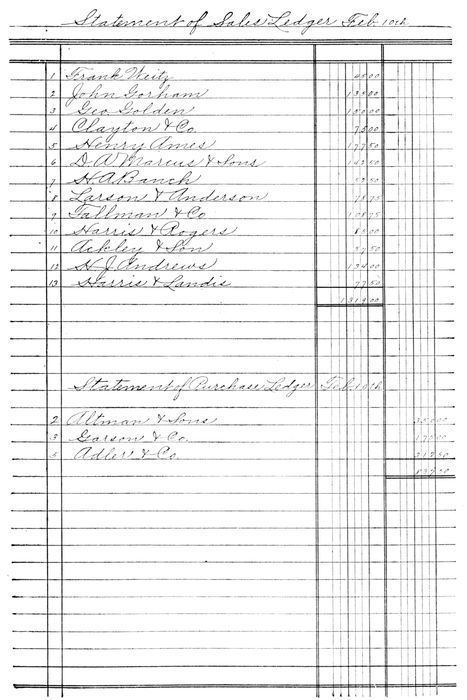
systems and labor-saving ideas in keeping with the financial
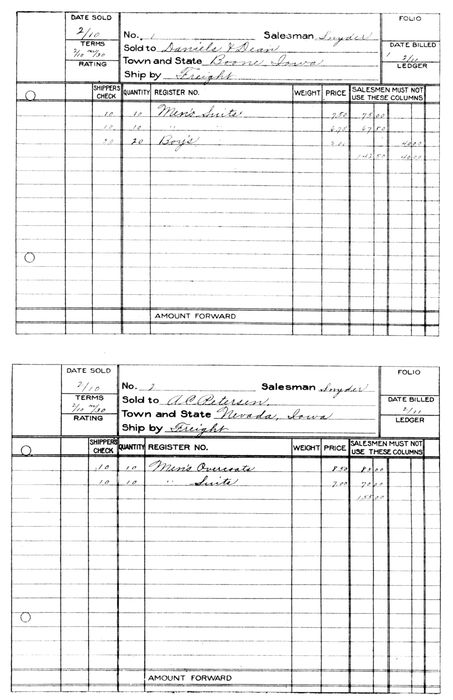
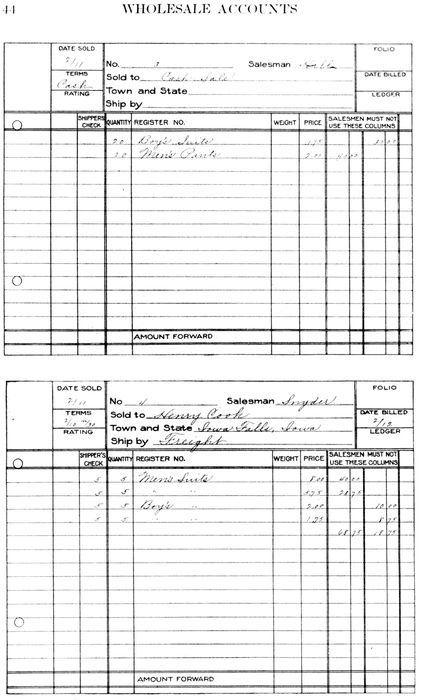
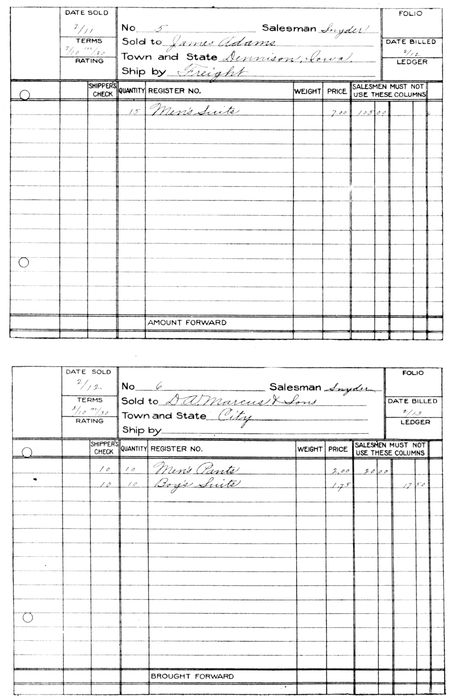
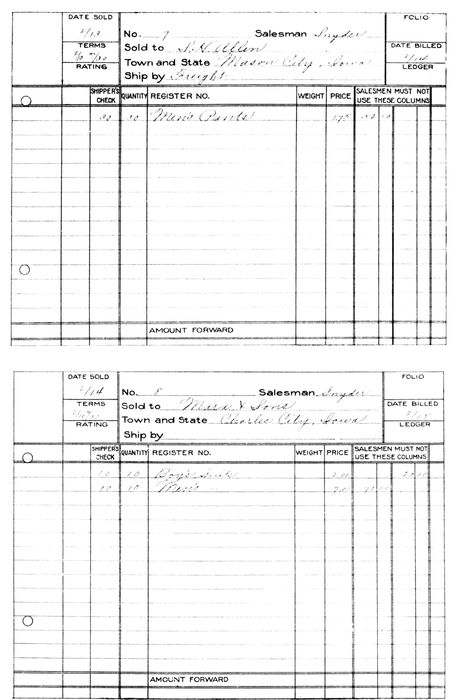
and industrial progress of the world.
¶ Out of this progress has risen a new literature—the
literature of business. But with the rapid advancement in
the science of business, its literature can scarcely be said to
have kept pace, at least, not to the same extent as in other
sciences and professions. Much excellent material dealing
with special phases of business activity has been prepared,
but this is so scattered that the student desiring to acquire
a comprehensive business library has found himself confronted
by serious difficulties. He has been obliged, to a great extent,
to make his selections blindly, resulting in many duplications
of material without securing needed information on important
phases of the subject.
¶ In the belief that a demand exists for a library which
shall embrace the best practice in all branches of business—from
buying to selling, from simple bookkeeping to the
administration of the financial affairs of a great corporation—these
volumes have been prepared. Prepared primarily for
9use as instruction books for the American School of Correspondence,
the material from which the Cyclopedia has been
compiled embraces the latest ideas with explanations of the
most approved methods of modern business.
¶ Editors and writers have been selected because of their
familiarity with, and experience in handling various subjects
pertaining to Commerce, Accountancy, and Business Administration.
Writers with practical business experience have
received preference over those with theoretical training;
practicability has been considered of greater importance than
literary excellence.
¶ In addition to covering the entire general field of business,
this Cyclopedia contains much specialized information not
heretofore published in any form. This specialization is particularly
apparent in those sections which treat of accounting
and methods of management for Department Stores, Contractors,
Publishers and Printers, Insurance, and Real Estate.
The value of this information will be recognized by every
student of business.
¶ The principal value which is claimed for this Cyclopedia
is as a reference work, but, comprising as it does the material
used by the School in its correspondence courses, it is offered
with the confident expectation that it will prove of great
value to the trained man who desires to become conversant
with phases of business practice with which he is unfamiliar,
and to those holding advanced clerical and managerial
positions.
¶ In conclusion, grateful acknowledgment is made to authors
and collaborators, to whose hearty coöperation the excellence
of this work is due.
WHOLESALE, COMMISSION, AND STORAGE ACCOUNTS — WHOLESALE BUSINESS — DIVIDING THE LEDGER — CONTROLLING ACCOUNTS — ORDER BLANKS — SALES BOOK — INVOICE REGISTER — CASH BOOK — SUBDIVISION OF EXPENSE ACCOUNT — PETTY CASH VOUCHER — TREATMENT OF PROTESTED PAPER — SAMPLE TRANSACTIONS — EXERCISES — COMBINED ORDER AND SALES RECORD — ABSTRACT OF SALES — OUT FREIGHT — SALES EXPENSE — TRIAL BALANCE BOOK — THE CHECK REGISTER — CASH RECEIVED BOOK — SAMPLE TRANSACTIONS — EXERCISE — COMMISSION AND BROKERAGE BUSINESS — MERCHANDISE BROKER — MANUFACTURER'S AGENT — SHIPMENTS — A CONSIGNMENT — PRODUCE SHIPPER'S BOOKS — TREATMENT OF ACTUAL SALES — SHIPPER'S TRADING ACCOUNT — SAMPLE TRANSACTIONS — EXERCISE — COMMISSION MERCHANTS' BOOKS — PURCHASE AND SALE OF OWN GOODS — SAMPLE TRANSACTION — EXERCISE — STORAGE — STORAGE ACCOUNTS — SPECIAL RECORDS REQUIRED
11
In this section complete methods of bookkeeping as practiced
in wholesale houses are demonstrated. Numerous modern methods
that are readily adaptable to other lines of business are illustrated
and explained in detail.
1. There are many advantages in dividing the ledger into
sections. The subdivisions most commonly used are purchase
ledger, sales ledger, and general ledger. Such divisions greatly
facilitate posting and reduce the chances of error. While it is advisable
in most cases to use a separate book for each division, the three
ledgers may be combined in one book by setting aside a section for
each. This practice is not recommended except where the number
of accounts is small, when general and purchase ledgers or purchase
and sales ledgers may be combined. The division of the ledger into
three sections does not necessitate radical changes, either in form or
method of handling, in the other books.
2. Purchase Ledger. The purchase ledger contains only
accounts with those from whom we are making purchases. The
balances of the accounts in this ledger will be on the credit side and
represent a liability. The total balance of the purchase ledger is the
amount we owe on open accounts. If, for example, our purchases
on account during a stated period amount to $964.50, and the amount
paid on account by us is $320.30, we still owe $644.20. If the work
is correct the combined balances of all open accounts in the purchase
ledger will exactly equal this amount.
123. Sales Ledger. The sales ledger contains only accounts with
customers to whom goods are sold on account. The balances of
the accounts in the sales ledger will be on the debit side and represent
an asset. The total balance of the sales ledger is the amount that
our customers owe us on open accounts. Suppose that a business is
started with no open accounts receivable—during a stated period
the sales on account amount to $1,427.75, and the total payments
received on account are $965.50—the amount still outstanding is
$462.25, and this amount should exactly equal the combined balances
of all the open accounts in the sales ledger.
The sales ledger is sometimes subdivided into two or more
parts. The divisions may be City and Country or they may be according
to the letters of the alphabet—as A-K, L-Z, etc.
4. Accounts in Both Ledgers. Occasionally one from whom
we are purchasing goods will also be a customer. For reasons which
will appear later, accounts should, in these cases, be opened in both
the purchase ledger and the sales ledger. When settlement of such an
account is made, the necessary adjusting entries are made through
the journal.
5. General Ledger. The general ledger contains the investment
accounts of the proprietor or partners, and all real, representative, and
nominal accounts. Accounts with the purchase and sales ledgers
are also kept in this ledger. These are controlling accounts which
represent at all times the total balances of the purchase and sales
ledgers.
When statements of the other ledgers have been made and
proved correct, a trial balance of the general ledger is made.
6. A controlling account is one which exhibits a summary of
all of the accounts in a ledger, or of all accounts of the same class.
The sales account, with which the student has been made acquainted,
exhibits net sales, while a sales controlling account exhibits a
summary of all accounts in the sales ledger. The debits to the sales
controlling account represent the total debits to customers' accounts
as shown by the sales book or the journal. The credits to the sales
controlling account represent the total credits to customers as shown
by the cash book and the journal. This account is variously styled
13Sales Ledger Account, Accounts Receivable Account, or Sales Controlling
Account.
A purchase controlling account exhibits a summary of all accounts
in the purchase ledger. It is called a Purchase Ledger Account,
Accounts Payable Account, or Purchase Controlling Account.
These controlling accounts are kept in the general ledger and
show at all times the totals of accounts receivable and accounts payable,
without the necessity of listing the individual balances. At
the end of the month statements of the balances of the accounts in
purchase and sales ledgers are made, and the totals of these balances
must agree with the balances of the controlling accounts.
The operation of these controlling accounts demonstrates one
of the most apparent advantages of the division of the ledger. If
an error is made in posting to an account in the sales ledger it is
discovered as soon as the statement of the sales ledger is made, and
can be located without referring to purchase or general ledger accounts.
Without the ledger division and the use of controlling accounts,
there would be nothing to assist in locating an error in the
trial balance in any particular section of the ledger.
7. In a wholesale business it is customary to have all orders
entered on specially ruled order blanks of a uniform size. These
orders are filed in a binder designed for the purpose, which takes the
place of the old style order book.
These order blanks are furnished to salesmen who send in their
orders on them. When an order is received direct from the customer
it, also, is transcribed on one of these blanks so that all order records
will be uniform. One very appreciable advantage in the use of this
loose sheet system of order blanks is that all unfilled orders are kept
in a binder by themselves.
8. Filling Orders. Each day the orders to be filled should be
placed in a temporary binder or holder and sent to the warehouse.
The packer will check quantities shipped and return the order, together
with the shipping receipt from the railroad or express company,
to the bookkeeping department.
The amounts are extended, and the invoice is made out from
this order blank. The sale is next recorded in the sales book. Instead
14of entering each item in the sales book the totals for each department
are entered in the proper column. Each sale is numbered in the
sales book as illustrated and the same number is placed on the order.
These orders are then filed in the binder for filled orders in exact
numerical order, which brings them also in the order of the dates of
shipment.
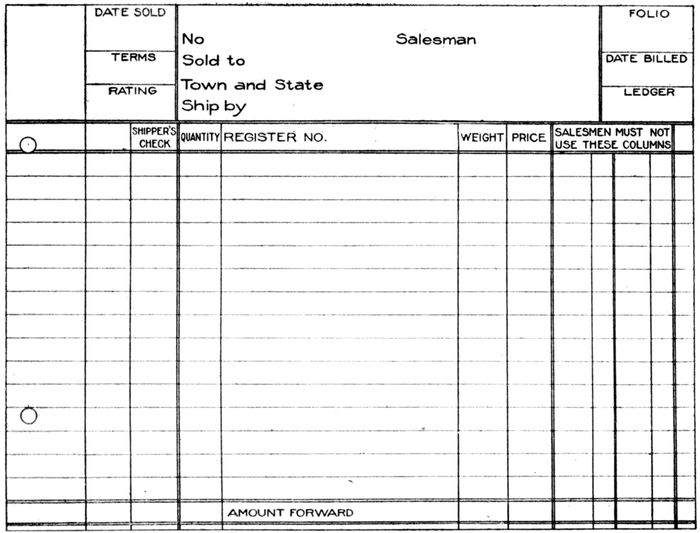
9. The sales book used in this set exhibits some features not
heretofore shown. At the right are three columns for the distribution
of sales. At the left, in addition to columns for number, date, and
folio, are two columns headed cash and sales ledger. All cash sales
are entered in the cash column, and all sales on account are entered
in the sales ledger column. At the end of the week or month the
total of the sales ledger column is posted to the debit of the sales
ledger account in the general ledger, while the totals of the sales
columns at the right are posted to the credit of the sales account in
the general ledger.
15
10. A form of purchase book, which also combines an invoice
register, is shown in this set. Unlike the forms of purchase book
with which the student has been made familiar, this invoice register
gives full particulars as to terms, discount, when due, and when and
how paid.
The combined footings of the two department columns must
of course agree with the footing of the amount column. At the end
of the month the total of the amount column is posted to the credit
of purchase ledger account in the general ledger, and the totals of the
department columns are posted to the debit of the purchase account
in the general ledger.
The details of payment are kept in the invoice register as a memorandum
only. This provides a convenient record of unpaid invoices,
showing when each is due.
11. In this set we introduce a columnar cash book which also
serves as a journal for cash transaction and is known as a cash journal.
The principal advantage of a columnar book lies in the opportunity
to introduce columns with special headings for accounts to which
entries are frequent. Not only does this permit of carrying footings
to the end of the month with one posting to the ledger account, but
it provides a convenient classification of receipts and expenditures
with a complete segregation of items of a given class.
In the form illustrated, columns are provided on the debit side
for cash, purchase ledger (subdivided for discount and amount),
bank deposits, and sundries; on the credit side, cash, sales ledger
(subdivided for discount and amount), cash sales, bank withdrawals,
and sundries. At first glance it might appear that this form is a
departure from the regular form of cash book, but it should be remembered
that the cash columns are the only ones having anything to do
with the cash account. A cash receipt is entered in the cash debit
column, but the amount is credited to its source through the proper
credit column; thus a payment received on account is debited to cash
and credited through the sales ledger column. A deposit is credited
to cash and debited to bank deposits; the payment of a purchase ledger
16account by check is credited to bank withdrawals, and debited to
purchase ledger account.
The discount columns are memorandum columns only, the net
cash being entered in the amount columns under purchase and sales
ledger. These columns are included that the total payment may be
posted to personal accounts in purchase or sales ledger. The totals
of these columns are to be posted to discount and interest columns
at the end of the month.
The total amount to be posted to the debit of the purchase ledger
account and to the credit of sales ledger account is made up of the
totals of the discount and amount columns.
The sundries columns are provided for all entries for which
there are no special columns and are used principally for transactions
affecting general ledger accounts. These columns are sometimes
used for ordinary journal entries not involving an exchange of cash,
but their use for this purpose is strongly advised against. The cash
book should be used exclusively for recording cash transactions.
When columnar purchase, sales, and cash books are used, the journal
is only needed for adjusting and closing entries, and for this purpose
it is best to provide an ordinary two-column journal.
12. In every business there are several classes of expense and
it is very useful to know the exact amount of each class. When all
expenses are charged under one head, it is impossible to determine
without considerable checking, whether or not any particular class of
expense is more than it should be. It is customary, therefore, to
subdivide expense and to open accounts in the ledger for different
classes of expense. Some subdivisions in common use are rent (paid),
insurance, taxes, interest and discount, in freight, out freight, salaries,
labor, fuel, office supplies, telegraph and telephone, postage, general
expense, etc. The exact subdivisions used must of necessity be
governed by the nature of the business. For instance, the item of
telegraph and telephone charges may be of importance in one business,
while in another, the number of such charges would be so small
that a separate account is not warranted.
17
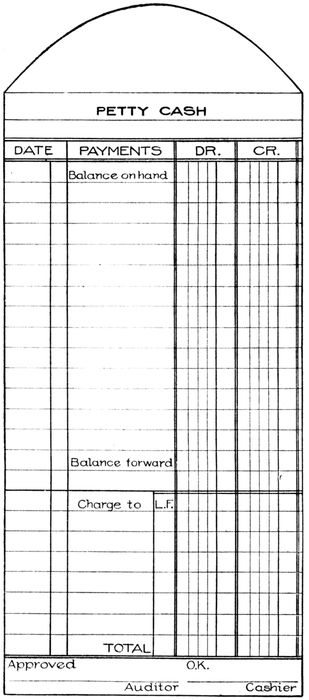
13. A form of envelope
voucher for petty
cash is illustrated. A
strong manilla envelope
in what is known as size
#10 takes the place of
the petty cash book. It
is ruled for a record of
payments, and a receipt
for each payment is
placed in the envelope.
At the bottom is a space
for a distribution of the
amounts to the proper
accounts. When the
petty cash fund is depleted—or
at stated intervals—a
check is drawn
for the amount expended
and it is charged
through the cash book,
leaving petty cash intact.
The amount of the petty
cash fund is considered
as cash on hand, and
the voucher envelope accounts
for any part of
the fund not actually in
the cash drawer. Petty
cash should be used
sparingly, as it is intended
only for small
expense items when it is
inconvenient to give a check. When the books are closed, the petty
cash expenditures may be charged through the cash book as cash payments,
instead of drawing a check.
18
14. When a note, draft, or check is protested, the bank will
charge us with the protest fee in addition to the face of the paper.
The total amount must then be charged to the one from whom the
paper was received. Suppose the check of Jones & Laughlin for
$100.00 goes to protest and is returned to us with a protest fee of
$2.50—the entry will be:
| Jones & Laughlin |
$102.50 |
|
| Bank |
|
$102.50 |
| Check No. 16 given to First Nat. |
|
|
| Bank to cover J. & L. check for |
|
|
| $100.00, protest fee $2.50. |
|
|
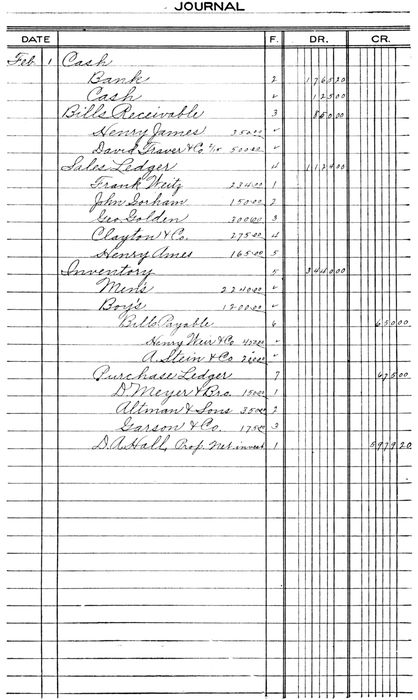
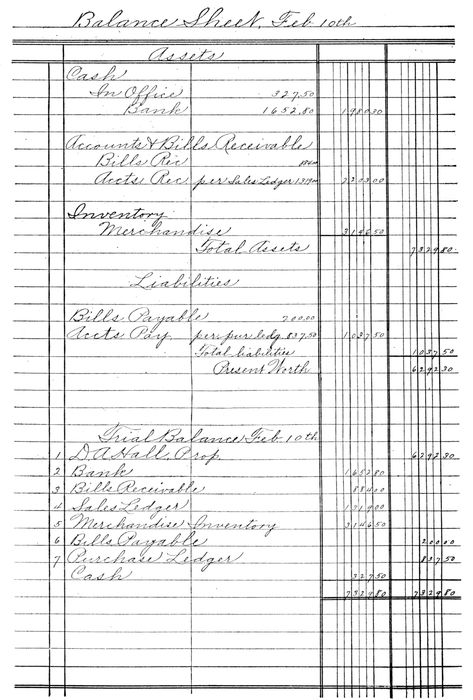
15. D. A. Hall is engaged in the business of a wholesale dealer in
men's and boys' clothing. On Feb. 1st. his balance sheet is as
follows:
| Balance Sheet, Feb. 1st, 1909. |
|---|
| Assets |
|---|
| Cash |
|
|
|
|
| In Bank |
|
$1,765.20 |
|
|
| In Office |
|
125.00 |
|
|
| |
|
|
|
|
| Total Cash |
|
|
$1,890.20 |
|
| |
| Accounts and Bills Receivable |
|
|
|
|
| Bills Receivable |
|
850.00 |
|
|
| Henry James, Due |
|
|
|
|
| Feb. 5 |
350.00 |
|
|
|
| David Traver & Co., Due |
|
|
|
|
| Feb. 15 |
500.00 |
|
|
|
| Accounts Receivable |
|
1,124.00 |
|
|
| Frank Weitz |
234.00 |
|
|
|
| John Gorham |
150.00 |
|
|
|
| George Golden |
300.00 |
|
|
|
| Clayton & Co. |
275.00 |
|
|
|
| Henry Ames |
165.00 |
|
|
|
| |
|
|
|
|
| Total Accounts and Bills Rec. |
|
|
1,974.00 |
|
| |
| 19Inventory |
|
|
|
|
| Men's clothing |
|
$2,240.00 |
|
|
| Boys' " |
|
1,200.00 |
|
|
| |
|
|
|
|
| Total Inventory |
|
|
$3,440.00 |
|
| |
|
|
|
|
| Total Assets |
|
|
|
$7,304.20 |
| |
| Liabilities |
|---|
| Accounts and Bills Payable |
|
|
|
|
| Bills Payable |
|
650.00 |
|
|
| Henry Weir & Co., Due |
|
|
|
|
| Feb. 7 |
450.00 |
|
|
|
| A. Stein & Co., Due |
|
|
|
|
| March 1 |
200.00 |
|
|
|
| |
|
|
|
|
| Accounts Payable |
|
675.00 |
|
|
| |
|
|
|
|
| D. Meyer & Bro. |
150.00 |
|
|
|
| Altman & Sons |
350.00 |
|
|
|
| Garson & Co. |
175.00 |
|
|
|
| |
|
|
|
|
| Total Accounts and Bills |
|
|
|
|
| Payable |
|
|
1,325.00 |
|
| Total Liabilities |
|
|
|
1,325.00 |
| |
|
|
|
|
| Present Worth |
|
|
|
5,979.20 |
The following transactions are entered on the books:
| —Feb. 1st— |
| Sold to D. A. Marcus & Son |
| 10 overcoats |
7.50 |
75.00 |
|
| 10 men's suits |
6.75 |
67.50 |
142.50 |
| |
|
|
|
| —1st— |
| Sold to H. A. Branch |
| 15 boys' suits |
3.50 |
52.50 |
|
| |
| —1st— |
| Rec'd from Geo. Golden |
| Cash on account |
|
150.00 |
|
| |
| —2nd— |
| Deposited in 1st Nat. Bank |
|
150.00 |
|
| |
| 20—2nd— |
| Sold to John Gorham |
| 10 men's suits |
7.00 |
70.00 |
|
| 10 men's suits |
6.50 |
65.00 |
$135.00 |
| |
|
|
|
| —2nd— |
| Sold to Larson & Anderson |
| 5 boys' suits |
2.75 |
13.75 |
|
| 10 men's suits |
6.50 |
65.00 |
78.75 |
| |
|
|
|
| —2nd— |
| Sold for cash |
| Men's clothing |
|
37.50 |
|
| |
| —3rd— |
| Sold to Tallman & Co. |
| 15 men's overcoats |
7.25 |
108.75 |
|
| |
| —3rd— |
| Paid 1 month's rent, Ck. |
| No. 1 |
|
75.00 |
|
| |
| —3rd— |
| Received from John Gorham |
| Cash on account |
|
150.00 |
|
| |
| —4th— |
| Bought from Carson & Scott |
| 36 men's corduroy coats |
3.00 |
108.00 |
|
| 12 men's corduroy coats |
3.50 |
42.00 |
150.00 |
| Terms 2/10, 1/30, n/60 |
|
|
|
| |
| —4th— |
| Deposited in 1st Nat. Bank |
|
187.50 |
|
| |
| —4th— |
| Sold to Harris & Rogers |
| 12 men's corduroy coats |
3.75 |
45.00 |
|
| 5 overcoats |
8.00 |
40.00 |
85.00 |
| |
| —4th— |
| Received from Frank Weitz |
| Note at 30 days, 6% |
|
234.00 |
|
| |
| 21—5th— |
| Sent to D. Meyer & Bro. Ck. |
| No. 2 |
|
$150.00 |
|
| |
| —5th— |
| Received from Henry James |
| Cash to apply on note |
|
200.00 |
|
| Cash for interest |
|
1.75 |
$201.75 |
| New note 30 days, 6% |
|
|
150.00 |
| |
| —5th— |
| Bought from Adler & Co. |
| 50 men's suits |
6.25 |
312.50 |
|
| Terms 3/10, 1/30, n/60 |
|
|
|
| |
| —5th— |
| Paid salesman's salary Ck. |
| No. 3 |
|
25.00 |
|
| |
| —5th— |
| Drew for personal use Ck. |
| No. 4 |
|
50.00 |
|
| |
| —7th— |
| Sold to Henry Ames |
| 20 men's suits |
7.50 |
150.00 |
|
| 10 boy's suits |
2.75 |
27.50 |
177.50 |
| |
|
|
|
| —7th— |
| Sold to Ackley & Son |
| 10 boy's overcoats |
3.00 |
30.00 |
|
| 10 boy's suits |
2.75 |
27.50 |
57.50 |
| |
|
|
|
| —7th— |
| Received from Clayton & Co. |
| Check to apply on acct. |
|
200.00 |
|
| |
| —7th— |
| Deposited in 1st Nat. Bank |
|
401.75 |
|
| |
| —7th— |
| Paid our note to H. Weir & Co. |
| Check No. 5 |
|
450.00 |
|
| |
| 22—8th— |
| Sold to H. J. Andrews |
| 10 men's overcoats |
8.00 |
80.00 |
|
| 12 men's corduroy coats |
4.50 |
54.00 |
$134.00 |
| |
|
|
|
| —8th— |
| Paid express on shipment from |
| Carson & Scott, Ck. No. 6 |
|
.90 |
|
| |
| —8th— |
| Received from Henry Ames |
| Cash on account |
|
165.00 |
|
| |
| —8th— |
| Sold for cash |
| 1 job lot boy's clothing |
|
87.50 |
|
| |
| —9th— |
| Deposited in 1st Nat. Bank |
|
252.50 |
|
| |
| —9th— |
| Received from bank, check of |
| Clayton & Co., protested |
| for non-payment. |
| Amount of check |
|
200.00 |
|
| Protest fees |
|
2.50 |
|
| |
| —10th— |
| Sold to Harris & Landis |
| 10 men's overcoats |
7.75 |
77.50 |
|
| |
| —10th— |
| Sold to Frank Weitz |
| 12 men's corduroy coats |
3.75 |
45.00 |
|
| |
| —10th— |
| Paid Carson & Scott |
| Check No. 7 |
|
147.00 |
|
| Discount 2% |
|
3.00 |
|
| |
| —10th— |
| Paid electric light bill |
| Check No. 8 |
|
3.75 |
|
| |
| 23—10th— |
| Received from Clayton & Co. |
| Cash to redeem protested |
| check |
|
$202.50 |
|
| |
| —10th— |
| Inventory at close of business, |
| Feb. 10 |
| Men's clothing |
|
1,898.75 |
|
| Boy's clothing |
|
1,247.75 |
|
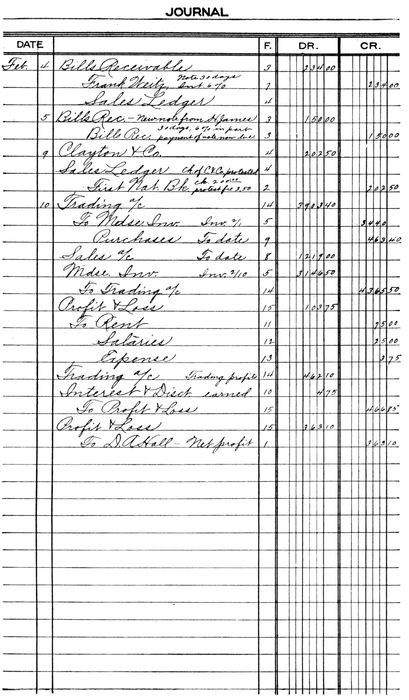
Journal entries are to be made to get the accounts, as shown
on Feb. 1st, recorded on the books. The transactions are properly
entered in journal, cash book, sales book, and invoice register, and
posted to ledger. The accounts in the general ledger are closed into
trading, and profit and loss—the net profit is credited to proprietor's
account—a trial balance is taken after the ledger is closed, and a
balance sheet is made. Statements are prepared from sales and
purchase ledgers, which agree with the balances of their controlling
accounts. All accounts in the general ledger are properly ruled
and balances carried forward.
24
25
Adjusting Journal Entries
26
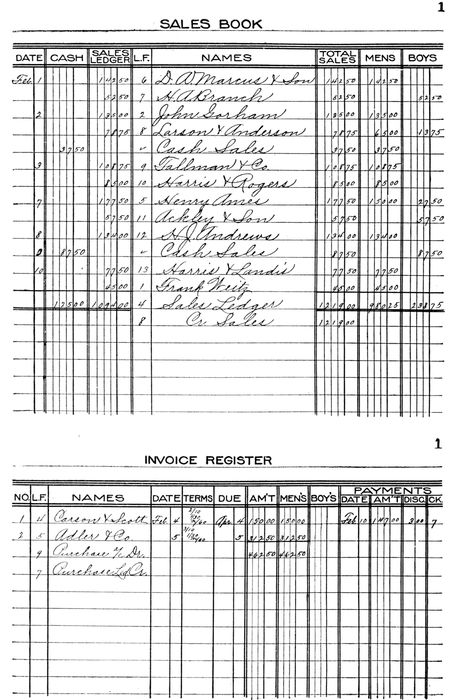
Sales Book and Invoice Register
SCENE IN SOUTH WATER STREET, WHERE THE COMMISSION HOUSES OF CHICAGO'S GREAT PRODUCE MARKETS ARE LOCATED
27
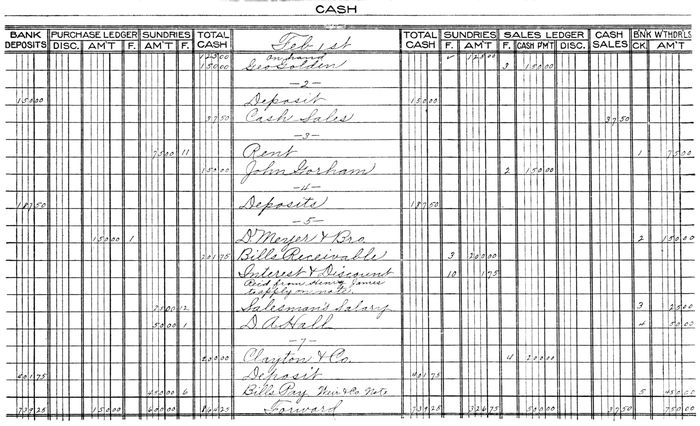
28
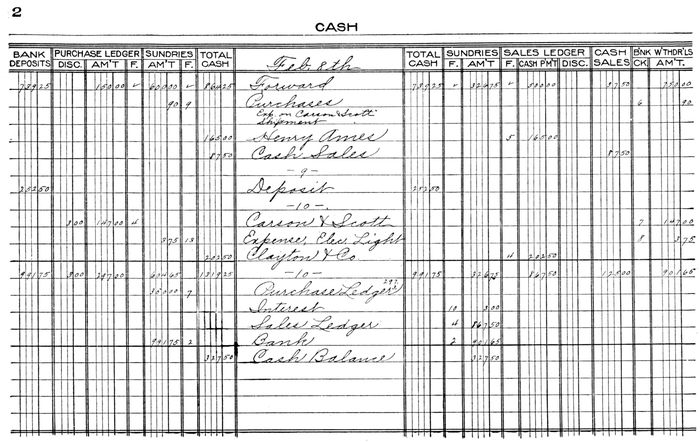
29
30
31
Sales and Purchase Ledgers
32
Purchase and General Ledgers
33
34
35
36
Statement of Sales and Purchase Ledger
37
Balance Sheet and Trial Balance of General Ledger
38
16. The following transactions are recorded on the books of
Parker and Hoadley, Omaha, Neb., wholesale dealers in tea and
coffee. In recording these transactions use is made of the books and
forms illustrated in this section.
A partnership is formed on this date between K. J. Parker
and D. C. Hoadley for the purpose of conducting a wholesale
tea and coffee business, in the name of Parker & Hoadley, the
principal place of business to be Omaha, Neb. Parker invests
$3,000.00 cash. Hoadley invests $2,000.00 cash. It is agreed
that profits are to be shared on the basis of capital invested,
capital to draw interest at 6%, and interest at 6% to be paid on
withdrawals. The books are to be closed monthly and the
profits divided between the partners. Hoadley is to assume the
entire responsibility for the conduct and management of the business,
for which he is to receive a salary of $150.00 per month, payable
in installments of $75.00 on the 15th and 31st of each month.
Deposited in Western National Bank $5,000.00.
Withdrew from bank, Ck. No. 1 petty cash $25.00.
Bought from Leggitt & Co., New York, 30 chests Japan
tea, 1,455# at .37½, 20 chests Oolong tea, 972# at .40; terms net
30, 2/10, f. o. b. N. Y.
Bought from Laughlin & Co., Chicago, 20 sacks Rio coffee,
1,020# at .22½, 20 sacks Java coffee, 985# at .25; 20 sacks
Mocha coffee, 970# at .25; terms net 30, 2/10, f. o. b. Omaha.
Paid rent of store 1 month to James Roberts, Ck. No. 2,
$60.00.
Sold to Ames & Johnson, 92 12th St., on account, 3 chests
Japan tea, 149# at .48; sack Rio coffee, 50# at .28; 1 sack Java
coffee, 52# at .32.
Sold to Landis & Snow, So. Omaha, on account, 2 chests
Oolong tea, 101# at .52; 1 sack Mocha coffee, 47# at .32; 2 sacks
Rio coffee, 98# at .28.
Sold to J. C. Peters & Son, 267 Roberts St., 3 chests Oolong
tea, 146# at .52, 5 sacks Rio coffee, 252# at .48.
39 Bought for cash from Harris & Co., 1 office desk and chair
$45.00, gave Ck. No. 3 in payment.
Paid freight on coffee from New York by Ck. No. 4, 12.93.
Sold to Wright & Noble, 146 7th St., 2 sacks Java coffee,
99# at .32; 2 sacks Mocha coffee, 101# at .32.
Sold to Horgis & Co., 84 Jackson St., 5 chests Japan tea,
248# at .48.
Sold to Winters & James, 92 Hastings St., 4 chests Japan
tea, 201# at .48; 3 chests Oolong tea, 138# at .52; 2 sacks Java
coffee, 97# at .32.
Sold for cash 1 sack Rio coffee, 47# at .28; 1 chest Japan
tea, 45# at .48.
Sold to Cobb & Willet, 892 Park Av., 2 chests Japan tea, 92#
at .48; 1 chest Oolong tea, 47# at .52; 1 sack Rio coffee, 44#
at .28; 1 sack Java coffee, 45# at .32; 1 sack Mocha coffee, 43#
at .32.
Sold to Young & Criger, 62 Watson St., 5 sacks Mocha
coffee, 205# at .32; 3 chests Oolong tea, 127# at .52.
Bought from Japan Importing Co., San Francisco, 60 chests
Japan tea, 2,700# at .36, f. o. b. Omaha, net cash; gave our note
at 10 days without interest in payment.
Paid account of Leggitt & Co., less 2% discount, Ck. No. 5.
Ames & Johnson paid their account, less 2% cash discount.
Deposited cash received to date.
Sold to Wade & Francis, 92 Bluff St., 10 chests Japan tea,
448# at .48.
Paid for telegram—petty cash—.40.
Received check from Landis & Snow in full settlement of
their account.
Sold to J. C. Peters & Son, 5 sacks Java coffee, 231# at .32.
Sold for cash 3 sacks Rio coffee, 127# at .28; 2 sacks Mocha
coffee, 89# at .32; 3 sacks Japan tea, 131# at .48.
Deposited cash on hand, also check of Landis & Snow.
40 Sold to Ames & Johnson, 2 sacks Mocha coffee, 91# at .32;
2 chests Oolong tea, 87# at .52.
Sold to Wright & Noble, 3 chests Japan tea, 129# at .48; 1
chest Oolong tea, 42# at .52.
Paid for fuel by check No. 6 to Rogers Coal Co., 12.00.
Paid clerk's salary, check No. 7, 10.00.
Paid for labor, check No. 8, 16.50.
Sold to Watkins & Fish, 64 Prairie Av., 5 chests Oolong
tea, 207# at .52.
Bought from Western Grocer Co., Chicago, 50 chests Oolong
tea, 418# at .39; 20 sacks Rio coffee, 876# at .22¼; 10 sacks Java
coffee, 434# at .25; 15 sacks Mocha coffee, 653# at .25; terms 30
days net, 2/10, f. o. b. Omaha.
Received from Wright & Noble cash in payment of our bill
of Jan. 4th, less 2% cash discount.
Received from bank, check of Landis & Snow protested for
non-payment, protest fees added 1.90.
Sent Laughlin & Co. our check No. 9 in payment of account
Sold to Raymond H. Moss, 182 Spring St., 5 chests Japan
tea, 217# at .48; 5 sacks Rio coffee, 214# at .28.
Sold to Watkins & Fish, 10 sacks Mocha coffee, 424# at .32.
Cobb & Willet paid their account in full, deducting 2% for
cash.
Deposited cash on hand.
Sold to Cobb & Willet, 5 chests Japan tea, 213# at .48.
Sold for cash, 2 sacks Rio coffee, 88# at .28.
Paid our note to Japan Importing Co., check No. 10.
Paid sundry office expenses from petty cash 3.60.
Sold to Wade & Francis 3 sacks Rio coffee, 123# at .28; 2
sacks Mocha coffee, 86# at .32.
Paid clerk's salary, ck. No. 11, 10.00.
Paid for labor, ck. No. 12, 16.50.
Paid ½ month's salary to D. C. Hoadley, ck. No. 13, 75.00.
1st. Balance cash, first charging petty cash expenditures as a cash payment.
2nd. Post purchase book, sales book, journal, and cash book.
3rd. Take a trial balance.
4th. Credit interest to partner's accounts.
5th. Take an inventory of stock on hand. The records show quantities purchased and quantities sold. When the same goods have been purchased at different prices, use the last price paid in figuring inventory.
6th. Close accounts into trading and profit and loss accounts.
7th. Distribute net profits to partners' capital accounts.
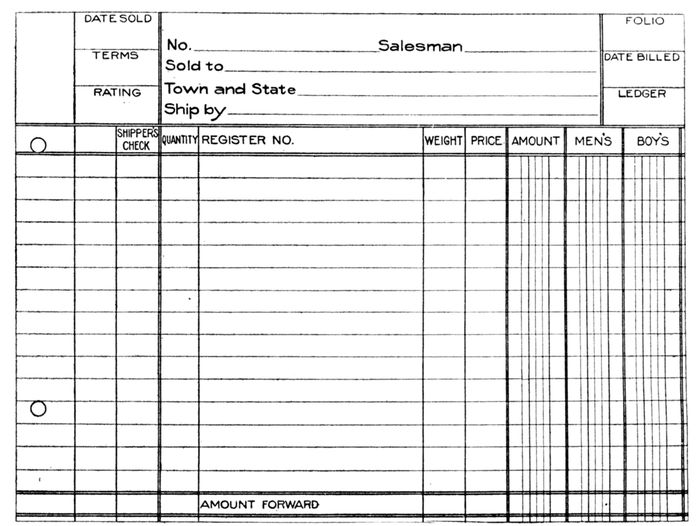
17. Instead of keeping separate order and sales books, both
records may be combined on one blank. This is accomplished by
the use of order blanks provided with columns for the distribution
of sales to the different departments. Before the order is filled
these blanks are handled in the same manner as those without distribution
columns. When filled, the amounts are extended in the
proper columns and the invoice made. The orders are then filed in
a binder, each day's orders being kept together, and postings made
direct to customers' accounts. The footings are carried forward to
the end of the month and totals posted to sales accounts. The original
orders thus become a loose leaf sales book.
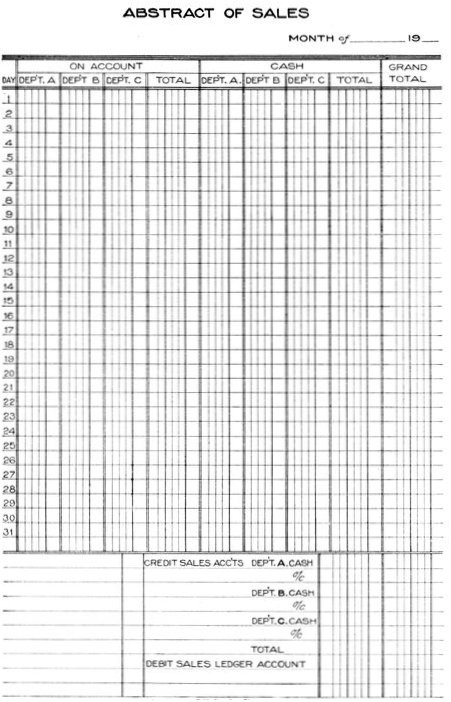
18. When the order blank is used as a sales record, making a
sales book with a record of a single sale to a sheet, it is somewhat
inconvenient to determine from the footings the total sales for the
day. This information is of considerable value, as a knowledge of
what is being done from day to day is of importance to the principals
of a business. Such a record is provided for by an abstract of sales
on a separate sheet. This abstract should show total sales for each
day, both cash and on account, divided by departments.
The blank may be made the same size as the order blanks, and
filed in the sales binder at the beginning of the month. Sales are
42recorded daily and footings carried forward to the end of the month,
when the totals may be posted direct to the credit of the sales account
in the general ledger. The totals of sales on account will be posted
to the debit of the sales controlling account in the general ledger.
19. The proper treatment of freight paid on outgoing shipments
is an important question in accounting. When goods are
sold at delivered prices, the freight paid is one of the items of expense
in selling the goods, and when the books are closed the account will
be closed into profit and loss. However, in a wholesale business,
freight is sometimes paid as an accommodation to the customer when
the goods have been sold at f. o. b. prices. Although the amount
should be added to the invoice it should not be credited to the sales
account as this would be taking credit for a fictitious trading profit.
Such an item should be made a special charge against the customer
by means of a journal entry.
Customer Dr.
Out Freight Cr.
Combined Order and Sales Record
THE GENERAL OFFICES OF THE SAMUEL C. TATUM CO., CINCINNATI, OHIO
43
Abstract of Sales by Departments
44
20. In a wholesale or manufacturing business it is very desirable
that the exact cost of selling goods be known. Broadly, this cost
is covered under the general head of sales expense, but this is usually
divided into several classes of expenditures. The segregation of the
various items of sales expense is desirable for the purpose of determining
the percentage of each. The items which properly belong
in sales expense depend somewhat on the nature of the business.
For example, traveling expenses are usually a direct sales expense,
but in some businesses they may be chargeable to the cost of purchases.
The items entering into sales expense of the average business
are: advertising, salaries of salesmen, traveling expenses of
salesmen, commissions paid on sales, cost of packing and shipping,
out freight.
21. Advertising. This account should be charged with all
expenditures for publicity such as newspaper, magazine, street car,
and bill board advertising, cost of printing catalogs, booklets, and
circulars. Where there is any reason for so doing, the cost of the
different classes of advertising can, of course, be kept in separate
accounts. The aim and object of advertising being to increase the
sale of goods, it is properly considered an item of sales expense.
22. Salaries of Salesmen. This account is charged with all
salaries paid to salesmen whether traveling or working in the house.
Commissions and bonuses are sometimes included in this account,
but it is usually considered best to keep them in separate accounts.
23. Traveling Expenses of Salesmen. This account is charged
with all legitimate traveling expenses of salesmen, the specific items
included depending largely on the nature of the business. For
example, in some businesses a liberal allowance is made for the entertainment
of customers, while in others this item is never allowed.
In any business the traveling expense account requires careful scrutiny.
Salesmen should be required to furnish an itemized statement
or voucher of expenses at stated intervals. For convenience, this
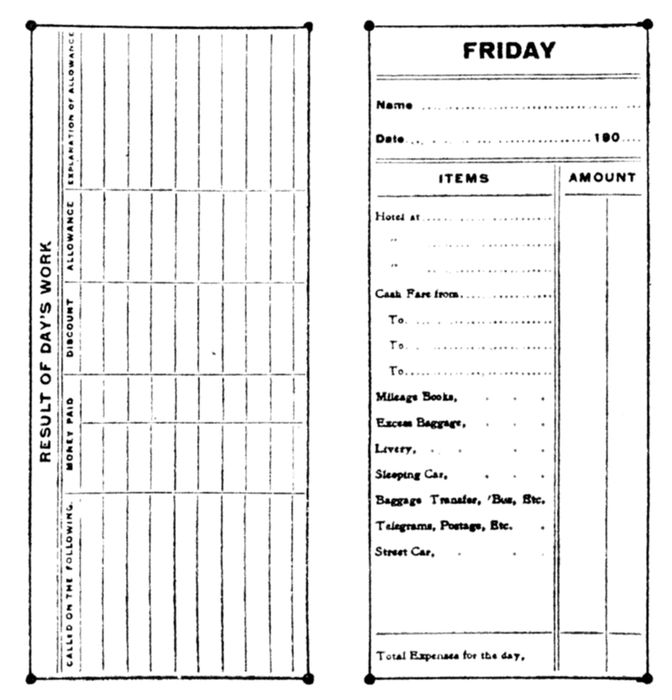
should be made on a form specially provided for the purpose. One
of the most convenient and popular expense vouchers is in the form of
a book of a convenient pocket size, with a page for each day of the
week and a summary of the week's expenses on the last page.
24. Packing and Shipping. This account is charged with the
45entire cost of packing goods for shipment. It includes such items
as wages of shipping clerk and his assistants, crates, lumber, boxes,
and all other packing materials.
25. To save rewriting
the names of the accounts
each month, a trial balance
book can be used to good
advantage. These books
are made to accommodate
six trial balances on a
double page, and are sometimes
made with alternate
short leaves so that twelve
trial balances may be made
with one writing of the
names. When the trial
balance book is used, care must be exercised in providing space
for the addition of new accounts in each section. Where separate
sales and purchase ledgers are used, it is best to provide a trial balance
book for each ledger.
26. Large check books are cumbersome to handle and necessitating
the expenditure of much needless labor. Their use is rapidly giving
way in modern offices to the check register. The check register has
several distinct advantages. It exhibits, in compact form, a record
of all checks issued and can also be arranged to show deposits and
balance in the bank. Distribution columns can be provided with
headings for the different expenditure accounts, which makes of the
check register a cash expenditure book. The form should be varied
to suit the business in which it is to be used. A typical form is illustrated
on page 37.
27. Checks in Pads. When the check register is used it is the
usual custom to have checks put up in pads. After the check is
written, it is registered and numbered to correspond to the register
number. With the use of padded checks, it is not necessary for the
clerk who writes the check to know anything about the bank balance.
46
47
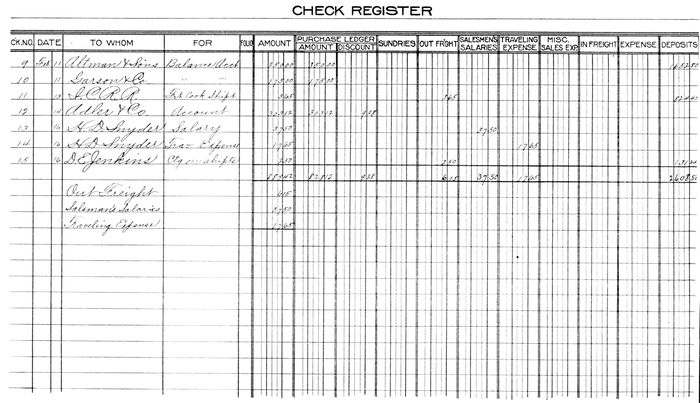
Check Register Combined with Cash Expenditure Book
48
49
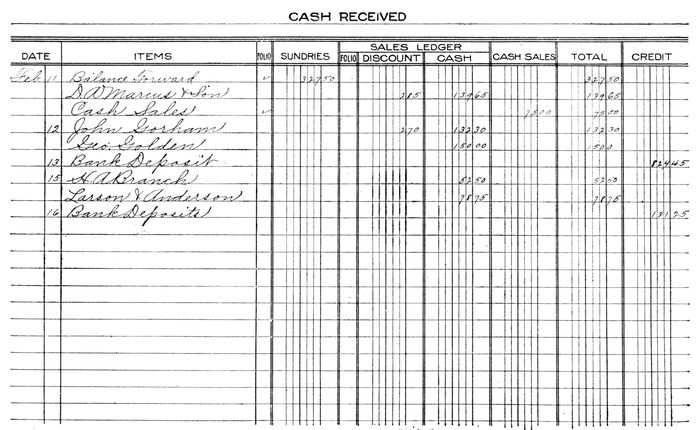
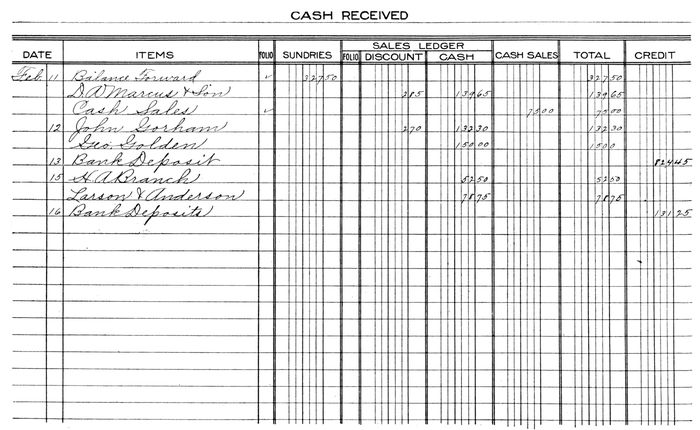
28. A cash book specially ruled for a record of cash received
is used to supplement the check register or cash expenditure book.
Columns are provided for the different classes of receipts, with one
credit column. It is assumed that all cash received is deposited,
payments being made exclusively by check. This does not refer to
petty cash expenditures which should be kept in a petty cash book or
on envelope vouchers.
29. The following transactions illustrate the use of the special
blanks and books described.
D. A. Hall employs H. D. Snyder as traveling salesman for
the purpose of increasing his business, agreeing to pay him a
salary of $150.00 per month and expenses. He commences work
on Feb. 11th. The amounts in the ledgers stand as shown in
the last model set illustrated and these transactions are recorded:
| —Feb. 11th.— |
| Paid Altman & Sons |
|
|
| To balance account |
|
|
| Ck. No. 9 |
|
$350.00 |
| |
|
|
| —11th— |
| Paid Garson & Co. |
|
|
| To balance account |
|
|
| Ck. No. 10 |
|
175.00 |
| 50 |
|
|
| |
|
|
| —11th— |
| Sold to Daniels & Dean, Boone, Ia. |
|
|
| 10 men's suits |
$7.50 |
$75.00 |
| 10 men's suits |
6.75 |
67.50 |
| 20 boys' suits |
2.00 |
40.00 |
| |
|
|
| |
|
182.50 |
| Terms 2/10 N/30 |
|
|
| |
|
|
| —11th— |
| Sold to A. C. Petersen, Nevada, Ia. |
|
|
| 10 men's overcoats |
8.50 |
85.00 |
| 10 men's suits |
7.00 |
70.00 |
| |
|
|
| |
|
155.00 |
| Terms 2/10 N/30 |
|
|
| |
|
|
| —11th— |
| Received from D. A. Marcus & Son |
|
|
| Cash |
|
139.65 |
| Discount 2% |
|
2.85 |
| |
|
|
| —11th— |
| Sold for cash |
|
|
| 20 boys' suits |
1.75 |
35.00 |
| 20 men's pants |
2.00 |
40.00 |
| |
|
|
| —12th— |
| Received from John Gorham |
|
|
| Cash 132.30 |
|
|
| Discount 2% 2.70 |
|
|
| |
|
|
| —12th— |
| Sold to Henry Cook, Iowa Falls, Ia. |
|
|
| 5 men's suits |
8.00 |
40.00 |
| 5 men's suits |
5.75 |
28.75 |
| 5 boys' suits |
2.00 |
10.00 |
| 5 boys' suits |
1.75 |
8.75 |
| |
|
|
| |
|
87.50 |
| Terms 2/10, N/30 |
|
|
| |
|
|
| —12th— |
| Sold to James Adams, Dennison, Ia. |
|
|
| 15 men's suits |
7.00 |
105.00 |
| Terms 2/10, N/30 |
|
|
| 51 |
|
|
| —12th— |
| Received from Geo. Golden |
|
|
| Cash |
|
$150.00 |
| |
|
|
| —13th— |
| Sold to D. A. Marcus & Sons |
|
|
| 10 men's pants |
2.00 |
20.00 |
| 10 boys' suits |
1.75 |
17.50 |
| |
|
|
| |
|
37.50 |
| Terms 2/10, N/30 |
|
|
| |
|
|
| —13th— |
| Paid freight on shipment to |
|
|
| Henry Cook |
|
|
| Ck. No. 11 |
3.65 |
|
| Charge to Cook |
|
|
| |
|
|
| —13th— |
| Deposited cash |
|
824.45 |
| |
|
|
| —13th— |
| Sold to S. H. Allen, Mason City, Ia. |
|
|
| 30 men's pants |
1.75 |
52.50 |
| Terms 2/10, N/20 |
|
|
| |
|
|
| —14th— |
| Paid Adler & Co. |
|
|
| Ck. No. 12 |
|
303.12 |
| Discount |
|
9.38 |
| |
|
|
| —15th— |
| Sold to Marx & Sons, Charles City, Ia. |
|
|
| 10 boys' suits |
2.00 |
20.00 |
| 10 men's suits |
7.00 |
70.00 |
| |
|
|
| Terms 2/10, N/30 |
|
90.00 |
| |
|
|
| —15th— |
| Received from H. A. Branch |
|
|
| Cash |
|
52.50 |
| |
|
|
| —15th— |
| Received from Larson & Anderson |
|
|
| Cash |
|
78.75 |
| 52 |
|
|
| —16th— |
| Paid H. D. Snyder |
|
|
| 1 week's salary |
|
$37.50 |
| Ck. No. 13 |
|
|
| |
|
|
| —16th— |
| Paid H. D. Snyder |
|
|
| Traveling expenses |
|
17.65 |
| Ck. No. 14 |
|
|
| |
|
|
| —16th— |
| Deposited cash on hand |
|
131.25 |
| |
|
|
| —16th— |
| Paid D. E. Jenkins |
|
|
| For cartage on shipments |
|
2.50 |
| Ck. No. 15 |
|
|
1. Prepare a trial balance of the ledger as it would appear
after posting these transactions.
2. Assuming that gross trading profits average the same per
cent of selling prices as in former transactions of this business house,
find approximate inventory at close of business Feb. 16th.
3. Prepare trading and profit and loss account, based on this
inventory.
53
54
55
56
57
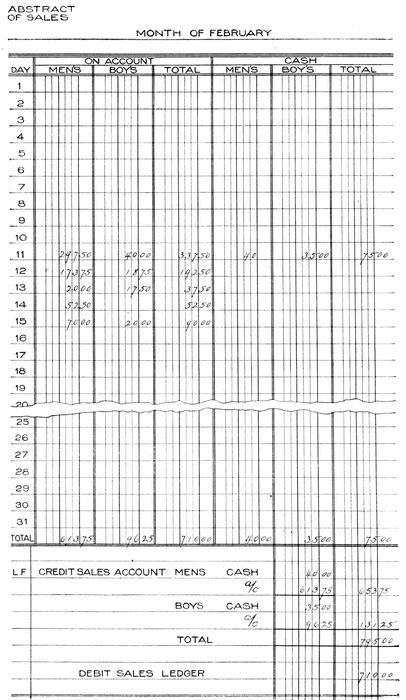
Departmental Abstract of Sales
58
ONE OF THE ELECTRICAL MANUFACTURING PLANTS OF THE FAIRBANKS-MORSE COMPANY
59
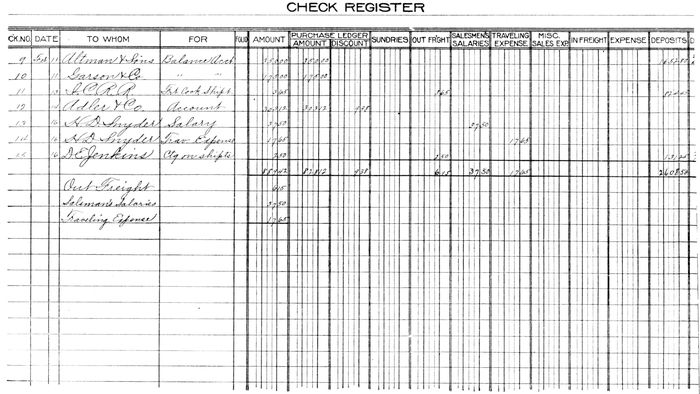
Check Register and Cash Expenditure Book
60
30. Commission or brokerage is the business of buying and
selling goods for another. The commission merchant or broker acts
in the capacity of agent, charging a stated per cent or commission
for his services.
Certain commodities are sold on the market at the best prices
obtainable, the prices depending upon the condition of the market—the
supply and demand. Since it would be both inconvenient and
unprofitable for each seller to accompany his own wares to market,
he avails himself of the services of the commission merchant. The
class of goods most largely dealt in by commission merchants is farm
produce, shipped to the cities by both producers and country dealers.
The practice of shipping produce to the broker to be sold on
commission is gradually falling into disuse. As the business is now
conducted, the commission merchant buys the produce outright and
takes his own chances of making a profit, and thus his business becomes
also that of a wholesaler.
31. Certain classes of merchandise are marketed through the
medium of brokers styling themselves merchandise brokers. Their
business is usually transacted on a larger scale than that of the ordinary
commission merchant. The merchandise broker sells in large
quantities—as salt by the car load.
The distinction between the commission merchant and the broker
lies in the fact that the commission merchant has the goods to be sold
actually in his possession, while the broker acts as agent for the purchase
and sale of goods which he does not actually handle.
32. One distinct class of brokers is the sales agent or manufacturer's
agent. He is a broker who sells goods for the manufacturer,
usually by sample. As a rule the manufacturer sets the prices
and determines the terms of credit. The goods are sold in the
name of the manufacturer who carries the accounts on his books,
paying the agent a commission for his services. In some cases, however,
the manufacturer's agent maintains his own warehouse, issues a
warehouse receipt for the goods which are shipped to him, and even
61advances money to the manufacturer. He then becomes virtually
a commission merchant. He holds the goods as security for the
money advanced, and, when sold, collects the money and remits the
balance of the net proceeds the same as the ordinary commission
merchant.
33. When a principal sends goods to a commission merchant
or broker to be sold on commission, it is called a shipment. As soon
as the goods are sent, an account is opened with the shipment, and
the shipment is designated by the name of the consignee, a number,
or the name of the place—as Shipment to Richard Roe. If more
than one shipment is made to a commission merchant an account
should be opened for each one in order that the gain or loss can be
determined for individual shipments. The separate accounts should
be designated by number—as Richard Roe, shipment No. 2.
The shipment, when made, is entered in the same way as a
sale, and the items are charged at cost price. The account is also
charged with any expense incurred on account of the shipment.
When the Account Sales is received, the account is credited with the
net proceeds. It now shows either a profit or a loss which is transferred
by a journal entry to an account called Profit and Loss on
Shipments. This account is, in turn, closed into profit and loss when
the books are closed.
If at the time of closing the books there are any outstanding
shipments on which Account Sales have not been received, the debit
balances represent assets the same as inventory of merchandise on
hand.
34. Agents' or Factors' Account. If the Account Sales, when
received, is accompanied by a remittance to cover net proceeds, cash
is debited and the shipment account credited for the amount. When
a remittance is not received with the Account Sales, the shipment
account is credited with net proceeds and the amount is charged
to a new account opened in the name of the consignee as Agent or
Bailee or Factor—as Richard Roe, Agent, or Richard Roe, Bailee,
which is treated as a personal account. This does not mean that
Richard Roe is a debtor in the ordinary sense of the term, but that
he holds funds in trust; and in case of his failure, the shipper could
62recover full value instead of being obliged to accept his pro rata
share of the assets.
35. When a broker receives a shipment of goods to be sold on
commission, it is known as a consignment. He opens a memorandum
account by entering a list of the goods, but without extending any
amounts. He has not purchased the goods, but simply holds them
for sale as agent of the shipper. If there are any charges against the
consignment, as freight, cartage, or storage charges, an account is
opened in the name of the consignor. The title would be John Doe's
Consignment, and if more than one consignment is received from
John Doe a separate account is opened for each. This account is
debited for all charges, and as sales are made they are credited to
the account. When all of the goods have been sold, the broker
renders the consignor a statement, known as an Account Sales, showing
sales, expenses, and net proceeds.
If, when the books are closed, there are on hand any consignments,
or parts of consignments, unsold, the consignment accounts
are left open and represent either assets or liabilities. If expenses
have been debited and no sales credited, the account will show a
debit balance representing an asset. If sales have been credited
in excess of the expense charges, the credit balance will represent a
liability. When an Account Sales has been rendered, the account
will balance, the net proceeds having been either remitted or credited
to the consignor.
36. Principal's Account. If the broker remits the net proceeds
at the time of rendering the Account Sales, he debits the consignment
and credits cash, or bills payable as the case may be. But if he renders
an Account Sales without remitting, he opens an account with the
consignor, as John Doe, Principal, or John Doe, Bailor, and credits
the account with the net proceeds, debiting the consignment account.
The title of the account shows that he is not an ordinary debtor to
John Doe, but that the amount of the credit represents funds belonging
to John Doe and held in trust by the broker. In case of his failure
the account of John Doe, Principal, would have to be paid before the
claims of ordinary creditors.
6337. Commission Account. All sums received by the broker
for services rendered in connection with the sale of goods for a shipper
are credited to a commission account. When the books are closed
this account is closed into profit and loss.
38. The most common branch of the commission business is
that of shipping and selling produce. The books used vary somewhat
from those used by a manufacturer's agent selling to jobbers, but the
principles are the same.
Sometimes the same man conducts both the business of shipper
and broker, buying certain goods which he in turn ships to other
brokers to be sold for his account. In the produce commission
business, however, the shipper is usually a buyer, located in the
country, who buys produce from the farmer and ships to a commission
merchant in the city.
The books required by the shipper are purchase book, shipment
book, shipment ledger, cash book, journal, and general ledger.
39. Purchase Book. This book is of the same form as used
in other businesses, with as many columns as may be desired to
separate purchases of different classes of produce.
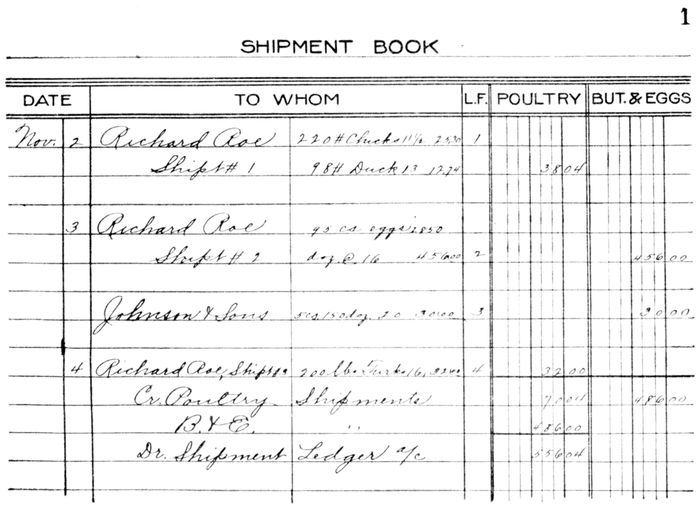
6440. Shipment Book. This is the book of original entry for
shipments in which each shipment is recorded in detail, showing
each item, with prices (usually at cost) extended. The book can be
ruled with columns for segregating shipments of different classes
of produce. The total of each shipment is posted to the debit of the
individual shipment account in the shipment ledger. The footings
of the columns are carried forward to the end of the month when they
are posted to the credit of shipment accounts in the general ledger.
These general ledger shipment accounts are opened for each class of
produce for which a separate record is desired, and correspond to the
sale account of a mercantile business.
At the end of the month the total of all shipments is posted to
the debit of a controlling account in the general ledger known as
shipment ledger account.
If more than one class of produce is shipped to an agent at the
same time it is best to make invoices for each, treating them as independent
shipments. Each package should bear a number or other
mark by which it can be identified as belonging to a particular shipment.
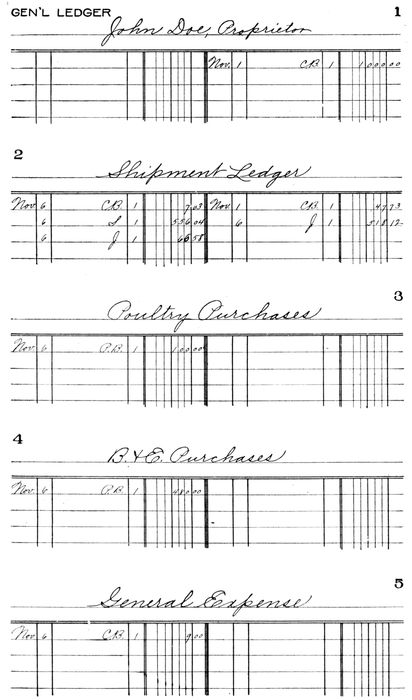
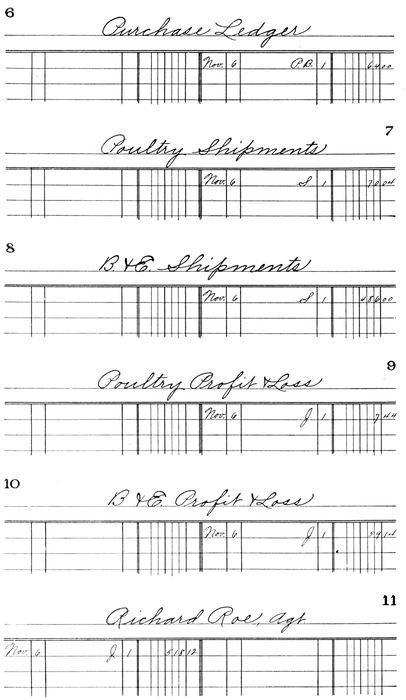
41. Shipment Ledger. An ordinary ledger can be used or a
special form prepared. Since the debit side of the account will
require much the greater amount of space, special forms are quite
desirable. A convenient form is illustrated on page 55.
42. Cash Book. Tabular cash books with special arrangement
of the column headings are used. The special features are the
column on the credit side headed shipment expense, and the debit
column headed shipment ledger. The shipment expense column is
for the expenses paid on each shipment. Expenses are posted direct
to the debit of the individual shipment accounts, and at the end of the
month the total expense is posted to the debit of the shipment ledger
controlling account. The shipment ledger column is for net proceeds
remitted with account sales. The amounts are posted to the
credit of shipment accounts, and the total is posted at the end of the
month to the credit of shipment ledger controlling account.
The sundries column is for receipts other than remittances with
account sales—as payments by agents who have not remitted with
account sales.
65
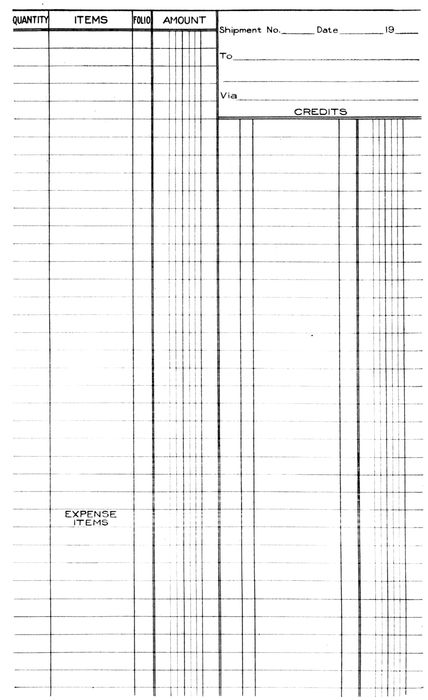
Shipment Ledger for Commission Business
66
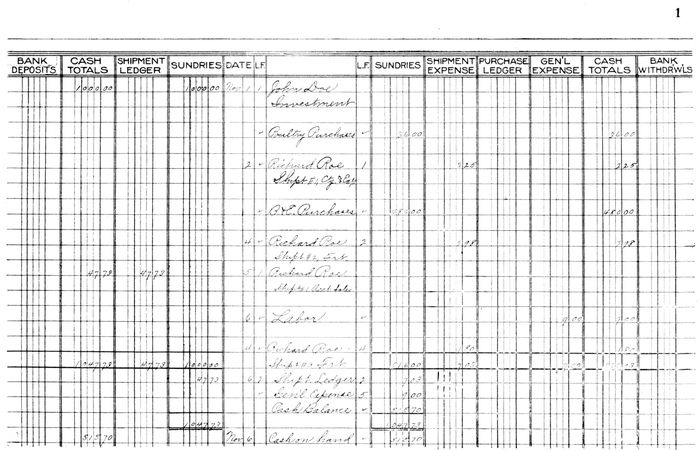
Cash Journal for Commission Business
6743. Shipment Ledger Account. This is the controlling account
of the shipment ledger. It is charged with total shipments through
the shipment book; with advance expenses through cash book or
journal; credited with net proceeds through cash book or journal.
It must also be charged with profits on shipments, or it will not represent
the total balance of shipment ledger.
When net proceeds are credited, the individual shipment account
should be charged, through the journal, with the net profit, which is
credited to Profit and Loss on Shipments. A special credit column is
provided in the journal for profits, or if a record of profits on each
class of produce is desired, two or more columns are provided.
Monthly totals are posted to the credit of profit and loss on shipment
account, or to more than one such account—as profit on poultry,
profit on butter and eggs, etc. The total of all profit columns, which
represents debits to shipment accounts, is charged to shipment ledger
account.
It is to be supposed that losses will be few, and when one is incurred
the entries should be made through the journal. The amount
will be charged to profit and loss on shipment account and credited
to both the individual shipment account and shipment ledger account.
44. Journal. As already explained, the journal should be
provided with extra columns for profits on each class of shipment.
When an agent transmits an account sales without a cash remittance,
the transaction must be journalized to close the shipment
account. When proceeds are to be charged to his account, the entry is:
|
Dr. |
Cr. |
Cr. |
| Richard Roe, Agt. |
$160.00 |
|
|
| To Shipment Ledger |
|
|
|
| Richard Roe Shipment No. 1 |
|
$160.00 |
|
| Richard Roe, Shipment No. 1 |
18.00 |
|
|
| To Profit and Loss on Shipments |
|
|
$18.00 |
If a note to cover net proceeds is received, the entry is the same
except that Bills Receivable is debited instead of Richard Roe, Agt.
When a loss is incurred the entry is:
|
Dr. |
|
|
| Profit and Loss on Shipments |
$18.00 |
|
|
| To Shipment Ledger Account |
|
|
|
| Richard Roe Shipment No. 1 |
|
|
$18.00 |
and postings will be made direct to all accounts affected.
68
45. The shipper may sell a portion of his produce outright, and
if a large share of his business is transacted in this manner, sales can
be treated exactly the same as though he was not engaged in a commission
business, with separate sales book and sales ledger.
Most shippers, however, will not find it necessary to segregate
sales to this extent. Sales can be charged to shipment accounts in
the shipment ledger, but will of course be charged at a profit, and
credited to shipment account in general ledger. Payments on these
accounts will be entered in the cash book as net proceeds.
46. The trading account of the shipper is made up somewhat
differently than for a mercantile business where all sales are supposed
to be entered at a profit.
If all his produce is sold through commission merchants, and
the inventory of produce in stock exactly equals the difference between
purchases and shipments, the account, profit and loss on shipments
represents the trading profit. But this state of affairs seldom
if ever exists. Either there will have been outright sales or a discrepancy
will appear in the inventory. The latter is usually the case in
a produce business, for some value will be lost owing to the perishable
nature of the goods handled.
The trading account is charged with all purchases and inventory,
if any, at beginning of the period, and credited with all shipments
and inventory at end of period.
The trading account now exhibits the true trading profits with
a complete segregation of profits from actual sales and commission
sales. The inventory does not include outstanding shipments, these
being treated as a separate item in the balance sheet.
| To Purchases |
$10,000 |
00 |
By shipments |
$9,000 |
00 |
| |
|
|
|
|
|
| Profit on Sales |
465 |
00 |
" Inventory |
1,465 |
00 |
| |
$10,465 |
00 |
|
|
|
| |
|
|
By Profit on Sales |
$465 |
00 |
69
47. The following transactions, taken from the books of John
Doe, shipper of poultry and butter and eggs, illustrate the books
and accounts used.
| —Nov. 1, 1908— |
| |
| Commenced business with a |
|
|
| cash investment of |
|
$1,000.00 |
| |
| —1st— |
| |
| Bought for cash |
|
|
| 200# chickens |
@ .11½ |
23.00 |
| 100# ducks |
@ .13 |
13.00 |
| |
| —1st— |
| |
| Bought from |
|
|
| Henry Meyers |
|
|
| 400# turkeys |
@ .16 |
64.00 |
| |
| —2nd— |
| |
| Shipped to |
|
|
| Richard Roe, to be sold on my a/c |
|
|
| 220# chickens |
@ .11½ |
25.30 |
| 98# ducks |
@ .13 |
12.74 |
| |
| —2nd— |
| |
| Ctg. and Exp. on above |
|
|
| paid in cash |
|
2.25 |
| |
| —3rd— |
| |
| Bought for cash |
|
|
| 100 cs. eggs, 3,000 doz. |
@ .16 |
480.00 |
| |
| —3rd— |
| |
| Shipped to |
|
|
| Richard Roe to be sold on my a/c |
|
|
| 95 cs. eggs, 2,850 doz. |
@ .16 |
456.00 |
| |
| —3rd— |
| |
| Sold to Johnson & Sons on a/c |
|
|
| 5 cases eggs, 150 doz. |
@ .20 |
30.00 |
| |
| 70 —4th— |
| |
| Shipped to Richard Roe to be sold |
|
|
| on my a/c 200# turkeys |
@ .16 |
$32.00 |
| |
| —4th— |
| |
| Paid freight on eggs to Roe |
|
2.98 |
| |
| —4th— |
| |
| Paid freight on turkeys to Roe |
|
1.80 |
| |
| —5th— |
| |
| Received from Richard Roe |
|
|
| Account Sales for Shipment No. 1 |
|
|
| Net proceeds remitted in cash |
|
47.73 |
| |
| —6th— |
| |
| Received from Richard Roe |
|
|
| Account sales for shipment No. 2 |
|
|
| Net proceeds retained by him |
|
518.12 |
| |
| —6th— |
| |
| Paid for labor |
|
|
| cash |
|
9.00 |
71
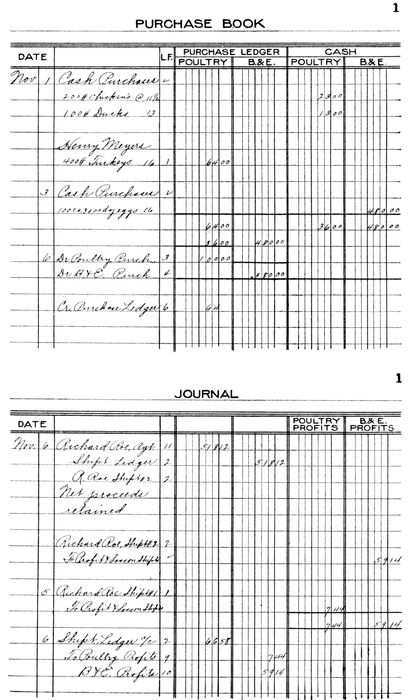
Columnar Purchase Book and Journal
72
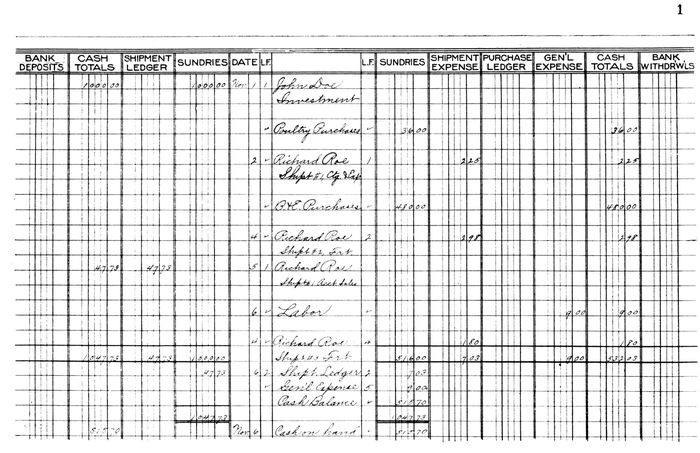
Cash Journal for Commission Business
73
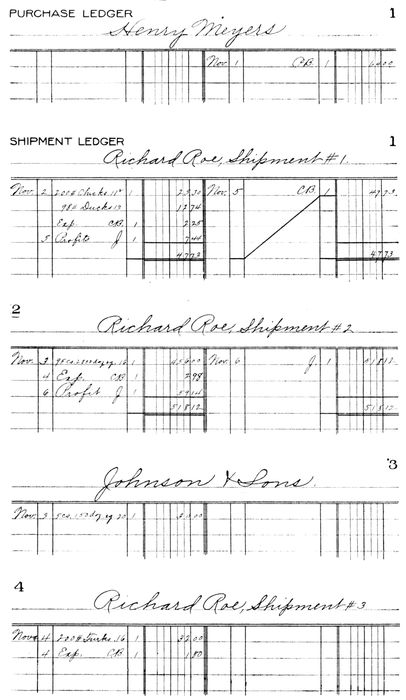
Shipper's Purchase and Shipment Ledger
74
THE ADMINISTRATION BUILDING OF THE MINNEAPOLIS STEEL & MACHINERY CO., MINNEAPOLIS, MINN.
75
76
48. On a certain date a trial balance of the ledger of Henry
Donnely, shipper of produce, stood as follows:
| DEBITS |
|---|
| |
| Purchases of apples |
|
$1,264.00 |
| Purchases of potatoes |
|
1,500.00 |
| Shipment Ledger Account |
|
736.00 |
| Cash |
|
450.00 |
| |
| CREDITS |
|---|
| |
| Shipment Account—apples |
|
1,200.00 |
| Shipment Account—potatoes |
|
1,200.00 |
| Profit on Shipments—apples |
|
250.00 |
| Profit on Shipments—potatoes |
|
350.00 |
| Accounts Payable |
|
950.00 |
| |
| During a subsequent period, his transactions were as follows: |
| |
| Cash purchases of apples |
|
1,000.00 |
| Cash purchases of potatoes |
|
1,000.00 |
| Shipments of apples |
|
900.00 |
| Shipments of potatoes |
|
1,100.00 |
| Profits on apples |
|
100.00 |
| Profits on potatoes |
|
200.00 |
| Account Sales for which cash was received |
|
1,800.00 |
| Account sales charged to Agts. |
|
600.00 |
| Shipment Ledger Account decreased |
|
100.00 |
| Sundry expenses paid in cash |
|
50.00 |
| |
| Inventory at end of period |
|
|
| Apples |
210.00 |
|
| Potatoes |
190.00 |
400.00 |
Prepare trading and profit and loss accounts showing net profits
or losses on both apples and potatoes for the entire period represented
by the accounts.
77
49. The books required by a produce commission merchant are
receiving book, cash book, consignment ledger, sales book, sales ledger,
journal, and general ledger. If he buys produce to be sold on his own
account, he also requires a purchase book and purchase ledger.
50. The Receiving Book. This is usually a rough blotter with
ordinary day book ruling, though some merchants use special forms.
When a consignment is received it is given a lot number and
entered in this book in the name of the shipper, but without extending
the amounts. If any expenses have been incurred, an account is
opened immediately in the consignment ledger in the name of the
shipper.
51. The Cash Book. On the credit side of the cash book, under
the general heading consignment ledger, are three columns, headed
net proceeds, expense, and commission. The commission column
is a memorandum column only, the total being posted, at the end of
the month, to the credit of commission account in the general ledger.
Net proceeds, expense, and commission on each consignment
are posted as separate items to the debit of that particular consignment
account. At the end of the month, the total of these three
columns is posted to the debit of consignment ledger account in the
general ledger.
52. Sales Book. The sales book is provided with special
columns for sales and consignment sales. The sales column represents
sales of the merchants' own goods, the totals being posted
at the end of the month to the credit of sales account in the general
ledger and to the debit of the sales ledger account.
The consignment sales are listed by lot number and posted to
the credit of the consignment accounts. As the lot numbers run
consecutively in the receiving book, this furnishes an index to the
consignment accounts. The totals of the consignment sales columns
are posted to the credit of consignment ledger account, and the consignment
ledger column is posted to the debit of sales ledger account.
53. Consignment Ledger. This ledger contains accounts
with every consignment received. The accounts are charged with
expenses, net proceeds, and commissions from the cash book, and
credited with sales from the sales book. If a remittance is not sent
with the Account Sales, the necessary entry is made in the journal,
78charging both consignment account and consignment ledger account
and crediting the shipper as principal—or bills payable account when
a note is sent.
54. Consignment Ledger Account. This is a controlling account
which receives its debits and credits from the same sources
as do the consignment accounts. Except in the case of journal
entries, totals only are posted at the end of the month.
55. When the commission merchant is also a wholesaler, the
purchases and sales are treated on the books exactly as they would
be if he was not a commission merchant. The books and accounts
required are the same as those of any other wholesale merchant.
56. The following transactions include the shipments used in
the last model set, but treated from the standpoint of the commission
merchant.
| —Nov. 3, 1908— |
| Received from John Doe to be |
|
| sold for his account: |
|
| 220# chickens |
|
| 98# ducks |
|
| Lot No. 1 |
|
| |
| —4th— |
| Received from John Doe to be |
|
| sold for his account |
|
| 95 cs. eggs, 2,850 doz. |
|
| Lot No. 2. |
|
| |
| —4th— |
| Sold for cash |
|
| 100# chickens (Lot 1) @ .16 |
$16.00 |
| |
| —4th— |
| Sold to Sweet & Co. on a/c |
|
| 110# chickens (Lot 1) @ .16 |
17.60 |
| |
| —4th— |
| Sold for cash |
|
| 100# ducks (Lot 1) @ .17¼ |
17.25 |
| |
| 79 —4th— |
| Paid expense on lot #1 |
$1.60 |
| |
| —4th— |
| Rendered Account Sales, with |
|
| remittance for Lot #1, commission 3% |
|
| |
| —5th— |
| Sold for cash |
|
| 20 cs. eggs., 600 doz., @ .18 (Lot 2) |
108.00 |
| |
| —5th— |
| Sold to Gaston & Co., 156 Hammond St. |
|
| 20 cs. eggs., 600 doz., @ .20 (Lot 2) |
120.00 |
| |
| —5th— |
| Sold to Francis & Gates, 948 37th St. |
|
| 30 cs. eggs, 900 doz., @ .19 (Lot 2) |
171.00 |
| |
| —5th— |
| Sold to H. B. Niles, 364 Fuller Ave. |
|
| 25 cases eggs, 750 doz. @ .19 (Lot 2) |
142.50 |
| |
| —5th— |
| Paid expense on Lot #2 |
7.13 |
| |
| —5th— |
| Rendered account sales for |
|
| Lot #2, commission 3%, crediting |
|
| amount to shippers' account. |
|
| |
| —5th— |
| Received from John Doe to be |
|
| sold for his account |
|
| 200# Turkeys |
|
| Lot #3 |
|
| |
| —5th— |
| Paid expense on Lot #3 |
1.25 |
80
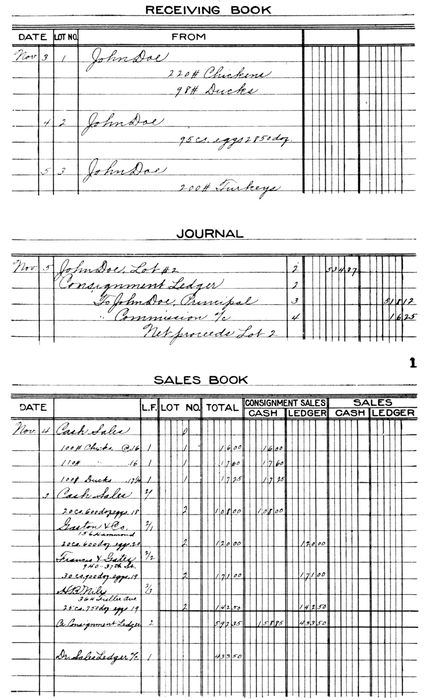
Commission Merchant's Receiving Book, Journal and Sales Book
81
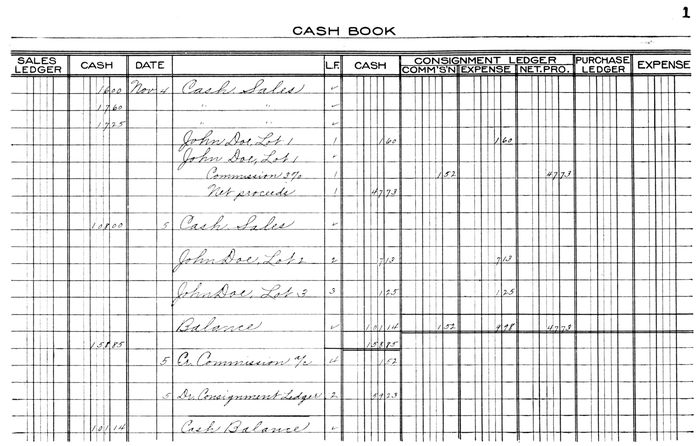
Commission Merchant's Cash Journal
82
Commission Merchant's Consignment and Sales Ledgers
83
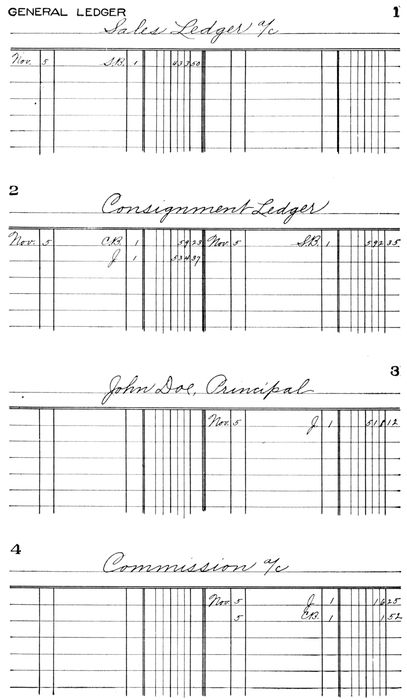
Commission Merchant's General Ledger
84
57. During a certain period a commission merchant transacted
the following business:
| Purchased goods on his own account |
$3,000.00 |
| Sold goods on commission |
5,000.00 |
| Sold his own goods |
2,500.00 |
| Commissions earned |
150.00 |
| Received cash for goods sold |
6,250.00 |
| Paid expenses on consignments |
37.50 |
| Rendered account sales with which cash was |
|
| remitted to cover net proceeds |
2,712.50 |
| Rendered account sales on which net proceeds |
|
| were credited to the account of principals |
2,000.00 |
| Paid cash on account of goods purchased |
2,200.00 |
| Paid cash for sundry expenses |
75.00 |
| Inventory of goods owned at the close of the period |
800.00 |
Prepare trading and profit and loss accounts and balance sheet.
58. Storage, as here used, is the business of furnishing storage
for merchandise on its way to market until such time as it is sold and
delivered to the purchaser. The source of supply and customs of the
trade in certain classes of merchandise render the question of storage
an important one. This is particularly true of the grain trade.
Large buyers of grain, located in important distributing centers which
have become the principal grain markets owing to their manufacturing
or transportation facilities, locate their buyers in the grain producing
sections to buy grain from the producers. At these points are located
small grain handling plants or elevators, where the grain is received
from the farmers and shipped to the distributing centers.
Here, extensive storage facilities must be provided, that these
shipments, aggregating enormous quantities of grain, may be held
until the condition of the market is favorable for selling. If it were
not for this custom of storage it would be necessary to market all of
the grain—except the small quantities stored by the farmers—soon
after harvest, which would result in lowering prices to all concerned,
from the farmer up.
85These conditions have resulted in the organization of warehousing
companies to provide storage for the owners. When grain,
or other classes of merchandise, is received for storage a warehouse
receipt is issued, and the merchandise will not be delivered without
the presentation of the receipt. Warehouse receipts are negotiable
and since they are evidence of the ownership of certain merchandise
stored in a warehouse, bankers will loan money to the owner and
accept the warehouse receipt as security.
Manufacturers and jobbers of certain products also find it necessary
to store large quantities of their wares at distributing centers
that they may promptly supply the trade. Another reason for this
practice is a financial one. When a manufacturer exchanges his
wares for a warehouse receipt, he can immediately borrow on its
security, thus securing capital to carry on his business until the regular
selling season for his particular product.
The merchandise broker and manufacturers' agent sometimes
have their own warehouses and combine the business of buying and
selling with that of storage and, if they possess sufficient capital,
advance money to the manufacturer.
Perishable products handled by the produce commission merchant
are also stored in cold storage warehouses, both to preserve
them and to hold for more favorable market conditions.
59. Storage charges are usually based on a 30 day period,
though sometimes for shorter periods, and any period less than a full
month is charged for at the 30 day rate.
The storage is frequently charged for the exact time that goods
are in the warehouse, that is, the amount is figured for each amount
withdrawn. The following example demonstrates this, storage
being charged on each quantity withdrawn at the rate of 10c per
case per month.
| Received |
Delivered |
Time |
Rate |
Amount |
| Nov. |
15 |
600 cs. eggs |
Dec. |
10 |
100 cs. |
1 mo. |
10c |
10 |
00 |
| |
|
|
|
|
|
|
|
|
|
| |
|
|
Jan. |
6 |
300 cs. |
2 mo. |
20c |
60 |
00 |
| |
|
|
|
|
|
|
|
|
|
| |
|
|
Feb. |
14 |
200 cs. |
3 mo. |
30c |
60 |
00 |
| |
|
|
|
|
Total |
|
|
130 |
00 |
86This is known as simple storage.
Another method is to charge storage for the average time at a
given rate per month of 30 days. This method is most commonly
used when receipts and deliveries are frequent, and is called average
storage. The following example demonstrates the method.
| Date |
Receipts |
Deliveries |
Balance |
Time |
Quantity Stored For One Day |
| Nov. |
15 |
600 cs. |
|
600 cs. |
15 da. |
9,000 |
cs. |
| Nov. |
30 |
200 " |
|
800 " |
10 da. |
8,000 |
" |
| Dec. |
10 |
|
100 cs. |
700 " |
27 da. |
17,900 |
" |
| Jan. |
6 |
|
300 " |
400 " |
39 da. |
15,600 |
" |
| Feb. |
14 |
|
200 " |
200 " |
10 da. |
2,000 |
" |
| Feb. |
24 |
|
200 " |
000 " |
|
|
|
| |
|
800 |
800 |
|
|
30)52,500 |
|
| Average for 1 mo. |
1,750 |
|
| 1,750 cs. @ 10¢ $175.00 (Amt. of charges) |
60. One of the most important records required is a storage
record showing receipts and deliveries. A special form is necessary
and should be adapted to the requirements of the particular class of
storage business in which it is to be used.
The form illustrated is typical in that it provides for a record
of storage of any class of goods handled in packages. The storage
charges are always shown so that a statement of the account can be
made at any time. At the end of each month the storage charges
extended during the month are debited, through the journal, to the
personal accounts of the owners. The total of all such storage
charges is credited to a storage account in the general ledger.
When there are frequent receipts and deliveries, the owner
should be given a detailed statement showing all changes in quantities
and storage charges. Such a statement should be a transcript of
the storage record. The form illustrated answers the requirements
of simple storage.
87
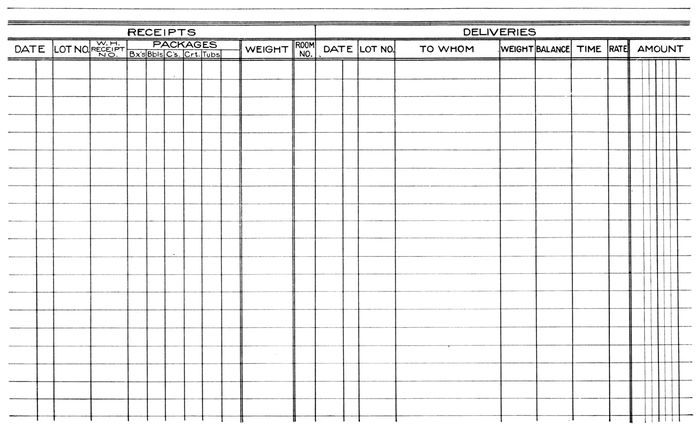
88
Statement of Storage Charges
90
BIRD'S-EYE VIEW OF THE PLANT OF SWIFT & COMPANY, CHICAGO, ILL.
SINGLE ENTRY BOOKKEEPING COMPARATIVE STATEMENTS [3] — SINGLE ENTRY BOOKKEEPING — SAMPLE TRANSACTIONS — DETERMINING THE PROFIT — CLOSING THE BOOKS — EXERCISE — CHANGING TO DOUBLE ENTRY — EXERCISE — CHANGING PARTNERSHIP BOOKS TO DOUBLE ENTRY — EXERCISE — CHANGING CORPORATION BOOKS TO DOUBLE ENTRY — EXERCISE — TRIAL BALANCES AND COMPARATIVE STATEMENTS — WORKING BALANCE SHEET — EXERCISE — COMPARATIVE STATEMENTS — PROOF WITHOUT A TRIAL BALANCE — BOOK INVENTORIES — DEMONSTRATION OF PROOF WITHOUT A TRIAL BALANCE — REVERSE OR SLIP POSTING — SPECIAL ACCOUNTING FORMS — SPECIAL LEDGERS — CASH BOOKS — TABULAR SALES BOOKS — PAY-ROLL RECORDS
91
1. To this point all of the discussions in this work have related
to the double entry system of bookkeeping, and all demonstrations
have been carried out according to that system. The reason for this
is that double entry is the best and the only satisfactory method of
bookkeeping; it is the only method that fulfils the important function
of bookkeeping by furnishing a true record of the results of all business
transactions.
It might appear that instruction in keeping books by the single
entry method has no place in a modern treatise on bookkeeping; and
if our purpose were to teach single entry as a method to be used,
this would be true.
Single entry bookkeeping is not recommended as a method to be
used in any business.
The only reason for introducing single entry is to show the
student how to change a set of books from the antiquated single
entry to a modern double entry system. Though inadequate, single
entry is still used to some extent. It is more commonly found in
small retail establishments, but occasionally encountered in the
offices of corporations and manufacturing enterprises. The bookkeeper
who is called upon to fill a position where this method is used
must know how to keep books by single entry, that he may more
clearly demonstrate the advantages of the double entry method.
When the advantages of double entry are demonstrated, few
employers will object to a change from single entry. In most offices
where single entry is still used, the reasons which have prevented a
change may be summed up as ignorance of the double entry
method, or a fear that double entry will increase the work without
a corresponding benefit. This latter idea is a misconception inherited
92from the days of the old time bookkeeper, who considered it necessary
to laboriously journalize every transaction. While it may have
possessed some merit at that time, it is no longer true. Modern ideas,
improved forms of account books, labor saving devices, and short
cuts without number have reduced the labor of bookkeeping to a
minimum, and if any attempt at a proof of accuracy is made, double
entry actually requires less labor than single entry.
2. Distinctive Features of Single Entry. The distinctive feature
of single entry is that only personal accounts are kept. When
goods are sold or purchased, records are made of the transactions
as they affect the persons to whom sold or from whom purchased.
The records do not show the increase or decrease of any specific
form of assets, like merchandise, for no property accounts are kept.
An account is usually kept with cash, but this approaches double
entry, for when a person pays money to the business, cash is debited
and the person credited; and when money is paid out, cash is credited
and the person debited.
Sometimes, in a set of books otherwise kept by single entry, such
accounts as merchandise, expense, and real estate are found, but
when such accounts are introduced the books begin to take on double
entry features.
3. Books Used. The principal books of a single entry set
usually consist of day book or journal, cash book, and ledger.
Both the day book and cash book are books of original entry, from
which transactions are posted direct to the ledger. Auxiliary books
used are order book, bill book, and check book.
The day book or journal is the familiar two-column form, the left-hand
column being used for debits and right-hand column for credits.
The cash book has two columns on each page, and these columns
are used to separate the items affecting personal accounts, which are
to be posted, and all other items, none of which are posted. See
illustration.
The ledger is the same form as used in the double entry method.
The order book is usually the regular two-column journal form.
In retail businesses it is used as a principal book, transactions being
posted from it to the ledger. Sometimes the first column is used for
prices, the extensions being made only when the order is filled.
The bill book is quite essential in a single entry set for the reason
93that no Bills Receivable and Bills Payable accounts are kept
in the ledger.
4. Rules for Debit and Credit. The rules for debit and credit
are the same in single entry as in double entry, except that no debits
and credits are recorded which do not effect persons or cash—when
a cash account is kept. Briefly, these rules applying to single
entry are:
- Debit the person
- When he receives anything of value;
- When you pay him cash.
- Credit the person
- When you receive anything of value;
- When he pays you cash.
- Debit cash
- When you receive it.
- Credit cash
- When you part with it.
5. Posting. There is no difference between posting to a single
entry ledger and one kept by the double entry method. However, the
only accounts posted are personal accounts, and the ledger shows merely
how much money the business owes to persons and how much
money persons owe the business. A single entry ledger does not show
the amount of our notes outstanding, or the amount of other persons'
notes held by us. This information can be found only in the bill
book. The ledger does not show the value of merchandise purchased
or sold, expenses of the business, nor the amount of our investments
in land, buildings, or other forms of property.
6. Proprietor's Account. A proprietor's investment or capital
account is kept in single entry just as it is in double entry. This
may or may not include withdrawals. They may be recorded in a
personal or private account, in which case the proprietor's account
will exhibit the net investment in the business.
7. Proving the Work. Since but one side of each journal
entry is posted, the two sides of the ledger will not agree as in double
entry. Hence a trial balance is, strictly speaking, impossible. The
only absolutely sure method of checking the accuracy of a single
account in the ledger is to carefully check all postings; this is also
true of double entry. But it is possible to prove that the correct totals
have been posted in single entry, as it is in double entry. Since
94the ledger is never in balance as in double entry, the proof is not found
by comparing the two sides of the ledger, but by comparing the difference
between the two sides of the ledger, with the difference between
debits and credits in the columns of books of original entry from
which postings have been made. If the difference between debits
and credits in the ledger agrees with the difference between debits
and credits in the books of original entry, the work may be assumed
to be correct.
To prove the work, first find the balances of all ledger accounts
and enter the amounts in the debit and credit columns on journal
paper—as for a trial balance. Foot and find the difference between
the two columns. Next foot the order book, day book, cash book,
or any other books from which posting is done, and list the totals
which should be posted to debit and credit of ledger accounts. Foot
and find the difference.
8. For the first demonstration of single entry bookkeeping, we
have selected a small retail business, using transactions which have
been used to illustrate a double entry set. This set is kept in the most
simple manner possible, the books used being journal, cash book,
and ledger.
The business is opened by Wm. Webster on the 21st day of
November, 190-. He is to conduct a retail grocery business and has
rented a store from Wm. Bristol at a monthly rental of $30.00. His
resources consist of cash, $600.00; a stock of groceries, $946.50; personal
accounts due him as follows: Henry Norton $25.00, L. B.
Jenkins $22.70. His liabilities consist of two accounts, as follows:
Brewster & Co., $115.20; Warsaw Milling Co., $64.00. The opening
entry recording the above, is made in the journal as in double entry,
but only personal items are posted. Cash is transferred to the cash
book.
CUTTING OFF DEPARTMENT IN THE PLANT OF THE UNION TWIST DRILL CO., ATHOL, MASS.
| 95 |
| |
| —Nov. 21— |
| Sold to Henry Norton on account |
|
| 10# sugar |
5½¢ |
$.55 |
| 2 cans corn |
|
.25 |
| 1 can peas |
|
.15 |
| 3# rice |
|
.30 |
| |
|
|
| |
|
1.25 |
| |
| —21— |
| Sold to John Smallwood on account |
|
| 5# butter |
|
$1.00 |
| 4# lard |
|
.50 |
| 1 doz. eggs |
|
.25 |
| |
|
|
| |
|
1.75 |
| |
| —21— |
| Cash sales |
|
14.10 |
| |
| —22— |
| Sold to Harry Webster on account |
|
| 7 bars Lenox soap |
|
.25 |
| 1 pkg. gold dust |
|
.20 |
| 1 pkg. matches |
|
.15 |
| ¼ bbl. flour |
|
1.35 |
| |
|
|
| |
|
1.95 |
| |
| —22— |
| Bought for cash |
|
| 10 doz. eggs |
.21 |
2.10 |
| |
| —23— |
| Bought from H. Kling & Co. on account |
|
| 244# hams |
.12½ |
22.50 |
| 201# lard |
.07½ |
15.08 |
| |
|
|
| |
|
45.58 |
| |
| —23— |
| Sold to F. W. Bradley on account |
|
| 2 bu. potatoes |
|
1.60 |
| |
| —23— |
| Sold to C. D. Glover on account |
|
| 1 bbl. apples |
|
3.25 |
| 5 gal. vinegar |
|
1.25 |
| |
|
|
| |
|
4.50 |
| |
| —23— |
| Cash sales |
|
13.20 |
| |
| 96—24— |
| Sold to A. C. Maybury on account |
|
| 1# bkg. powder |
|
$.50 |
| 1# corn starch |
|
.10 |
| 1# soda |
|
.10 |
| 1 pkg. jello |
|
.20 |
| |
|
|
| |
|
.90 |
| |
| —24— |
| Sold to John Smallwood on account |
|
| 2# cheese |
|
.32 |
| 1 bottle vanilla |
|
.35 |
| 1# coffee |
|
.35 |
| 1# tea |
|
.60 |
| |
|
|
| |
|
1.62 |
| |
| —24— |
| Bought from John Smallwood on account |
|
| 100 bu. potato |
.60 |
60.00 |
| |
| —24— |
| Paid John Smallwood |
|
| Cash on account |
|
25.00 |
| |
| —24— |
| Cash sales |
|
15.00 |
| |
| —25— |
| Paid Brewster & Co. |
|
| Cash on account |
|
115.20 |
| |
| —25— |
| Sold to L. B. Jenkins on account |
|
| ½# pepper |
|
.20 |
| 12# ham |
.14 |
1.68 |
| |
|
|
| |
|
1.88 |
| |
| —25— |
| Received from Henry Norton |
|
| Cash |
|
26.25 |
| |
| —25— |
| Cash sales |
|
13.00 |
| |
| 97—26— |
| Credited Wm. Bristol |
|
| for one month's rent |
|
$30.00 |
| |
| —26— |
| Sold to Wm. Bristol on account |
|
| 11# ham |
.14 |
1.54 |
| 1 qt. bottle olives |
|
.50 |
| 2# coffee |
|
.70 |
| 20# sugar |
.05½ |
1.10 |
| |
|
|
| |
|
3.84 |
| |
| —26— |
| Sold to C. D. Glover on account |
|
| ¼ bbl. flour |
|
1.35 |
| 1# bkg. powder |
|
.50 |
| 7 cks. borax soap |
|
.25 |
| |
|
|
| |
|
2.10 |
| |
| —26— |
| Paid cash for clerk hire |
|
8.00 |
| |
| —26— |
| Cash sales |
|
18.70 |
| |
| —28— |
| Sold to H. N. Shaw on account |
|
| 1 bu. potatoes |
|
.80 |
| 1 doz. cans corn |
|
1.50 |
| |
|
|
| |
|
2.30 |
| |
| —28— |
| Sold to Watkins Hotel Co. on account |
|
| 10 bu. potatoes |
.75 |
7.50 |
| 50# lard |
.10 |
5.00 |
| 20# ham. |
.13½ |
2.70 |
| |
|
|
| |
|
15.20 |
| |
| —28— |
| Cash sales |
|
9.45 |
| |
| 98—29— |
| Bought from Lowell & Sons on account |
|
| 500# sugar |
.04¾ |
$23.75 |
| 50 gal. molasses |
.30 |
15.00 |
| |
|
|
| |
|
38.75 |
| |
| —29— |
| Bought from Star Salt Co. on account |
|
| 10 bbls. salt |
.80 |
8.00 |
| |
| —29— |
| Sold to R. H. Sherman on account |
|
| 1# coffee |
|
.25 |
| 1# chocolate |
|
.45 |
| 1 qt. olive oil |
|
1.35 |
| ¼# ginger |
|
.15 |
| ¼# pepper |
|
.15 |
| 1 pkg. mince meat |
|
.10 |
| 2# lard |
|
.25 |
| |
|
|
| |
|
2.70 |
| |
| —29— |
| Cash sales |
|
14.35 |
| |
| —30— |
| Received from F. W. Bradley on account |
|
| Cash |
|
1.60 |
| |
| —30— |
| Paid Warsaw Milling Co. on account |
|
| Cash |
|
64.00 |
| |
| —30— |
| Sold to John Smallwood on account |
|
| 1 bbl. salt |
|
1.10 |
| |
| —30— |
| Sold to D. E. Johnson on account |
|
| 10# lard |
.10 |
1.00 |
| 1# bkg. powder |
|
.50 |
| 1 pk. apples |
|
.35 |
| |
|
|
| |
|
1.85 |
| |
| 99—30— |
| Bought for cash |
|
| 5 bu. apples |
1.00 |
$5.00 |
| |
| —30— |
| Cash sales |
|
17.90 |
At the close of business, Nov. 30, the ledger is proved, in accordance
with the rules given in Art. 7. All open accounts in the
ledger are listed on ordinary journal ruled paper and the balances
extended to the debit and credit columns. These columns are footed,
the total of the credit columns being $1,564.02, and of the debit
column, $56.08. Subtracting the latter from the former, we find the
difference to be $1,507.94. The total postings—debit and credit—from
the journal and the cash book are then entered and added, the
total debit postings being $296.44, and the total credit postings,
$1,804.38. The former deducted from the latter leaves $1,564.02,
which agrees with the difference in the ledger balances. This proves
the correctness of the postings to the ledger, and takes the place of
the trial balance used in the double entry method.
100
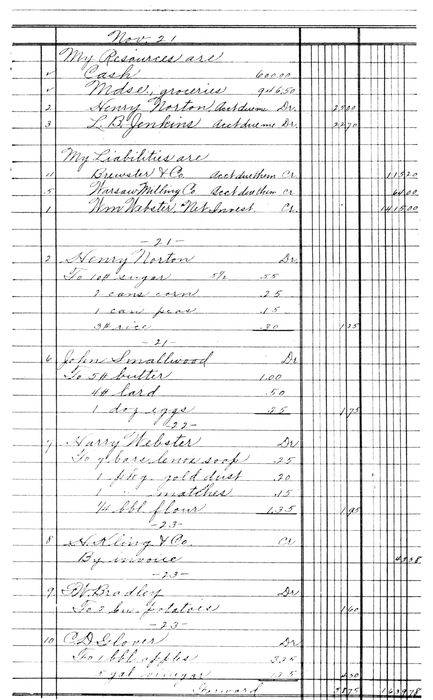
101
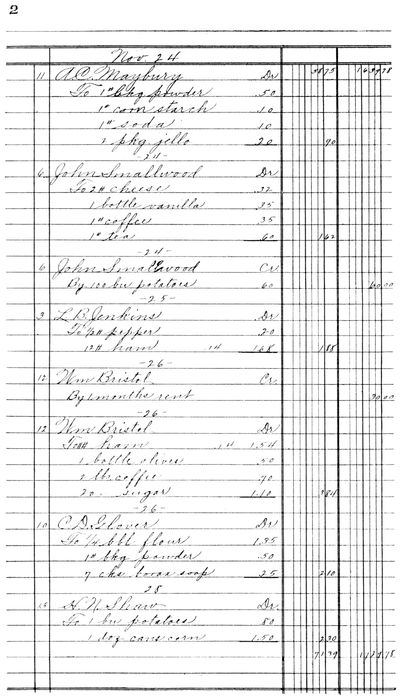
102
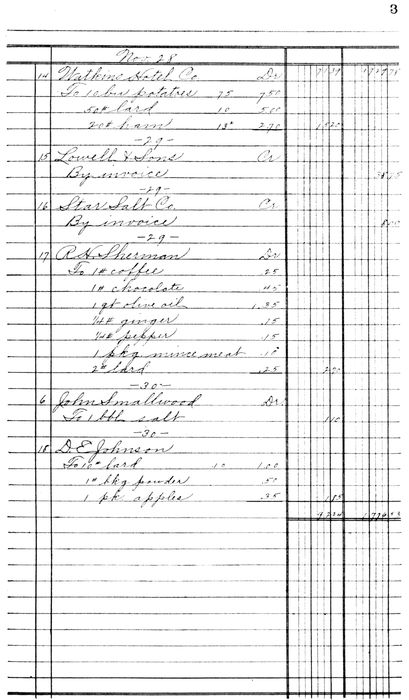
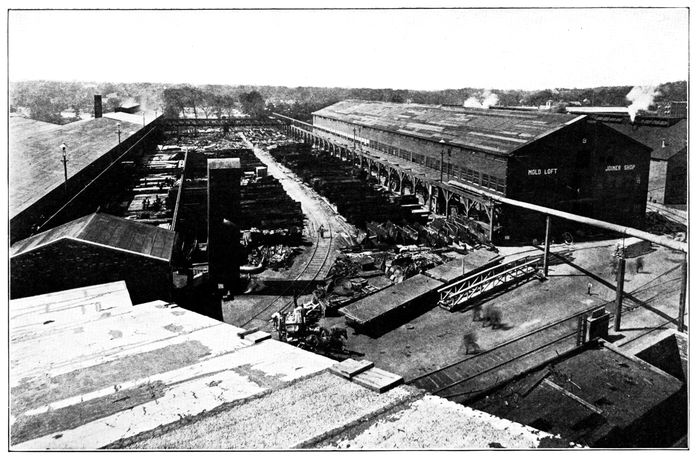
VIEW IN THE GROUNDS OF THE FORE RIVER SHIPBUILDING COMPANY, QUINCY, MASS.
Showing the Facilities for Handling Material in the Plate Yard and a Typical Arrangement of the Shops. The Great Electric Crane Shown has a Span of 175 Feet, and Travels Over 1,000 Feet of Track. It is Said to be One of the Largest of Its Kind in the World.
103
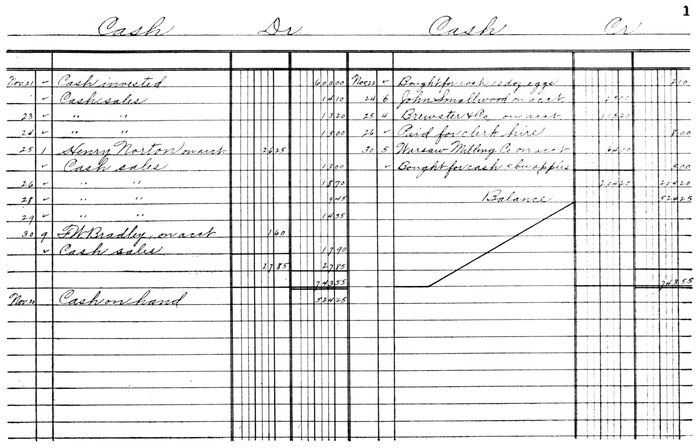
104
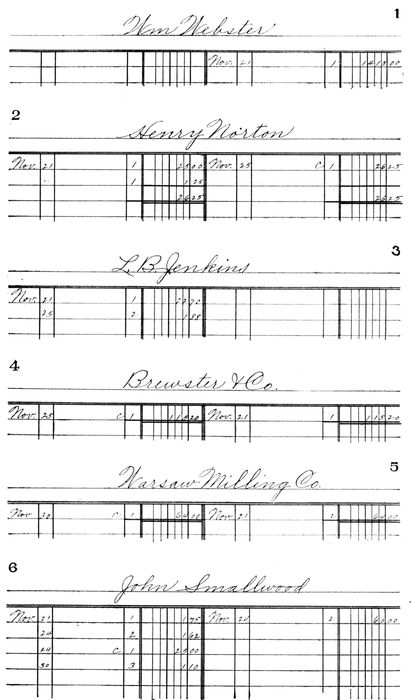
105
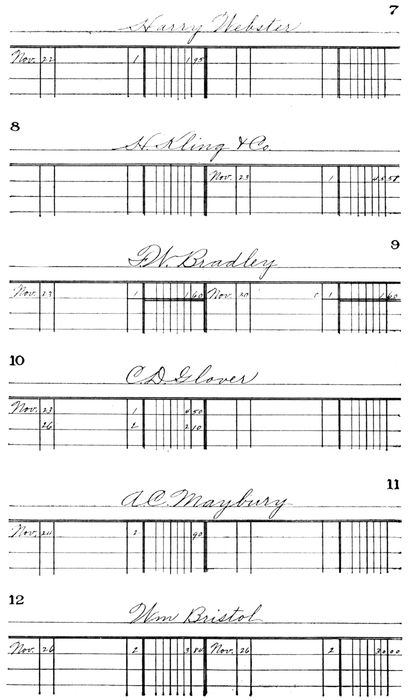
106
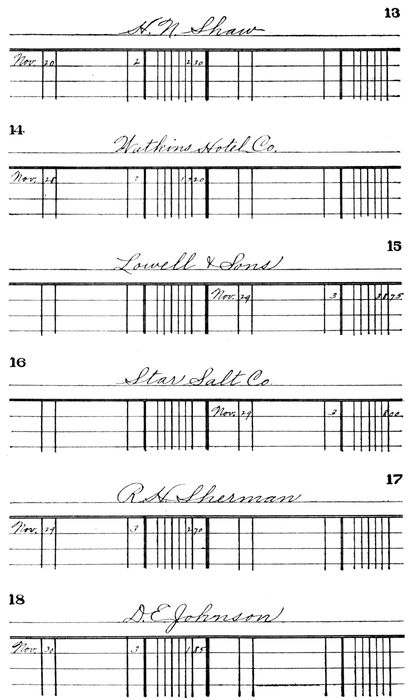
AUTOMATIC MACHINE TOOL ROOM, FOR THE MANUFACTURE OF PARTS FOR ROCK DRILLS, COAL MINING MACHINES, DIAMOND DRILLS, ETC., IN THE CLAREMONT, N. H., FACTORY OF THE SULLIVAN MACHINERY COMPANY
107
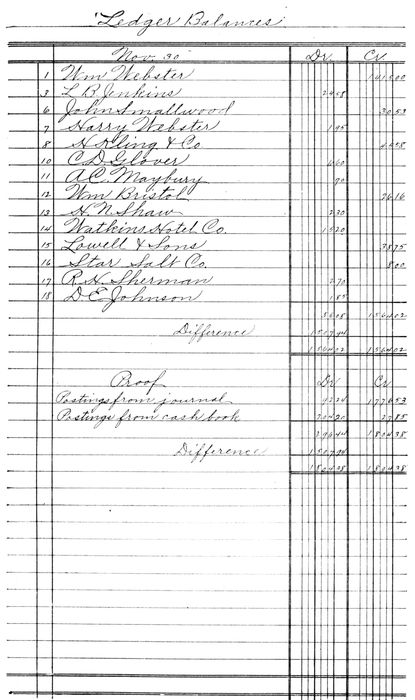
Proof of Single Entry Ledger
108
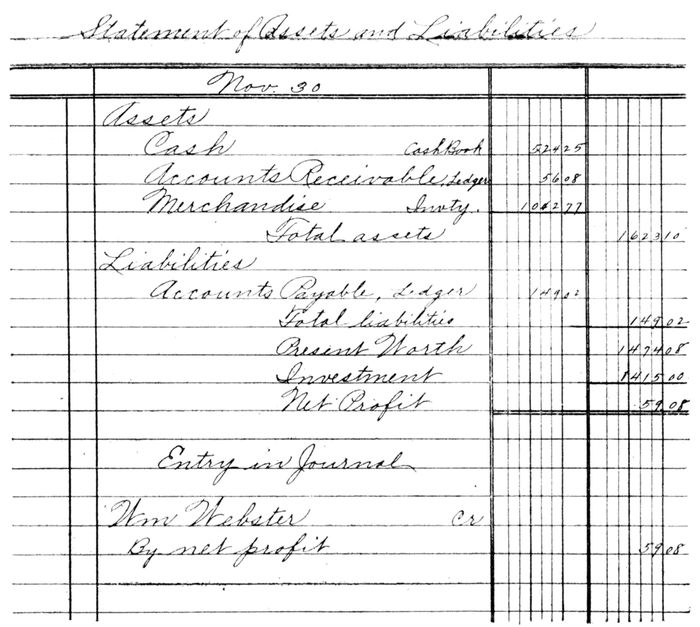
Single Entry Profit and Loss Statement
9. Having no nominal accounts, we cannot close through trading
account into profit and loss, but must use another method to find
the profit or loss for a given period. It will be necessary to first
ascertain the present worth of the business. Therefore the first step
will be to take an inventory, just as we would if closing a double entry
ledger. Our inventory shows merchandise $1,042.77. Next, we will
make a statement of assets and liabilities, following the same form
as the balance sheet when the books are kept by double entry. This
will give us the present worth.
From the present worth, we will deduct the capital investment
(or the present worth at the time of making the last statement) which
will show the profit for the period. If the present worth is less than
the capital investment, the business shows a loss.
It will be noted that while this method shows net profits, it does
not show how those profits were made. Having no accounts with
purchases and sales, we can have no trading account to show gross
109profits, and without expense accounts there is no data from which
to make up a detailed profit and loss statement. Herein is one of the
shortcomings of the single entry method of bookkeeping.
10. To close a single entry ledger, all that is necessary is to
credit the proprietor's investment account, or any account representing
capital, with the net gain, or debit the account with the net loss.
Then rule the personal accounts and bring down the balances.
On a certain date the assets and liabilities of David Henry are
as follows:
| Assets |
|
| Cash |
$450.00 |
| Due from sundry debtors |
75.20 |
| Merchandise per inventory |
762.50 |
| Liabilities |
|
| Due sundry creditors |
144.00 |
The following transactions are recorded:
| Sales to sundry persons on account |
44.71 |
| Bought from sundry persons on account |
337.54 |
| Sold for cash |
94.90 |
| Received cash on account |
62.00 |
| Paid cash on account |
132.50 |
| Paid cash for rent |
35.00 |
| Paid cash for clerk hire |
7.00 |
At the close of the period in which these transactions were recorded,
the inventory of merchandise on hand was $987.75.
First. Open single entry books, entering these transactions in
the journal and cash book.
Second. Post to ledger using the terms Debtor and Creditor to
represent account of customers and those from whom goods were
purchased.
Third. Prove the ledger.
Fourth. Make a statement of assets and liabilities.
Fifth. Has there been a gain or a loss, and how does it affect
the account of the proprietor?
110
11. How to change the method of keeping a set of books from
single to double entry is an important question to the bookkeeper,
for he may be called upon any time to do the work. When once
understood, the change involves only very simple entries. The routine
may be briefly described as follows:
First. Prepare a statement of assets and liabilities.
Second. Enter this statement in the journal and post to the ledger,
debiting all accounts which represent assets and crediting all accounts
which represent liabilities. Credit proprietor's account with the difference,
which is the present worth.
If a new ledger is to be opened, new accounts will be opened
for each form of asset or liability represented in the entry.
If the old ledger is to be used new accounts are to be opened
with assets and liabilities not already represented by accounts in the
ledger, and the net gain only will be credited to the proprietor's
account. Check personal accounts, but do not post.
Third. Take a trial balance to see if the ledger is in balance,
as it should be after posting these entries.
Following the rules given, change the books of David Henry
to double entry using the old ledger.
Show necessary journal entry and indicate what new accounts
must be opened.
12. We will suppose that the ledger illustrated in the following
model set (pages 23-27) represents the business of Benton, Douglas,
and Kemp, and that the books have been kept by single entry.
They wish to adopt the double entry method and call you in to
make the necessary changes in their books.
Your first step is to make a statement of the ledger accounts,
including all except the capital accounts of the partners. This
statement gives you the following information:
| Personal Accounts, Debit Balances |
$189.25 |
| Personal Accounts, Credit Balances |
2,828.50 |
| Cash in Bank |
7,313.73 |
111You also balance the cash book and compare the balance with
the cash in drawer, and find that the amount shown, $21.60, is correct.
In the meantime an inventory is being taken. When completed,
the results shown are:
| Merchandise |
$2,114.50 |
| Furniture and Fixtures |
2,000.00 |
The next step is to make a statement of assets and liabilities for
the purpose of finding the present worth of the business.
| STATEMENT OF ASSETS AND LIABILITIES |
|---|
| |
| Assets |
|
|
| Cash in Bank (Ledger) |
$7,313.73 |
|
| Cash in Office (Cash Book) |
21.60 |
|
| Personal Accounts (Ledger) |
189.25 |
|
| Merchandise (Inventory) |
2,114.50 |
|
| Furniture and Fixtures (Inventory) |
2,000.00 |
|
| |
|
|
| Total Assets |
|
$11,639.08 |
| |
| Liabilities |
|
|
| Personal Accounts (Ledger) |
|
2,828.50 |
| |
|
|
| Present Worth |
|
8,810.58 |
The capital accounts of the partners show the original investment
to have been $9,000.00, which is more than the present worth. Deducting
the latter from the former will give the net loss.
| Investment |
$9,000.00 |
| Present Worth |
8,810.58 |
| |
|
| Net Loss |
189.42 |
The partnership agreement provides that profits and losses are
to be shared equally, but contains no reference to the payment of
interest on withdrawals, or allowance of interest on personal credits.
The statement of assets and liabilities is entered in the journal
and accounts opened in the ledger with merchandise inventory and
furniture and fixtures—the only items not already represented by
ledger accounts. To complete the change and balance the ledger
the following single entry is made in the journal and posted to partners'
personal accounts.
| 112 |
| James Benton |
Dr. |
$63.14 |
| Horace Douglas |
Dr. |
63.14 |
| Henry Kemp |
Dr. |
63.14 |
A trial balance will now show the ledger to be in balance.
You have followed the routine necessary to change the books
of a partnership from single to double entry under the conditions
given. A general rule to be followed is to ascertain the present
worth, make the partnership adjustment as in double entry, and post
as in changing books of a single proprietorship.
The books of Lancaster, Jenkins, and Stubb have been kept by
single entry, but they desire to change to double entry.
The partnership agreement provides that each partner shall
share in the profits in proportion to his net investment. Separate
accounts are kept with each partner to cover his investment and
withdrawals.
The following is a statement of the ledger accounts as they
appeared December 31st. The balances of partners' investment
accounts are the same as when the last adjustment was made, no
additional investments having been made during the present period.
| STATEMENT OF LEDGER |
|---|
| |
| Lancaster, |
Investment |
Credit |
Balance |
$2,000.00 |
| Jenkins |
" |
" |
" |
1,500.00 |
| Stubb |
" |
" |
" |
1,500.00 |
| Personal |
Accounts |
" |
" |
900.00 |
| " |
" |
Debit |
" |
2,200.00 |
| Lancaster, |
Withdrawals |
" |
" |
325.00 |
| Jenkins |
" |
" |
" |
250.00 |
| Stubb |
" |
" |
" |
175.00 |
| Bank |
" |
" |
" |
2,150.00 |
| Cash in office |
|
|
50.00 |
An inventory is taken and shows the value of merchandise in
stock to be $1,850.00, fixtures $300.00.
First. Transfer debit balances of partners' withdrawal accounts
to investment accounts.
Second. Show entries to make the partnership adjustment and
to change books to double entry.
Third. Indicate by check (√) what accounts are to be posted,
the old ledger being used.
113
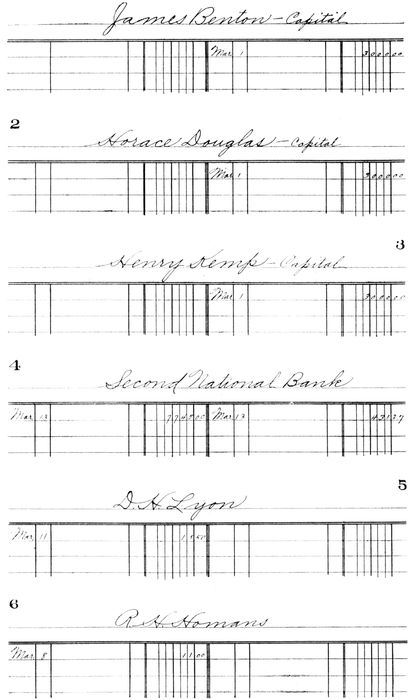
Single Entry Partnership Ledger
114
Single Entry Partnership Ledger
115
Single Entry Partnership Ledger
116
Single Entry Partnership Ledger
117
Single Entry Partnership Ledger
118
13. Corporation books are seldom kept by single entry, but
such cases are not impossible to find. In Chicago, there is a manufacturing
corporation which has been in business for more than
twenty years and is doing a business of a quarter million dollars a
year, whose books have been kept by single entry. Not until January
1909 was an accountant called in to change their books to a modern
double entry system.
In the case cited a capital stock account was kept, and dividends
were paid in cash. The routine followed by the accountant was to
first take an inventory of machinery, material, supplies, goods in
process, and manufactured goods. Then the land and buildings were
appraised at their present value. Accounts had been kept with real
estate and machinery, but repairs to buildings had been charged to
real estate, thus showing a fictitious increase in value, and no depreciation
had been charged against machinery. There was also a
merchandise account which had been charged with all purchases
and credited with all sales, so that it furnished no information of
value.
For these reasons only personal accounts, capital stock, bank
account, and cash were taken from the books in making up a statement
of assets and liabilities. In making this statement capital stock
was included as a liability and the excess of assets over liabilities
represented surplus.
The statement was entered in the journal and accounts representing
each item were opened in a new ledger. The balance was
credited to surplus account and the books were in balance. Subsequently,
the different expense accounts were opened as the transactions
requiring their use arose.
Had the directors insisted, the accountant would have been
obliged to enter real estate and machinery at the values shown in the
old accounts, but an inventory of merchandise would have been
necessary in any event.
A safe rule in changing the books of a corporation to double entry
is to make a statement of assets and liabilities, including capital
stock in liabilities. Then open the necessary accounts and credit
the difference in the statement to surplus account.
119
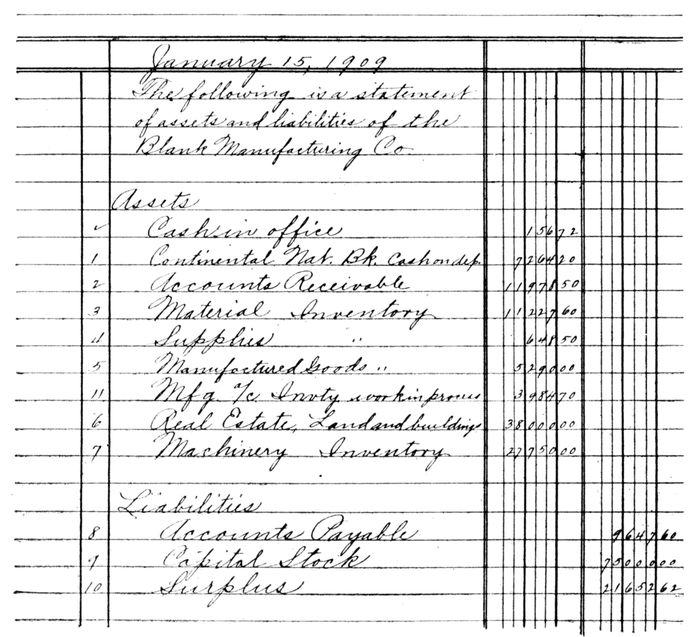
Journal Entries to Change to Double Entry
In the case referred to the following facts were shown by the
books:
| Cash in Office |
$156.72 |
| Cash in Bank |
7,264.20 |
| Accounts Receivable |
11,978.50 |
| Accounts Payable |
9,647.60 |
| Capital Stock |
75,000.00 |
The inventories and appraisals resulted in the following valuations:
| Real Estate (Land and Buildings) |
$38,000.00 |
| Machinery |
27,750.00 |
| Material |
11,227.60 |
| Supplies |
648.50 |
| Goods in Process |
3,984.70 |
| Manufactured Goods |
5,290.00 |
A cost system was desired by the management, consequently in
opening new books it was necessary to provide for the needed accounts.
The complete entries used to change these books from single
to double entry are shown in the model journal illustrated, page 29.
120
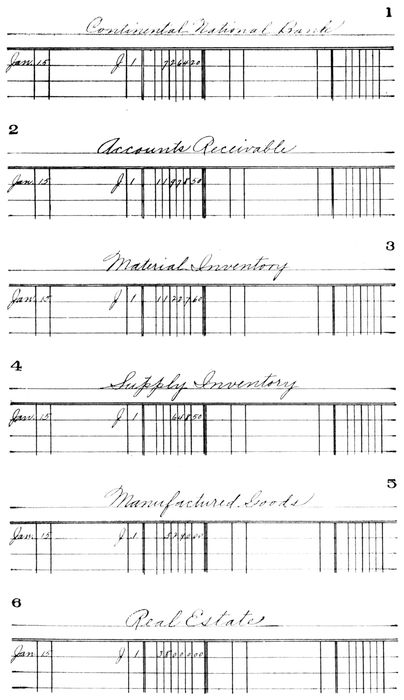
Ledger After Changing to Double Entry
121
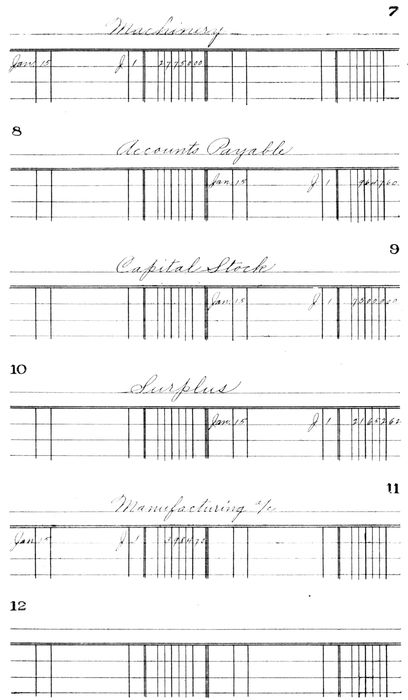
Ledger After Changing to Double Entry
122
The books of the Star Coal Company, a corporation with a
paid-up capital of $10,000.00, have been kept by single entry. The
following facts are gathered from the books:
| Cash in Bank |
|
$3,500.00 |
| Personal Accounts |
Debit Balances |
6,500.00 |
| Cash in Office |
|
200.00 |
| Personal Accounts |
Credit Balances |
2,500.00 |
An inventory results as follows:
| Coal |
3,750.00 |
| Horses and Wagons |
800.00 |
| Furniture and Fixtures |
300.00 |
Make necessary journal entries to change to double entry.
Provide a reserve of 5% for uncollectible accounts, 10% for depreciation
of horses and wagons, 10% for depreciation of furniture and
fixtures. Declare a dividend of 10% and transfer balance of profits
to surplus, making all journal entries to record these transactions.
TWO HEMISPHERICAL BOTTOMS FOR 100,000-GALLON ELEVATED TANKS RIVETED TOGETHER, SHOWING CLASS OF WORKMANSHIP NECESSARY ON WORK OF THIS CHARACTER
Chicago Bridge & Iron Works, Chicago, Ill.
123
14. The construction of comparative statements is one of the
most important duties of the bookkeeper. The ability to properly
classify the accounts that make up trading and profit and loss statements,
and balance sheets is a valuable asset to the bookkeeper who
aims to advance to the highest position.
Statements of this kind, unless properly classified, are unintelligible
to the average business man. A mere statement of the balances
of the ledger accounts arranged without respect to their relationship,
one to the other, may show that the ledger is in balance, but does not
present information of special value to the manager of a business.
What he wants—and expects—is a statement from which he can
readily extract desired information; it must emphasize the salient
points.
The classification of accounts has already been touched upon,
but no harm will be done by placing still greater emphasis on the
importance of this feature. For with the right classification of
accounts in the ledger, the trial balance itself will supply some very
interesting information, instead of being a mere list of balances. The
following rules should be observed in the arrangement of accounts
in the ledger.
All asset accounts should be assembled in the first section and
grouped according to their classification; i. e., active, fixed, and passive
or fictitious.
The liabilities should be divided into secured or funded, unsecured
or floating, and capital; the latter includes any reserve accounts
that may be maintained.
The expense accounts should follow and should be subdivided
as to selling, general, and administrative.
The trading accounts should be grouped and divided into purchases,
in-freight, and sales.
If a manufacturing business, the manufacturing accounts should
be divided as to purchases, labor, and expenses.
The advantages of card and loose leaf ledgers are apparent in
connection with the proper arrangement of accounts. They readily
lend themselves to any desired classification, and new accounts as
needed can be inserted at any point.
124For the purpose of showing some of the possibilities in the classification
of accounts, we give a few examples of model trial balances.
| TRIAL BALANCE |
|---|
| |
| Assets |
| Cash |
$264.20 |
|
| Bank |
4,728.50 |
|
| Accounts Receivable |
6,270.00 |
|
| Inventory (Jan. 1) |
7,860.00 |
|
| Real Estate |
10,000.00 |
|
| Furniture and Fixtures |
5,000.00 |
|
| |
| Liabilities |
| Mortgage Payable |
|
$3,000.00 |
| Bills Payable |
|
5,000.00 |
| Accounts Payable |
|
6,120.00 |
| Capital Stock |
|
20,000.00 |
| |
| Profit and Loss |
| Advertising |
475.00 |
|
| Salesmen's Salaries |
300.00 |
|
| Traveling Expenses |
189.70 |
|
| General Expense |
74.00 |
|
| Interest and Discount |
22.60 |
|
| Building Maintenance |
37.00 |
|
| Taxes and Insurance |
42.00 |
|
| Salaries |
525.00 |
|
| |
| Trading |
| |
| Purchases |
5,500.00 |
|
| In-Freight and Cartage |
96.20 |
|
| Sales |
|
7,219.00 |
| |
|
|
| |
41,361.60 |
41,361.60 |
If the accounts in this trial balance were listed without regard to
the groups in which they belong, it would merely show that the ledger
balances. In its present form, it gives at a glance much valuable information.
Total expenses and expenses of each class are readily
ascertained, sales are shown, and expenses can be compared with
sales. With the exception that it does not show the changes in the
125account of the inventory, this trial balance exhibits the condition of
the business.
Supposing that an inventory is taken, the following statements
are quickly prepared.
| BALANCE SHEET |
|---|
| Assets |
| Cash |
$264.20 |
|
| Bank |
4,728.50 |
|
| Accounts Receivable |
6,270.00 |
|
| Inventory (Feb. 1) |
7,995.00 |
|
| Real Estate |
10,000.00 |
|
| Furniture and Fixtures |
5,000.00 |
|
| |
| Liabilities |
| Mortgage Payable |
|
$3,000.00 |
| Bills Payable |
|
5,000.00 |
| Accounts Payable |
|
6,120.00 |
| Capital Stock |
|
20,000.00 |
| Surplus |
|
137.70 |
| |
|
|
| |
34,257.70 |
34,257.70 |
| |
| TRADING STATEMENT |
|---|
| Inventory (Jan. 1) |
7,860.00 |
|
| Purchases |
5,500.00 |
|
| In-Freight |
96.20 |
|
| |
|
|
| |
13,456.20 |
|
| Less Inventory (Feb. 1) |
7,995.00 |
|
| |
|
|
| |
5,461.20 |
|
| Sales |
|
7,219.00 |
| Gross Profit |
1,757.80 |
|
| |
|
|
| |
7,219.00 |
7,219.00 |
| |
|
|
| |
| PROFIT AND LOSS STATEMENT |
|---|
| Gross Profit |
|
$1,757.80 |
| Advertising |
$475.00 |
|
| Salesmen's Salaries |
300.00 |
|
| Traveling Expenses |
189.70 |
|
| General Expense |
74.00 |
|
| Interest and Discount |
|
22.60 |
| Building Maintenance |
37.00 |
|
| Taxes and Insurance |
42.00 |
|
| Salaries |
525.00 |
|
| Net Profits |
137.70 |
|
| |
|
|
| |
1,780.40 |
1,780.40 |
| |
|
|
126The facts that sales were $7,219.00, or that the expense for salesmen's
salaries was $300.00 mean nothing in themselves. It is only
when compared that they exhibit vital facts. If we find that last
month's sales were $8,400.00 and salesmen's salaries the same as this
month, we know at once that our present selling cost is proportionately
higher than during the preceding period.
The following trial balance should be compared with the preceding
and the difference in their values, in respect to the information
given, carefully noted. The accounts in this trial balance are arranged
in the order in which they were found in the ledger.
| TRIAL BALANCE |
|---|
|
Dr. |
Cr. |
| Capital Stock |
|
$30,000.00 |
| Sales |
|
45,411.40 |
| Accounts Receivable |
$7,190.00 |
|
| Accounts Payable |
|
2,720.00 |
| General Expense |
727.00 |
|
| Salesmen's Salaries |
3,000.00 |
|
| Salaries, General |
3,600.00 |
|
| Interest and Discount |
|
126.70 |
| Returns and Allowances |
942.20 |
|
| Inventory |
9,687.00 |
|
| Purchases |
26,250.00 |
|
| In-Freight |
$396.40 |
|
| Bank |
6,470.00 |
|
| Traveling Expense |
1,759.00 |
|
| Taxes and Insurance |
236.50 |
|
| Real Estate |
25,000.00 |
|
| Fixtures |
3,000.00 |
|
| Surplus |
|
10,000.00 |
| |
|
|
| |
88,258.10 |
88,258.10 |
| |
|
|
127
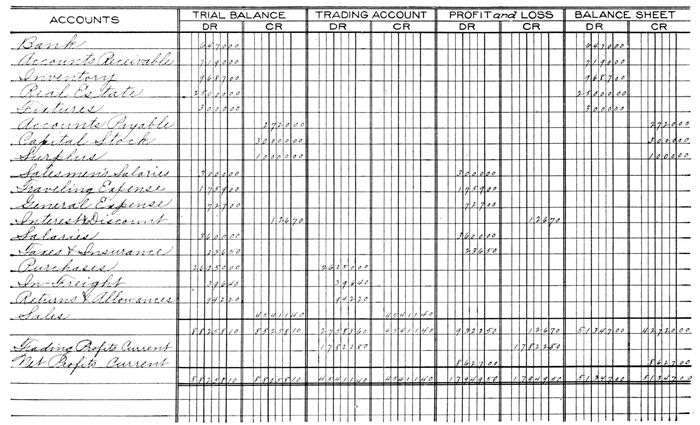
Fig. 15-a. Working Balance Sheet
128
15. A form much used by accountants combines the trial balance
with the balance sheet, trading and profit and loss statements.
The compilation of the information required for this form is greatly
facilitated by a proper classification of accounts in the ledger. The
form is known as a working balance sheet.
A working balance sheet is shown in Fig. 15 a. The figures
used are taken from the last trial balance shown, and furnish a
graphic illustration of the difference between proper and improper
classification of accounts. It will be noticed that the first two columns
constitute the trial balance. Following this are columns which
classify the accounts under the headings of Trading, Profit and Loss,
and Balance Sheet. The balance of each account is extended to its
proper group.
At the bottom of the form, trading and net profits are extended
as a memorandum only. Since no inventory has been taken these
figures are not exact, but represent approximate results on the supposition
that the inventory would be practically the same as when
the last inventory was taken. Of course, if there was a noticeable
change in the quantity of merchandise in stock, an estimate would be
made and taken into consideration in making this statement of probable
profits.
From the following trial balance, prepare a working balance
sheet showing actual gross and net profits.
| 129 |
| TRIAL BALANCE |
|---|
| Bank |
$8,460.00 |
|
| Capital Stock |
|
$25,000.00 |
| Sales |
|
11,201.00 |
| Purchases |
10,000.00 |
|
| Returns and Allowances |
400.00 |
|
| Interest and Discount earned |
|
260.00 |
| General Expense |
425.00 |
|
| Salaries |
360.00 |
|
| Rent |
300.00 |
|
| Taxes and Insurance |
37.60 |
|
| Selling Expense |
421.00 |
|
| Inventory (Jan. 1st) |
8,864.00 |
|
| Fixtures |
2,500.00 |
|
| Accounts Receivable |
5,680.00 |
|
| Accounts Payable |
|
1,274.00 |
| Cash in Office |
287.40 |
|
| |
|
|
| |
37,735.00 |
37,735.00 |
| Inventory (Feb 1) |
|
9,650.00 |
16. The trial balances shown in the preceding pages illustrate
some of the advantages of properly classified accounts. The information
gained can be made of still greater value by the construction
of comparative statements; for, as has been stated, the chief value
of many of the figures shown lies in the opportunity for comparisons.
Statements which permit of comparison of items of a like nature
from month to month furnish a valuable survey of the progress of
the business.
The following is a trial balance taken from the books of a manufacturing
business, and will be used as a basis for the construction
of comparative statements.
| TRIAL BALANCE |
|---|
| |
| |
Dr. |
Cr. |
| Cash in Office |
$162.50 |
|
| Bank |
8,500.00 |
|
| 130Accounts Receivable |
7,500.00 |
|
| Bills Receivable |
4,500.00 |
|
| Inventory, Materials (Jan. 1) |
9,500.00 |
|
| Inventory, Manufactured Goods |
|
|
| (Jan. 1) |
6,000.00 |
|
| Real Estate |
20,000.00 |
|
| Machinery and Tools |
17,500.00 |
|
| Furniture and Fixtures |
3,500.00 |
|
| Bills Payable |
|
$7,000.00 |
| Accounts Payable |
|
5,000.00 |
| Capital Stock |
|
50,000.00 |
| Surplus |
|
10,000.00 |
| Undivided Profits |
|
900.00 |
| Advertising |
1,200.00 |
|
| Salesmen's Salaries |
1,000.00 |
|
| Salesmen's Expenses |
720.00 |
|
| General Expense |
430.00 |
|
| Interest and Discount |
|
97.50 |
| Salaries Administrative |
900.00 |
|
| Factory Expense |
850.00 |
|
| Factory Labor |
1,750.00 |
|
| Repairs to Machinery |
150.00 |
|
| Depreciation |
175.00 |
|
| Taxes and Insurance |
25.00 |
|
| Material Purchases |
4,600.00 |
|
| In-Freight and Cartage |
126.00 |
|
| Sales |
|
16,491.00 |
| Returns and Allowances |
400.00 |
|
| |
|
|
| |
89,488.50 |
89,488.50 |
| |
|
|
In Fig. 16 a. is shown a working balance sheet in which the accounts
as found in the trial balance are segregated in the four groups,
Manufacturing, Trading, Profit and Loss, and Balance Sheet. First,
the trial balance is entered in the two columns at the left. Next,
the manufacturing account is made up by extending the inventory
of material at end of preceding period, the manufacturing expense
accounts, material purchases and freight on same. This gives the
131total charges to manufacturing account, but not the month's expenditures,
for the present inventory of material must be considered.
An inventory shows the value of material in stock to be $4,550.00.
Deducting this leaves $12,626.00, the total operating cost for the
month. To find the cost of goods completed during the month an
inventory is taken of work in process, the amount is deducted from
the total operating cost and the result, $9,126.00, represents cost of
goods manufactured.
The trading account is now made up, this $9,126.00 taking the
place of purchases, and the gross profit is carried to profit and loss
account.
The manufacturing, trading, and profit and loss accounts are
now ready for analysis, which is made on a percentage basis. In
the analysis of the manufacturing account, the total operating cost
is used as a basis and the different items of manufacturing cost are
figured on this basis. We find that the expense items are 23.3%
and the material 76.7% of the total which furnishes a tangible basis
for a comparison of the same items in other months. Having the
percentage of each item, we can note the fluctuations from month to
month, and know where to retrench if any item appears to be increasing
too rapidly.
The basis of the analysis of the trading and profit and loss
accounts is the turnover. Figuring on this basis, we find the total
expenses, exclusive of manufacturing costs, to be 41% of the turnover,
and the net profit, 20%. The gross profit is 60% of the turnover.
Ordinarily the total expense and net profit would equal the gross
profit, but in this case there is a capital profit of $97.50 from interest
earned.
Sometimes these comparative percentages are figured on the
gross sales, but the turnover is considered the proper basis, for it is
less subject to marked fluctuations. The sales in one month may
show abnormal profits, while in the next these profits may return to
normal. If based on sales, the cost percentages would fluctuate
accordingly, when in reality they may have remained stationary.
17. A comparison of the accounts in the last trial balance with
the working balance sheet shows them to be arranged in the order
in which they would appear in the balance sheet and profit and loss
statements.
132
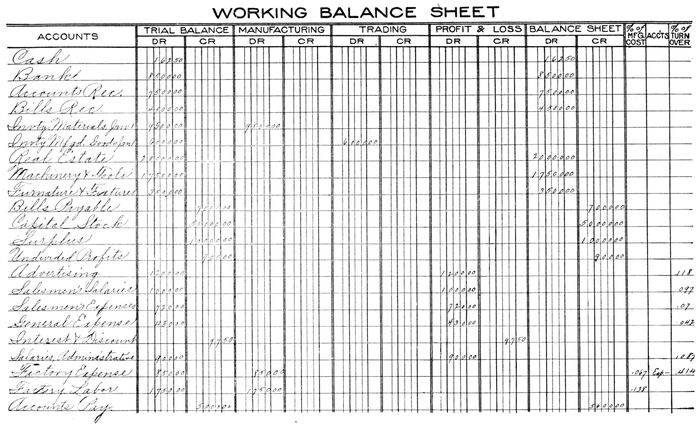
133
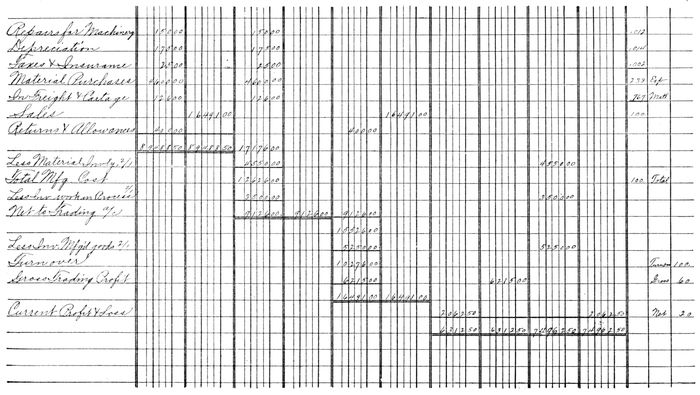
Fig. 16a. Working Balance Sheet for a Manufacturing Business
134It should be remembered that manufacturing and trading accounts
are subdivisions of the profit and loss account, and that the
profit and loss account is a statement of income and disbursements
including differences in inventories.
If it is desired to show the actual condition of the business at the
end of each month, the inventory must be added. There may be
objections to actually closing the books each month, but the complete
statement can be made by adding the current inventories as
shown in the working balance sheet illustrated. The amounts of
these inventories and the gross and net current profits are, in such
cases, memoranda only. The inventories may be arbitrary estimates,
and while the results shown may not be exact they will be found of
value for purposes of comparison; and care in estimating inventories
will greatly increase their value.
Reference to our working balance sheet shows that the profit
and loss statements—with current inventories added—agrees with
the balance sheet in one respect. The current profit exactly agrees
with the difference between assets and liabilities as shown by the
balance sheet.
To prove the ledger without the usual trial balance these rules
should be followed:
First: Make up trading and profit and loss statements, taking balances
direct from the ledger accounts, deducting current inventories.
Second: Make up balance sheet using current inventories in
listing assets.
If the current profit and loss agrees with the difference between
assets and liabilities the ledger may be assumed to be in balance.
This is, in effect, a sectional trial balance, since the accounts in the
trial balance are all represented in the two statements. The reliability
of this proof is not affected by the fact that the inventories
are arbitrary—and perhaps inaccurate—since the same amounts
are used in both the balance sheet and profit and loss statement.
18. To make the foregoing plan still more effective, perpetual
inventories should be carried in the ledger. A perpetual or book
135inventory is an account showing the value of merchandise received,
sold, and on hand. If an accurate account is kept of merchandise
received and sold, the perpetual inventory will show the amount
that should be in stock. To prove the accuracy of the account, it is
necessary to take an actual inventory of the merchandise in stock,
just as it is necessary to count the cash before we can know that the
amount on hand agrees with the cash account.
A detailed perpetual inventory should be kept on cards or in a
loose leaf book. A card or sheet is used for each article or class of
material carried in stock. The sheets or cards should be arranged
alphabetically according to the names of the articles. To make the
system effective one person should have charge of these records and
no goods should be taken from stock without an order or other proper
record.
At the end of the month the receipts will be shown by the purchase
accounts. The deliveries will be tabulated from the cards,
and the necessary adjustments made on the ledger account. Adjustments
should be made by journal entry debiting inventory accounts
and crediting trading account for increase in inventory, and vice
versâ for decrease in inventory.
Fig. 18 a. is a typical form of stock ledger sheet for a loose leaf
book. The form should in all cases be made to suit the requirements
of the business in which it is to be used.
Fig. 18 b. is a card form of stock ledger which gives more detailed
information about the article in stock. On the top line is recorded
the name of the article, size or kind, where kept, and date of verification
of the record. The second line gives the unit and maximum
and minimum limits. The unit represents the unit in which the
article is bought—as pounds, tons, dozen, feet, yards, etc. It is
customary to establish a minimum limit, below which the stock is
not allowed to go before re-ordering, and a maximum limit of a quantity
sufficient for the needs of the business. The record of receipts
and disbursements includes a detailed record of cost, including freight
and cartage, and columns for costs per unit. This makes it possible
to calculate the value of the stock in hand without referring elsewhere
for prices.
In some lines of business it is possible to ascertain the quantities
sold, at the end of each month, from the sales records. This
136applies where an article is sold in but one grade or size, and necessitates
keeping sales records which show sales of each article. An
example is the coal business. For such a business a card like the
one shown in Fig. 18 c. can be used to good advantage. This provides
for a monthly record of purchases and sales.
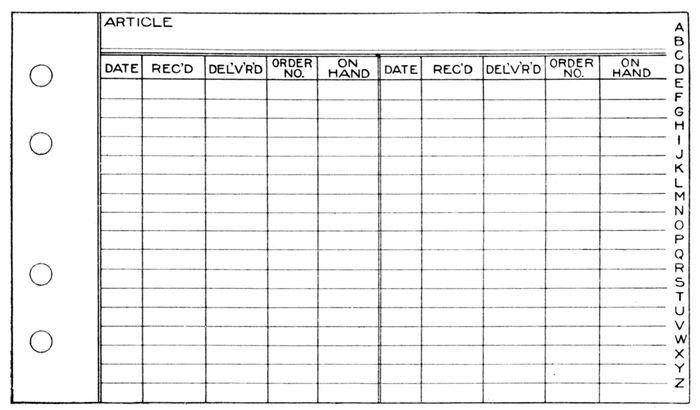
Fig. 18 a. Loose Leaf Stock Ledger
In this illustration the manner of indexing is shown. The cards
are first arranged alphabetically under the names of the articles.
If there is more than one size, the cards bearing the records of a
certain article are filed in the order of their sizes. Indexed in this
manner any card that may be desired is quickly found.
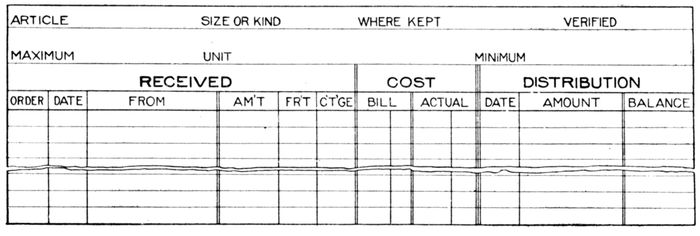
Fig. 18 b. Stock Ledger Card
137
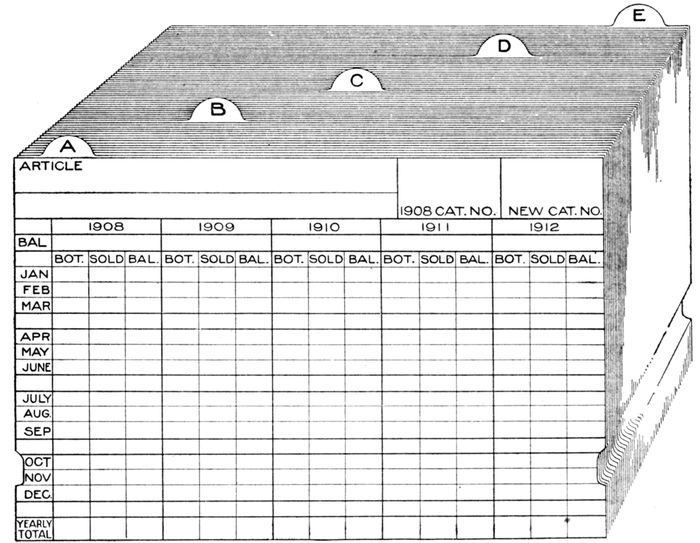
Fig. 18 c. Stock Ledger Card and Indexes
19. Taking the accounts in the following trial balance, a model
ledger is illustrated which demonstrates the manner of proving the
ledger without the aid of the conventional trial balance. It is assumed,
of course, that a book inventory or stock ledger is kept, and
in this demonstration the figures showing the change in inventory
are used. Only the ledger is illustrated, it being expected that the
student will understand the necessary journal adjusting entries.
| TRIAL BALANCE |
|---|
| |
| Cash in Office |
$575.00 |
|
| Bank |
8,750.00 |
|
| Accounts Receivable |
8,871.00 |
|
| Bills Receivable |
5,000.00 |
|
| Inventory (Jan. 1) |
12,500.00 |
|
| Furniture and Fixtures |
2,250.00 |
|
| Bills Payable |
|
$4,000.00 |
| Accounts Payable |
|
3,325.00 |
| 138Capital Stock |
|
$25,000.00 |
| Purchases |
$6,750.00 |
|
| Sales |
|
15,000.00 |
| Advertising |
960.00 |
|
| Salesmen's Salaries |
450.00 |
|
| Traveling Expense |
190.00 |
|
| Office Expense |
46.50 |
|
| Office Salaries |
225.00 |
|
| General Expense |
34.20 |
|
| Rent |
175.00 |
|
| Taxes and Insurance |
21.30 |
|
| Discounts Allowed |
47.90 |
|
| Interest Paid |
33.10 |
|
| Interest and Discount Earned |
|
54.00 |
| Administrative Salaries |
500.00 |
|
On Feb. 1st the inventory shows a decrease of $3,500.00. A
reserve of 3% on accounts receivable is to be created to provide
for uncollectible accounts. To make these adjustments the following
journal entries will be required:
| Trading a/c |
3,500.00 |
|
| To Inventory |
|
3,500.00 |
| Decrease in Inventory |
|
|
A study of this entry will show that the result is the same if we
make up the trading account by using purchases and adding or
subtracting the decrease or increase in inventory, or if the preceding
inventory is added and present inventory is deducted. The result
in either case is the turnover and the above entry makes the necessary
adjustment in the inventory account without closing the account
through the trading account.
The entry for the reserve for uncollectible accounts is
| Profit and Loss |
266.13 |
|
| To Reserves |
|
266.13 |
| Reserve of 3% to provide |
|
|
| for uncollectible accounts. |
|
|
At the end of the next month this account will be adjusted by
charging or crediting the amount necessary to maintain the total at
the desired percentage of accounts receivable.
UNDERWOOD TYPEWRITERS USED IN MELBOURNE UNIVERSITY COMMERCIAL EXAMINATIONS
139
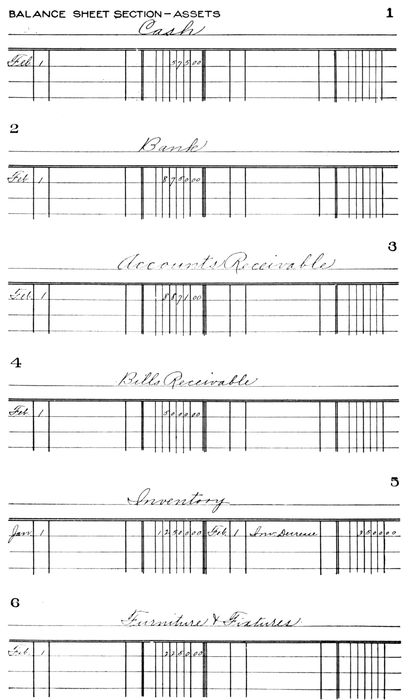
Ledger with Accounts Classified
140
Ledger with Accounts Classified
141
Ledger with Accounts Classified
142
Ledger with Accounts Classified
143
Ledger with Accounts Classified
20. To feel absolutely sure that his work is correct is the ambition
of every bookkeeper. The fear that an error will throw his
books out of balance is always present, and is only dispelled when
the ledger is proved at the end of the month.
Accountants, bookkeepers, and mathematicians have long
searched for an infallible rule or method of checking which would
detect an error as soon as it is made. No system could possibly
prevent the making of an error, but if detected, an error is quickly
corrected. Numerous formulas and checking systems, designed to
detect errors in posting, have been put on the market from time to time.
Each has been advertised as the only infallible system. All have
been eagerly purchased, tried more or less faithfully, and, as a rule,
speedily discarded.
Modern methods of bookkeeping have done more to aid in the
detection of errors in posting than all of the checking systems combined.
The sectionalization of accounts not only facilitates the detection
of errors, but greatly minimizes the chances of their being made.
As an illustration take a sales ledger which is subdivided into two or
more parts, with special columns in cash book and sales book, and
controlling accounts for each section. If the individual balances
taken from the sales ledger do not agree with the controlling accounts,
it is seen at a glance in which section the error has been
made. Instead of a search through all postings to sales ledger accounts,
it is only necessary to check postings to that particular section.
144
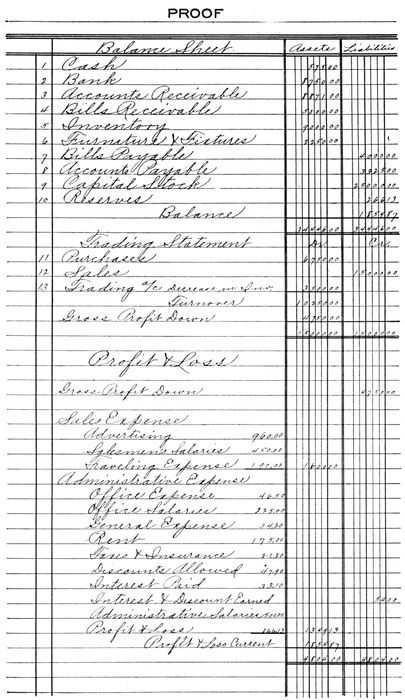
Ledger Proof Without a Trial Balance
145Errors in posting to nominal accounts are minimized by special
columns in cash book, sales book, and purchase record, with one
posting at the end of the month, in place of a posting for each item
entered.
But still, errors are and always will be made in posting, and for
the bookkeeper who has a large number of accounts to post and
wishes to keep a constant check on his work, the reverse posting
or slip posting system will give satisfactory results with little labor.
Fig. 19. Monthly Posting Proof Sheet
This system is very simple, and easily operated. It consists
of the use of a slip of paper with debit and credit columns in which
accounts posted to the ledger are entered. A separate slip is used
for each book from which postings are made, and the items are posted
to the slip from the ledger. The slip should be placed on the desk
on the opposite side of the ledger from the book of entry.
If posting is from the sales book, the ledger should be placed
to the right of the sales book and the slip to the right of the ledger.
After the item is entered in the ledger it is posted to the slip. When
the work is completed the slip is footed and compared with the footing
of the sales book. If the footings agree, it is quite evident that the
correct amounts have been posted to the ledger, for it is scarcely
possible that an incorrect amount has been posted to the ledger and
the correct amount entered on the slip.
A further daily proof may be had by inserting a blank slip of
paper in the ledger wherever an item is posted. At the end of the
day these ledger accounts are referred to, the amounts are drawn
off, and total postings compared with the totals of the checking slips
from the different books.
146When postings are not checked daily a form should be prepared
to which daily totals will be carried. Columns are provided
for each book from which posted, and these are footed at the end of
the month and compared with the footings of the books. If the
ledger does not balance a comparison of this proof slip with the
column footings of the books will show in which book the error has
been made. The form of the monthly proof slip is illustrated in
Fig. 19.
21. Bookkeeping, if it is to fulfil its mission, must furnish a
complete record of the transactions of a business. The record must
show, as well, the results of each transaction or class of transactions,
with respect to their bearing on the business as a whole, or on specific
sections or departments of that business. From a mere record of
personal debits and credits, bookkeeping has grown into a detailed
history of a business.
The principles of bookkeeping are the same regardless of the
nature, size, or condition of a business. But different businesses
require different kinds of information; vital facts in one business
may be valueless in another. The success or failure of each depends
upon certain elements which must be recorded in its history. It is
the work of the bookkeeper to record these facts—to write the history
of the business in language that will be understood by anyone who
may read it.
Laying out the business history is the work of the accountant.
He makes an analysis of those elements which bear on the success
of the business, and determines what facts, when properly recorded,
will furnish the clearest and most understandable history. And
when he has determined what facts should be recorded he must plan
how they are to be recorded—in what form they will present the
most concise history of business transactions. His work should
result in a system of bookkeeping that will present the most vitally
important information, with a minimum expenditure of labor.
The increasing demand for more intelligible records—for facts—has
stimulated the ingenuity of accountants in devising forms that
will not only accommodate the records desired but will permit of their
being made with the least labor. Special forms exactly suited to
147the records which they are to contain, are now made for every purpose.
Labor-saving devices and methods have minimized the drudgery
of bookkeeping.
The bookkeeper who would rise above mediocrity requires something
besides the ability to record business transactions in the proper
columns of books prepared for him. He must know how to devise
forms and books, how to adapt correct principles to the building of
a system of bookkeeping for any line of business. If certain facts
assume importance, he must know how those facts can best be obtained
and recorded.
To assist in familiarizing the student with the more modern
methods, this section is devoted to illustrations and descriptions of
special forms of books for various purposes. The student should
devote careful study to these forms, for while they have been in the
main devised to meet special conditions, the principles can be adapted
to any line of business where similar conditions exist.
22. Loose Leaf Ledgers. A loose leaf ledger is one in which
the leaves are removable. Instead of the sheets being bound in
solid book form, each leaf is a separate sheet ruled for one ledger
account. The sheets are filed or bound in what is known as the
binder, being securely held in place by a mechanical device. The
binder can be locked so that only the person holding the key can insert
or remove the sheets.
The loose leaf ledger is indexed either numerically or alphabetically.
When the numerical method is used the sheets are numbered
and placed in the binder in numerical order which gives the same
arrangement as a bound book. A separate index is required with
the numerical method. The alphabetical method of indexing necessitates
the use of sheets on the edges of which are tabs or projections
printed with the letters of the alphabet. These index sheets are
placed in the binder in alphabetical order and the ledger sheets
are placed between them. The alphabetical method is preferred
by many as it makes the ledger self-indexing. Another method of
indexing is a combination of the alphabetical and numerical. The
alphabetical index sheet is used, and under it are filed all accounts of
persons whose names begin with that letter. These sheets are numbered
148Account No. 1, No. 2, etc., and the names are written on the
index sheet, followed by the account number. This practically
divides the ledger into separate numerical ledgers for each letter of
the alphabet.
Fig. 20. Loose Leaf Ledger
Binders for loose leaf ledgers are made to hold from a few sheets
up to one thousand or more. By proper arrangement of the indexes,
more than one ledger can be accommodated in one binder. As an
illustration, the general, purchase, and sales ledgers, each with its
separate index, may all be in the same binder.
One of the chief advantages of the loose leaf ledger is that all
"dead" matter can be removed. When a sheet becomes filled, it
can be removed to another binder called a transfer binder, and a
new sheet put in its place. Or if the account be permanently closed,
it is transferred, leaving only live accounts in the ledger. When new
accounts are to be opened, it is only necessary to insert additional
sheets. There is no transferring of all accounts from one ledger to
another as with bound books, for the loose leaf ledger is never filled.
If the number of sheets increases beyond the capacity of the binder,
the ledger can be divided by transferring a part of the sheets to a
new binder.
The ruling of loose leaf ledger sheets is the same as in bound
books, the forms usually being made to fit the business. A sheet
with a conventional form of ruling is illustrated.
23. Card Ledgers. For certain classes of accounts, the card
ledger is very desirable. It is well adapted for a sales ledger in a
business having a large number of customers, and especially so if the
149nature of the business is such that the purchases of a customer are
infrequent. In many businesses handling a single line of goods
known as seasonable, sales are made in the spring and fall so that a
customer purchases practically an entire year's supply in two orders.
Fig. 21 a. Ledger Card for Dentists
The card ledger is largely used in banks for keeping accounts
with depositors in the savings department. A card 5 inches x 8 inches
in size gives room for forty items on each side, and for the average
savings account will last more than two years.
Some advantages claimed for the card ledger are:
First: Dead records are eliminated, as filled cards and closed
accounts are transferred to a separate file, leaving only open accounts
in the current file.
Second: It can be expanded to any size, which makes it ideal
for business with a large number of customers. The opening of a
new account, or re-opening of a closed account, is accomplished by
merely dropping a card in the right place.
Third: The labor of making trial balances is greatly reduced,
as there are no closed accounts to refer to in the current file.
Fourth: Statements can be mailed much earlier as the cards
can be distributed among several clerks who can be working on them
at the same time.
Fifth: The ledger can be subdivided as desired by the use of
proper index cards. When one drawer or tray is filled, a part of the
150cards can be taken out and placed in another tray without disturbing
their arrangement.
There are two general plans of indexing the card ledger—alphabetical
and numerical. The alphabetical method consists of a set
of guide or index cards between which the cards are filed. This
index may consist of one index for each letter of the alphabet, a
smaller number with two or more letters on one index, or a much
larger number subdividing the alphabet into as many parts as may
be necessary. In planning an index for a card ledger, a safe rule to
follow is to provide one index card for every ten ledger cards.
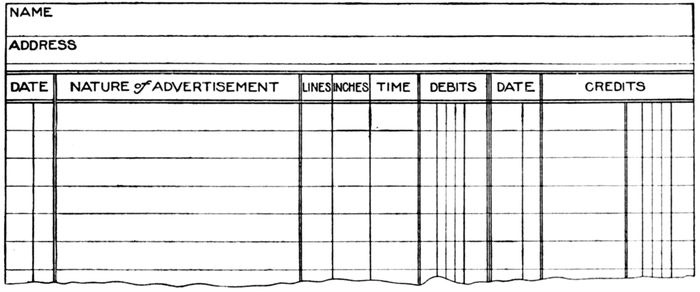
Fig. 21 b. Ledger Card for Publishers
A subdivision of the alphabetical index is the geographical or
territorial. This divides the ledger by states and towns. Guide
cards, printed with the names of the states, provide the main division;
other guides, printed with names of towns, subdivide the state sections;
and where necessary, alphabetical guides subdivide the names in the
towns. If desired, the ledger may be divided into territorial sections,
as East and West; or each section may include the territory covered
by one salesman.
A numerical index divides the cards by tens and hundreds.
Guide cards numbered by hundreds—100, 200, etc.—provide the
main divisions. Between these are placed guides numbered 10, 20,
30, etc. to subdivide these sections by tens, and the ledger cards
are filed in numerical order between these guides. To facilitate
locating any number desired, the cards themselves are made with
small projections numbered from 0 to 9 to represent the units. Each
card bears one tab, and all tabs bearing the same unit are in the same
151relative position on the card; that is—0 is always at the extreme left,
while 9 is ten positions to the right. When the cards are placed in
numerical sequence, between the guides numbered by 10's, any
number can be found instantly. To find number 2,987, we refer first
to the main guide number 29, then to the guide numbered 8—in the
section between 29 and 30—and then to the number 7 tab next following.
As there are never more than one thousand cards in a tray,
any number can be found more quickly than in a bound book. If a
card is misplaced in filing, the unit tab will greatly assist in locating
the missing card. Suppose card No. 964 is missing; a search through
the row of No. 4 tabs will locate it, no matter where filed. With this
system of filing, a separate index by name is required, and this also
is made on cards. For a very large ledger the numerical system is
more frequently adopted than the alphabetical.
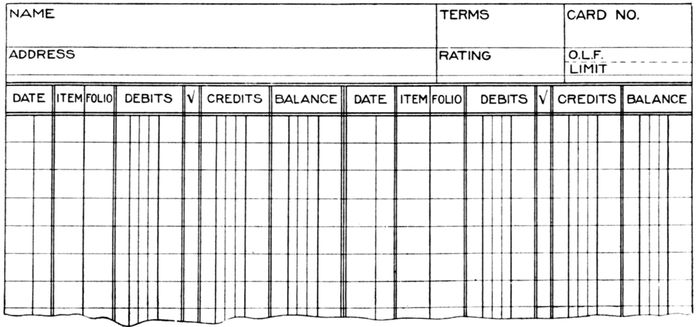
Fig. 21 c. Balance Form of Ledger Card
It is claimed that the numerical tab scheme affords one safeguard
not found in an alphabetical system. A missing card is at once
detected by the break in the row of tabs, but to make the safeguard
of value it is necessary to leave the cards in the file even after accounts
are closed.
There is no good reason why an alphabetical card ledger should
not be as safe as the numerical. If it is desired to guard against the
removal of one card and the substitution of another, the blank cards
should be placed in the custody of one man, who will issue them to
the bookkeeper as needed, first placing his initials on the card. In
any event, the card ledger should be provided with a locking device
152which will prevent the removal of a card, except by the one who has
the key.
These suggestions may be of assistance to the bookkeeper who
is called upon to use a card ledger.
Never leave ledger cards lying on the desk. When you leave
your work, put them back in the file, where they belong.
Before leaving the office, lock the ledger so that no one can
remove a card in your absence.
If your superior asks you to see a certain ledger account, do
not give him that one card. He may lose it. Give him the entire
tray, with the cards securely locked. Should he insist on having that
one card, ask him to give you a receipt for it.
Some special forms of ledger cards are illustrated. Fig. 21 a.
is a form used by a dental supply house. The special feature of the
form is a separate column for each different class of goods purchased
by the customer. Fig. 21 b. is used by a publisher for advertising accounts.
Fig. 21 c. is a conventional balance ledger form adapted for
use in almost any line of business.
24. Tabular Ledger. This is a ledger in which the names are
written down the side of the page, with debits, credits, and balances
extending across the page. Columns are arranged to group entries
during uniform periods, as a month, week, or day. A special feature
of this style of ledger is that it can be more quickly balanced and
proved than any other style. To prove this ledger add the balances
at the end of the preceding period to the debit postings of the current
period. This will equal the total of the credit postings added to
the new balances, if the balances have been correctly extended. The
postings to all of the accounts on a page—30 to 40—can be footed
at one operation, saving much time.
Fig. 22 a. is a form of a tabular ledger used by banks, known as
the Boston bank ledger. It is specially arranged to exhibit daily
balances, as it is necessary that the depositor's ledger be balanced
daily. This form can be used in a mercantile business, but as balances
are not required daily, the form shown in Fig. 22 b. is better
adapted to the purpose. These tabular forms of ledgers are not
commonly used except in banks.
25. Balance Ledgers. Three forms of balance ledgers are
illustrated, each one of which is specially adapted to some particular
class of business.
153
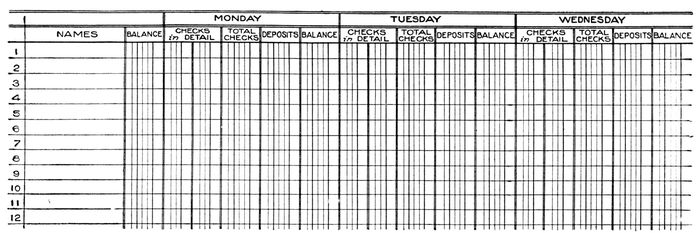
Fig. 22 a. Boston Bank Ledger
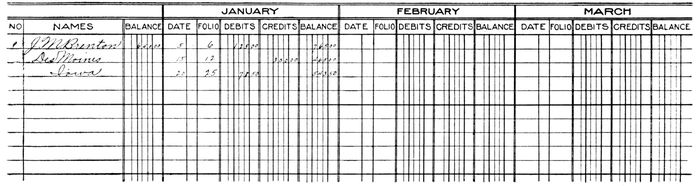
Fig. 22 b. Commercial Tabular Ledger
154The special feature of Fig. 23 a. is two credit columns—one for
cash and one for merchandise returns. This form is favored in
certain lines of business where merchandise returns are frequent. A
special column serves to separate returns of merchandise sent out
on approval, which in some businesses is an important item.
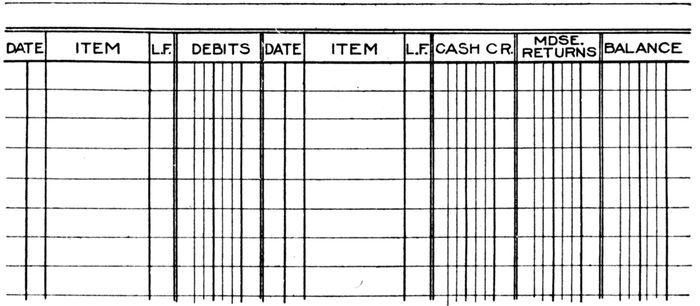
Fig. 23 a. Ledger with Special Credit Columns
Fig. 23 b. is provided with two balance columns, for debit and
credit balances. This form saves time in taking trial balances, as it
is seen at a glance whether the balance is a debit or a credit.
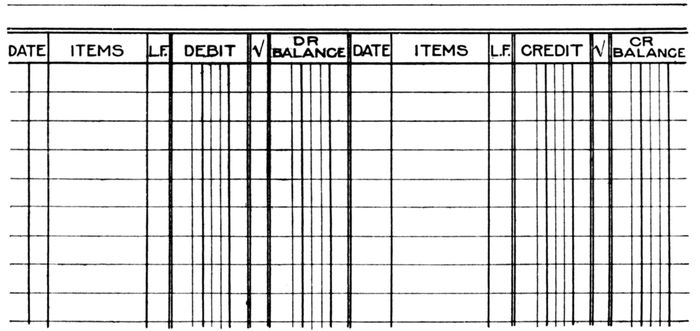
Fig. 23 b. Balance Ledger
The feature of Fig. 23 c. is several credit columns to one debit
column. This form is largely used where sales are made subject to
periodical payments. It is well adapted for installment accounts, rent
accounts, insurance accounts, and similar classes. The number of
credit columns can be extended indefinitely to meet existing conditions.
THE PRUDENTIAL BUILDING
One of Buffalo's Best Office Buildings
155
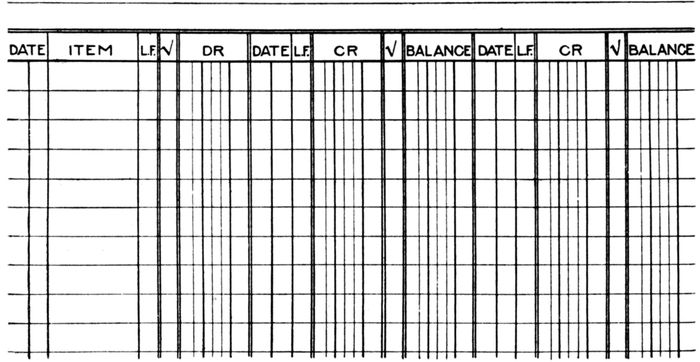
Fig. 23 c. Balance Ledger for Installment Accounts
26. Since the almost universal adoption of special forms of
sales books, purchase books, and check registers, the journal proper
is only used for adjusting entries. The cash journal, which is a combination
of cash book and journal, has taken the place of the two
books. Some forms of this book have been illustrated earlier in this
text, and a typical form is shown in Fig. 24 a. A study of this form
will be found instructive as it suggests the many possibilities of
segregating distinct classes of receipts and expenditures. Note the
segregation of charges to manufacturing, selling, and administrative
branches of the business. Under each branch the different kinds of
expense might be shown with all their subdivisions by providing additional
columns.
In fact, as we have already stated, there is no end to the possibilities
of segregating different classes of transactions by means of
the columnar principle in designing books of entry. But it may
not be out of place to sound a note of warning against increasing the
size of the pages of a book beyond a reasonable limit. While the
saving of time is the important factor that influences the introduction
of columnar books, there has grown up a tendency to go to such
extremes that the unwieldy book defeats this very purpose.
156
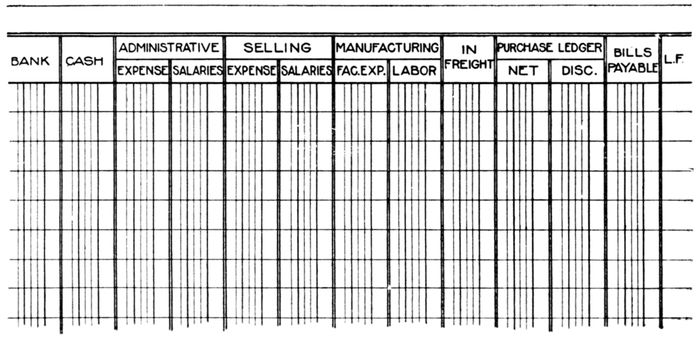
Fig. 24. Cash Journal—Left-Hand Page
While the "sundries" columns in the form shown render possible
the making of any kind of adjusting entries in this cash journal,
we recommend that it be reserved for cash transactions and that all
adjusting entries be made in an ordinary journal. This will segregate
cash transactions, just as sales and purchases are segregated,
and render much easier an audit of the books. The
journal of the ordinary type also affords abundant space for explanations
which should be exceptionally complete for adjusting
entries. Entries of this kind are frequently used to cover up
fraud and they are sure to receive the careful attention of the
auditor.
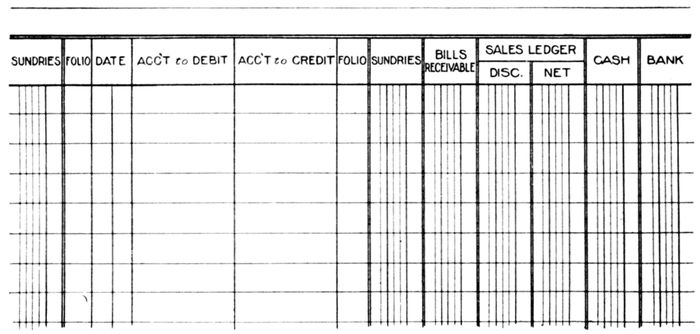
Fig. 24. Cash Journal—Right-Hand Page
157
27. In no department of a business are tabulated records of
greater value than in the sales department, for only by studying the
records of sales of different classes of goods or of different departments
can a manager determine which departments of his business
are most profitable. A tabular sales book makes it possible to record
sales in detail with very little additional labor, resulting in greater
economy of time in collecting valuable data.
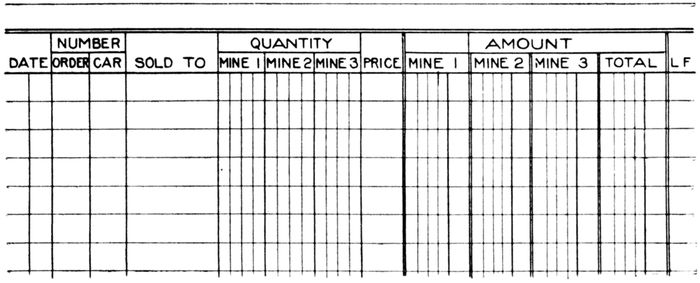
Fig. 25 a. Tabular Sales Book
In certain lines of business a record of quantities of different
kinds of merchandise sold is of almost equal value to records of values.
Examples are—wholesale coal business, in which records are kept of
quantities and values of different grades and sizes or the product of
different mines; lumber, in which sales are divided as to lumber, lath,
shingles, sash, and doors; wholesale paper, in which some of the
divisions are book, flats, bonds, cover, etc. A sales book designed
for a business of this class is shown in Fig. 25 a. This is arranged
for a record of sales in a coal business, segregating sales of the
product of each of three mines.
There are businesses in which returns and allowances are so
frequent as to constitute an important item in the record of transactions.
Such cases demand special columns in either journal or sales
book. Another condition occasionally met with is where purchases
are frequently made from customers, resulting in accounts in both
ledgers. This requires journal entries to adjust the accounts, but instead
of making these in the regular journal, special columns can be
provided for the purpose in the sales book. Fig. 25 b. illustrates a sales
158journal with columns for returns and allowances, and columns for
purchase adjustments. The total of these adjustment columns are
posted to the sales ledger controlling account.
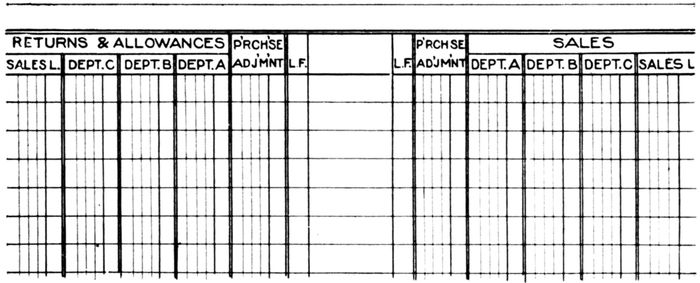
Fig. 25 b. Sales Journal with Adjustment Column
Sales recapitulations are of very great importance in department
stores and similar businesses where it is desired to ascertain the total
sales of each sales person as well as the result by departments. In
Fig. 25 c. is shown a sales recapitulation sheet arranged for daily records
of sales of each clerk and of each department. All sales tickets are
lettered or numbered to indicate the clerk, and at the end of the day
these tickets are tabulated by numbers. One of these recapitulation
sheets is used for a month's record, and it can of course be designed
to accommodate as many departments and clerks as there are in the
establishment. Recapitulation sheets arranged on this plan are found
very convenient in many lines other than department stores.
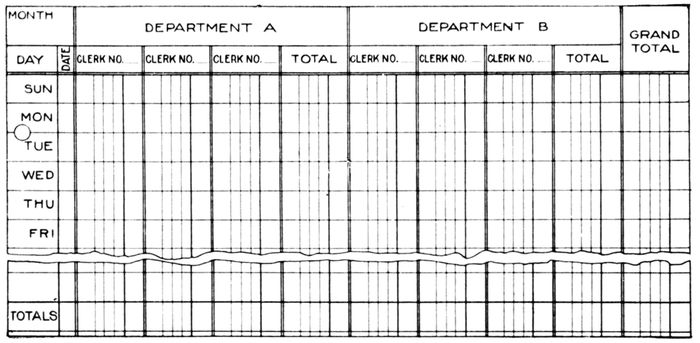
Fig. 25 c. Sales Recapitulation Sheet
159
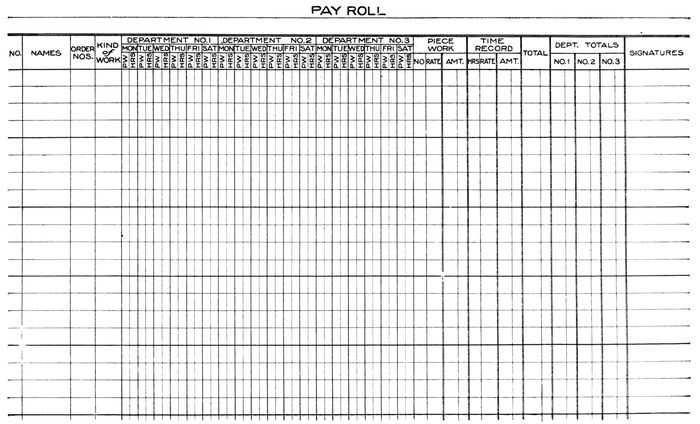
Fig. 26. Departmental Pay-Roll Record for Piece Work and Day Workers
160
28. The designing of pay-roll records to meet the special conditions
in the great variety of manufacturing industries, offers a wide
field for the ingenuity of the bookkeeper or accountant. Where all
employes are paid a stated wage and their employment in one department
is continuous, the problem is a simple one, resolving itself into a
mere record of the number of hours worked each day, the rate, and the
amount due. But this condition seldom exists.
In most industries more complex problems are encountered.
The same employe may be called upon to work in more than one
department during a pay-roll period, or he may do several different
kinds of work in the same department. In either case the form for
the record must be so constructed as to furnish complete information
relative to the cost of the different classes of work. Elaborate systems
for gathering records of time on each detail of the work are employed
in most modern factories, and the pay-roll record or time book
is arranged for a consolidation of these detailed records.
Fig. 26 illustrates a form used in one factory for a distribution
of time records where men are employed on different kinds of work
in different departments, and on both day wage and piece work plans.
In this form provision is made for the record in each department, and
each day's record is divided between time and piece work. Several
lines are set aside for each employe, so that the record will be complete
for each kind of work. At the extreme right, department totals
are extended. These are quickly calculated for the reason that while
an employe may do different kinds of work and in different departments
the same operation is not performed in more than one department.
To provide for records of more kinds of work this principle can
be carried still farther by allowing more space for each employe, and
in some cases a full sheet is assigned for each. In one factory the
pay-roll book is loose leaf, one sheet being used for each employe.
Each side of the sheet holds the record for two weeks, and by using
both sides, it gives a complete record for four pay-roll periods.
29. Combined Pay-Roll and Check Register. Many industries
pay their employes by means of checks instead of in currency. Special
pay checks are used which merchants willingly cash as an accommodation
to their customers. Whenever the check system of payments is
adopted it is best to carry a special bank account for the purpose. When
161the amount of the pay-roll is determined, a check should be drawn on
the regular bank account and deposited in a special fund against
which the pay checks will be drawn.
Fig. 27 shows a form, designed for the use of a concern paying
by check, which combines a check register with the pay-roll record.
Since all checks drawn against this special fund are pay checks, this
register gives a complete record of the special bank account.
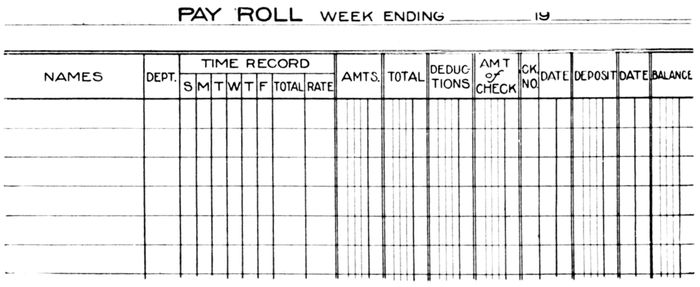
Fig. 27. Combined Pay-Roll and Check Register
162
A TYPICAL GRAIN ELEVATOR IN CHICAGO HARBOR, WITH A MODERN FREIGHTER READY FOR LOADING
TRUSTEES AND EXECUTORS' ACCOUNTS — EXECUTOR'S ACCOUNTING — FORM OF ACCOUNTS — EXAMPLES — SAMPLE ACCOUNTS — EXERCISE — ACCOUNTS WITH TRUST PROVISIONS — REALIZATION AND LIQUIDATION ACCOUNTS — STATEMENT OF AFFAIRS
163
1. From the accounting standpoint, business can be divided
into two general classes: (a) Business conducted by the owner or a
person appointed by him for the benefit of the owner; (b) Business
that is the property of persons incapable of transacting business,
necessitating the appointment, by the owners or other authority, of
persons to transact business in place of the owner. It is with business
of the latter class that we now have to deal.
In this class the owner or proprietor is supplanted by the administrator
of the business. The generic term trustee applies to the
administrator, who also takes more specific titles, depending upon
the nature of the trust—as executor, administrator, assignee, guardian,
receiver, etc. He is subject to the powers granted by the source of
his appointment, and to the restrictions and requirements imposed
by law.
A trustee—by whatever specific name designated—acting in
his capacity as substitute for the owner, is the owner of the trust
property as against the public. He is accountable to no one but the
beneficiaries for whom he is acting as custodian. As owner of the
estate, he can sue or be sued and perform many functions pertaining
to the ordinary property owner. The beneficiary, by reason of his
equity in the estate, can compel the trustee to carry out the provisions
of his trust.
2. While an executor may keep his accounts in a manner chosen
by himself, his accounting must conform to the legal requirements
of the state in which the accounting is made. The form in which
the accounting is to be made is not subject to rigid rules, but must
conform to certain regulations. While requirements differ according
to the jurisdiction, the regulations in general are as follows:
The preliminary accounting consists in filing an inventory of
the personal estate of the deceased, showing both the nominal or
164face value of the assets and the amount they are expected to realize
as stated by the appraisers. An executor usually files two accounts—an
intermediate account, filed at some date prior to the final account,
and a final account, showing the property in his hands subject to
distribution by judicial decree. The intermediate account may
be filed either voluntarily or by order of the court. The account
must be accompanied by the following schedules:
1. Statement of property contained in the inventory, which
has been sold, with the manner of sale and amounts realized.
2. Statements of debts due the estate as scheduled in the inventory,
which have been collected.
3. Statement of all interest and dividends received by the
executor.
1. Statement of debts due the estate that have not been collected
or are uncollectible, with reasons.
2. Statement of personal property named in inventory that
has not been sold, with reasons, and the appraised value of such
property.
3. Statement of all property belonging to the estate that is
lost through no fault of the executor, with the cause of loss and
appraised valuation.
4. Statement that no other property than set forth in the inventory
or schedules has come into the possession or the knowledge
of the executor.
5. Statement that the increase or decrease in value of all assets of
the deceased is allowed for or charged in Schedules A and B.
1. Statement of all amounts expended by the executor for
funeral and other necessary expenses, together with the receipts for,
and objects of, such expenditures.
2. Statement of the date when the executor caused a notice
for claimant to present claims against the estate to be published,
together with order, notice, and proof of publication herewith filed,
to which the executor refers as a part of his account.
1. Statement of all claims of creditors allowed by executor
or disputed by him, for which a judgment or decree has been rendered,
with the names of the claimants, nature of claim, amount and
date of judgment.
2. Statement of all money paid to creditors of the deceased,
with names and time of payment.
1. Statement of all money paid to legatees, widow, or next of
kin, of the deceased.
1. Statement of names of all persons entitled—as widow,
legatee, and next of kin, of the deceased—to a share of his estate, with
place of residence, degree of relationship, and statement as to which
are minors, whether they have a general guardian, and if so, the
name and place of residence to the best of the executor's knowledge,
information, and belief.
1. Statement of all other facts affecting the administration
of said estate, executor's rights, and those of others interested.
These schedules provide all the material from which to make
the account proper. In his account, the executor charges himself
as follows:
| With amount of inventory |
$_________ |
| With amount of increase as per schedule A |
_________ |
| With amount of income as per schedule A |
_________ |
| _________ |
|
| Total debits |
_________ |
He credits himself:
| With amount of losses on sales as per schedule B |
$_________ |
| With debts not collected as per schedule B |
_________ |
| With articles mentioned in inventory lost, schedule B |
_________ |
| With funeral expenses and other expenses, schedule C |
_________ |
| 166With money paid creditors, schedule D |
_________ |
| With money paid to legatees, widow, or next of kin, schedule E |
_________ |
| Total credits |
$_________ |
| Balance |
_________ |
| Add articles unsold |
_________ |
| Add debts not collected |
_________ |
| |
_________ |
| Total to be distributed |
_________ |
3. The devising of forms of trust and executory accounts
offers a wide scope for the application of accounting knowledge.
Many intricate problems arise in the interpretation of details of the
trust and in the apportionment of sums received, between capital
and revenue. Broadly, these accounts are prepared in one of two
forms: (a) An account of charge and discharge; (b) in the form of
regular ledger accounts. As has been intimated, legal requirements
are complied with by the first form, but the second form is preferable.
When ledger accounts are kept on the double entry plan, the fullest
information can be obtained about the condition of the trust at any
time, and from these accounts, the account of charge and discharge
or any form required by the court can be made for each period.
In preparing the accounts the exact relationship of the trustee
to the estate (as the property in trust is called) must be kept in mind.
As the owner of the property, he is a creditor of the estate (the
business) just as the proprietor of the business is the creditor of that
business. On the other hand, as custodian, he is a debtor, being in
possession of the property of others.
In the ledger, property accounts are opened with the different
classes of properties represented in the estate, which accounts are
debited for the appraised value of the properties. These are known
as custodian accounts.
A contra account representing the estate—sometimes called
the capital—is opened under some such caption as Personal Estate
Account. This account is credited with the combined values of all
properties represented by the custodian accounts.
167When the assets are entered and posted, the ledger accounts
will appear as follows:
These asset accounts represent the value of the individual
properties, while the personal estate account represents the combined
values of all personal property of the estate (No. 1, No. 2,
and No. 3). The personal estate is known as the corpus, distinguishing
it from the real estate.
If the trustee, as the custodian, is called upon merely to distribute
the estate to the beneficiaries, his accounting is a very simple
problem. In many cases, however, he is called upon to take care
of the income arising from the corpus or the real estate.
When he receives such income in the shape of cash, he debits
168himself as custodian through a cash account, and credits an income
account under an appropriate title—as interest account, rent account,
dividend account, etc. The account may represent the income from
a specific property, or all income of a stated class. For example,
rent account may represent the rents received from all properties,
or there may be a separate rent account for each.
Distinguished from the income accounts, the trustee sometimes
has accounts representing the sale of real estate, which must then be
treated as personal property. When real estate is sold, cash is
credited and an account, usually called Sale of Real Estate, is credited.
4. Classification of Accounts. A classification of the accounts
of the executor naturally divides into: (a) Personal estate account;
(b) asset accounts; and (c) distributive accounts. The personal
estate account, as we have seen, is a controlling account which represents
the total of all assets. It is also referred to as the capital
account. It is, as well, a controlling account of the distributive
accounts, and in the end exhibits a schedule of transactions in the
order in which they occur.
The asset accounts, representing the different classes of properties
or assets of the estate, correspond to the asset accounts of an
ordinary business.
The distributive accounts may be likened to the revenue accounts
of a business enterprise. These accounts are debited with all
amounts distributed—as expense of administering the estate—and
credited with all income or revenue other than that representing the
conversion of the original estate into cash.
5. Executors' Commissions. While the commission allowed
administrators and executors varies in different states, the amount
specified by law in New York applies as a general rule. The commission
allowed is 5% on the first thousand dollars received and
disbursed, 2½% on the next ten thousand dollars, and 1% on all
amounts above eleven thousand dollars.
If the value of the personal property is $100,000.00, or more,
in excess of all debts, each executor is entitled to receive the commissions
provided in case of a single executor; except that if there
are more than three executors, the amount which the three would
receive must be divided in proportion to the services rendered.
In cases where the will provides a specific remuneration, the
169executor is not entitled to a commission. He can, however, decline
a legacy and in lieu thereof take the usual commission.
Commissions are not allowed on specific legacies, that is, where
specific property, as household effects, automobiles, etc., are named.
An annuity is a series of legacies and the commission is not allowed
on its payment. However, when a beneficiary is given the use of a
fund, the beneficiary is charged with the commission.
In all cases where administrators or trustees are responsible
for the investment of the funds of an estate, they are entitled to receive
commission on the income. The commission in all of these
cases is at the regular rate, that is, 5% on the first thousand dollars
received and paid out, etc.
1. Two trustees collect in one year an income of $36,000.00
for a beneficiary, the expense being $3,000.00. If each trustee receives
an equal share, what commission will be paid to each, and
what sum shall be paid to the beneficiary? Ans. Each trustee,
$275.00; beneficiary, $3,275.00.
2. Executor X collects of the corpus of an estate $30,000.00,
executor Y collects $40,000.00. Together they pay out $55,000.00.
Commissions are to be divided in proportion to the amount collected
by each. What commission will each receive and what is the net
amount to be paid to the residuary legatee? Ans. Commissions:
X, $381.43; Y, $508.57. Residuary legatee, $14,110.00.
3. Four trustees collect and pay out of an estate $350,000.00,
the total debts of the estate being $135,000.00. What commission
will each trustee receive? Ans. $2,767.50.
6. Following are the transactions and accounts of David Brown,
executor of the estate of Henry Snow, deceased. For keeping the
accounts, the journal, cash book, and ledger are the books used.
| June 1, 1908 |
| Henry Snow died this day, naming David Brown executor. |
| |
| —3— |
| Estate inventoried and appraised as follows: |
|
|
| Cash in bank |
$390.50 |
|
| Mortgages |
5,000.00 |
|
| 170R. R. stocks $5,000.00 appraised @ 112 |
|
$5,600.00 |
| Household furniture |
|
1,000.00 |
| Debtors to the estate |
|
|
| Henry Alton |
$160.00 |
|
| J. L. Lawrence |
52.00 |
|
| D. Pringle |
75.00 |
|
| F. D. Smith |
84.50 |
371.50 |
| |
|
|
| Interest accrued on mortgages $5,000.00 |
|
|
| —5 mo. @ 5% |
|
104.16 |
| Accrued dividends on stock estimated |
|
|
| at 3% semi-annual, payable July |
|
|
| 1st—5 mo. accrued |
|
137.50 |
| |
|
|
| |
|
12,603.66 |
| |
| —30— |
| Approved the following claims: |
|
|
| Dr. Knight bill |
|
200.00 |
| Funeral expenses—Undertaker |
|
250.00 |
| Henry Cole account |
|
62.00 |
| H. Dawson account |
|
17.00 |
| Probate expenses |
|
100.00 |
| |
| —30— |
| Additional assets discovered |
|
|
| Geo. Smith owes the estate |
|
50.00 |
| |
| July 1 |
| Collected 6 mo. interest on mortgage |
|
|
| at 5% |
|
250.00 |
| |
| —1— |
| Collected the following accounts: |
|
|
| Henry Alton |
|
160.00 |
| D. Pringle |
|
75.00 |
| |
| —1— |
| Paid the following: |
|
|
| Dr. Knight |
|
200.00 |
| Funeral expenses |
|
250.00 |
| Henry Cole |
|
62.00 |
| H. Dawson |
|
17.00 |
| Probate expenses |
|
100.00 |
| |
| —5— |
| Received dividend on R. R. stock |
|
|
| 3½% semi-annual on $5,000.00 |
|
$175.00 |
| |
| —5— |
| Sold R. R. stock $5,000.00 @ 132 |
|
6,600.00 |
| |
| Sept. 1 |
| Collected the following account: |
|
|
| J. L. Lawrence |
|
52.00 |
| |
| —20— |
| Sold H. H. furniture |
|
790.00 |
| Depreciation on H. H. furniture |
|
210.00 |
| |
| Nov. 1 |
| Collected the following accounts: |
|
|
| F. D. Smith |
|
84.50 |
| Geo. Smith |
|
50.00 |
| |
| Dec. 1 |
| Collected 6 mo. interest on mortgage |
|
|
| $5,000.00 @ 5% |
|
125.00 |
| |
| —1— |
| Sold mortgage |
|
5,000.00 |
A GENERAL VIEW OF THE PLANT OF THE FOX TYPEWRITER COMPANY, GRAND RAPIDS, MICH.
172
173
Executor's Account of Cash Receipts and Disbursements
174
Classified Ledger Accounts of an Executor
175
Classified Ledger Accounts of an Executor
176
Classified Ledger Accounts of an Executor
177
Schedule Filed by an Executor
178
Schedule Filed by an Executor
179
7. George Williams died on March 5th, bequeathing his entire
property, after payment of all debts and funeral expenses, to the
following beneficiaries: George Williams, Jr., one-fifth; John Williams,
one-fifth; Fred Williams, one-fifth; Mary Williams, three-tenths;
and George Robinson, one-tenth.
The inventory filed by his executors was as follows:
| Stocks and bonds |
$4,000.00 |
| Mortgages |
6,000.00 |
| Wearing apparel |
100.00 |
| Cash in bank |
40.00 |
There are two executors, and their transactions are as follows:
| Cash Receipts |
| Stocks and bonds sold |
3,341.00 |
| Mortgages realized |
4,656.00 |
| Wearing apparel sold |
50.00 |
| Dividends collected on stocks and bonds |
1,800.00 |
| Interest collected on mortgages |
2,400.00 |
| Interest received on deposits in bank |
100.00 |
| Real estate sold |
1,000.00 |
| Rents collected |
720.00 |
| Cash in bank at decease, withdrawn |
40.00 |
| |
|
| |
14,107.00 |
| |
| Cash Disbursements |
| Funeral expenses |
30.00 |
| Expenses of probate |
200.00 |
| General legal expenses |
400.00 |
| Repairs to building |
220.00 |
| Stationery, postage, etc. |
10.00 |
| Accountant's fee |
80.00 |
| Debts of deceased |
500.00 |
| Taxes |
800.00 |
| Insurance |
10.00 |
| George Williams, Jr., on account of legacy |
2,200.00 |
| John Williams, on account of legacy |
2,500.00 |
| Fred Williams, on account of legacy |
2,220.00 |
| Mary Williams, on account of legacy |
3,100.00 |
| George Robinson, on account of legacy |
960.00 |
| |
|
| |
13,230.00 |
| |
========= |
180The inventory at the date on which they wish to account is as
follows:
| Stocks and bonds |
$1,000.00 |
| Mortgages |
1,280.00 |
| Cash in bank |
877.00 |
Make up summary statement of the Executor's Accounts showing
the balance due each legatee.
8. In the accounts shown in the preceding illustrations the
entire estate is distributed by judicial decree. When all of the
property has been distributed, the custodian accounts will have been
closed into the personal estate account, which in turn is closed
by the distribution of the estate. In many cases the will of the
deceased provides that certain beneficiaries shall have a life interest
in certain of the assets. Quite frequently the widow is given
the income on certain investments which will revert to the estate at
her death. This is illustrated in the following example of trust
accounts:
Edward Brown died on June 15, 1907, leaving a will which
elected that after payment of all just and lawful debts the following
legacies should be made:
To his widow, that part of the real estate consisting of his residence,
the household effects therein, and the income from $50,000.00
to be invested.
To his son and daughter, $20,000.00 each, and an equal share
of the above $50,000.00 at his widow's death.
The inventory made up for the preliminary accounting was as
follows:
| Cash in house |
$200.00 |
| Cash in bank |
1,500.00 |
| Household effects valued at |
2,500.00 |
| Stocks |
40,000.00 |
| Book accounts |
20,000.00 |
| Merchandise, fixtures, and stock in trade |
25,000.00 |
The real estate consists of
| The residence of the deceased, valued at |
15,000.00 |
| 5 houses valued at |
15,000.00 |
| (to be sold according to will) |
|
181
Executor's Accounts With Trust Provisions
182
Executor's Accounts With Trust Provisions
183
Executor's Accounts With Trust Provisions
184
Executor's Accounts With Trust Provisions
185
Executor's Accounts With Trust Provisions
186
Accounting of an Executor, in the Form of an Account of Charge and Discharge
A FACTORY CHEMICAL LABORATORY AT THE PLANT OF THE S. OBERMAYER CO., CINCINNATI, OHIO
187
Accounting of an Executor, in the Form of an Account of Charge and Discharge
188
9. A realization and liquidation account is an account showing
the result of the liquidation of a business or an estate.
It is debited with the total assets as shown by the balance sheet
or statement of affairs, and is credited with all liabilities to outside
creditors. The account is subsequently credited with the amounts
realized on assets, and debited with liabilities liquidated together
with the expenses of realization and cost of liquidation.
Realization and liquidation accounts are frequently prepared
in the form of an account of charge and discharge as shown in the preceding
pages for executor's accounts.
10. A statement of affairs is frequently confused with a balance
sheet. This is because, like a balance sheet, a statement of affairs
exhibits the resources and liabilities of a business. The difference
lies in the fact that a statement of affairs is made up partly from information
gained from the books and partly from information secured
from other sources.
A statement of affairs is used chiefly in the preparation of a
statement of the condition of an insolvent concern, or one whose
affairs have been, for any reason, placed in charge of an Administrator.
In a going business, all facts that have a bearing on its financial
standing should be recorded on the books, when the statement will
be made in the form of a balance sheet.
Statements of affairs of a going business are sometimes made
when it is desired to make a showing for a special purpose, or at a
date other than a regular closing date. When the books have been
improperly kept, a statement of affairs, or statement of assets and
liabilities, is necessary to get all of the facts properly recorded.
11. Statement of Affairs of a Bankrupt. A statement of affairs
of a bankrupt is prepared on a somewhat different basis than a similar
statement for a going concern. Such a statement is prepared for
the benefit of creditors, and should be based on the probability of the
creditors receiving their claims in whole or in part.
189
A Statement of Affairs of a Bankrupt
190On the left-hand side of the statement, the liabilities should be
listed, showing whether they are actual, contingent, or provisional;
which are preferable or ordinary, or secured partly or wholly by
assets held by creditors of the concern as security for their claims. On
the right, the assets of the concern should be shown. These should
be classified as to whether they are free for distribution among the ordinary
creditors or subject to special liability or claims and which
must be liquidated before the assets can be released for distribution.
The assets may be listed on the basis of their value in a going
concern, or on the basis of the prices they are estimated to bring at
forced sale. The best practice is to list the assets to show, in one
column, their nominal value, and in another column the amounts
they are expected to realize. The statement is prepared for the
express purpose of showing the probability of creditors—preferable,
secured, partly secured, and ordinary—receiving their claims in full
or being obliged to accept a dividend. In preparing such a statement,
therefore, the investigation should be extended beyond the
mere bookkeeping records. While the statement should be based
on the properly balanced books of account, it must be supplemented
by information from other sources.
The statement of liabilities should include, not only all of the
liabilities shown on the books of the debtor, but all other enforcible
claims, including contingent liabilities on account of the debtor's
name being on commercial paper as an endorser.
Preferable claims for taxes, wages, and salaries which must be
paid in full out of the assets of the estate, should be deducted from
the assets in order to show the net value of the estate available for
distribution among ordinary creditors. The details of such claims
should be included among the liabilities, but without extending the
amounts to the total column.
Claims of secured creditors also are entered on the liabilities side
of the statement, but are not carried to the total column. Such claims
are deducted from the assets forming the specific security held, the
balance only being included among the assets available for distribution
and carried to the total assets column.
Partly secured claims are entered among the liabilities, but the
amount to which they are secured is deducted, and the balance, which
must take the same chances of payment as other unsecured claims,
is entered in the liabilities column. The corresponding assets are
entered on the assets side but not extended.
191
A Deficiency Account Which Shows the Causes of Loss
192These adjustments are necessary to show clearly the net assets
that will be available for the ordinary creditors, and the total amount
of claims to be satisfied out of these assets.
Every statement of affairs should also have appended to it
schedules showing the fullest particulars of the different entries which
appear in the statement. The names and addresses of all creditors
should be given and the nature of the debt, whether a trading debt or
for borrowed money, should be clearly shown. Full particulars of
any security held should also be given.
It is much more difficult to ascertain the value of the assets of a
bankrupt than the amount of the liabilities. While it is comparatively
easy to get at the cost or book value of the assets, if the books have
been properly kept, it is usually necessary to write off a considerable
portion of this value to arrive at the amount likely to be realized on
forced sale. It is usually advisable, therefore, to call in an appraiser,
familiar with the line of business involved, to set the values of the
assets on the basis of a going business and on forced sale.
By showing the book value of the assets and the values they are
expected to realize, the probable deficiency as a result of the liquidation
of the estate is readily seen. Book debts should be classified as good,
doubtful, and bad. Good debts are extended at face value, doubtful
debts at the amount they are expected to realize, while the bad debts
are entered on the statement without extending any amounts.
Assets should be listed in the order of their availability, those
most readily realized being placed first. At the bottom of the statement,
in the form of a note, the dividend available for ordinary creditors,
exclusive of expense of realization and liquidation, is shown.
A statement of affairs is shown, Page 27, which will make
the explanation clear.
Every statement of affairs should, when possible, be accompanied
by a deficiency account. The purpose of the deficiency account
is to show, as far as may be, the cause of insolvency. This
account is credited with the losses and shrinkage in the estate shown
by the statement of affairs, the losses shown by the books, and the
withdrawals of the owner or partners. It is debited with the capital
at the last known date of solvency, all additions of capital, and all
profits shown by the books. The balance is the net amount of the
deficiency, and should agree with the amount shown by the statement
of affairs. A deficiency account is shown in connection with the
illustration of a statement of affairs.
STOCK EXCHANGE BUILDING, CHICAGO, ILL.
STOCK BROKERS' ACCOUNTS [4] — LARGE CAPITAL REQUIRED — GRAIN PURCHASES — BULLS AND BEARS — EXACT BOOKKEEPING NECESSARY — BROKER'S COMMISSION — SECURITIES — BUCKET SHOPS — LEGITIMATE DEALERS — CLEARING HOUSE — RING SETTLEMENT — ILLUSTRATION — COMMODITIES HANDLED — CORNERING THE MARKET — VALUE OF THE WIRE — SETTLEMENT OF CONTRACTS BY OFFSET — DEPOSITS TO SECURE THE FULFILLMENT OF TIME CONTRACTS — COMMISSIONS ALLOWED BY BOARD TO BROKERS — BOOKS AND FORMS USED — ORDER BLANK — DEBIT AND CREDIT SLIP — DAILY RECORD SHEET — GRAIN COMMISSION JOURNAL SHEET — ADVICE OF PURCHASE OF SALE — STOCK RECORD — CASH BOOK — OFFICE CASH DISBURSEMENTS — MARGIN BOOK — THE LEDGERS — CUSTOMERS' STATEMENT — BILLS PAYABLE RECORD — JOURNAL — CHECK REGISTER — GLOSSARY OF BOARD OF TRADE TERMS
195
1. The principal feature of brokerage accounting is that such
companies are not supposed to make investments upon their own
account, but to act as intermediaries or agents for those who desire
either to buy or sell.
As this is the case, such companies' profits depend entirely
upon the commission charged their clients, which is charged whether
they buy or sell for a client. There is also a margin of profit on the
interest account, as large brokerage firms are enabled to secure
money from banks at very favorable rates, sometimes much lower
than the regular six per cent charged to customers.
The legitimate broker actually buys and sells, as instructed
by his client. If a customer instructs the broker to buy one thousand
shares of D. & R. G. preferred at 88½, the customer deposits
the margin required by the broker, usually 10 per cent, and the
broker at the first opportunity thereafter, buys in open market the
one thousand shares of D. & R. G. stock ordered, paying in full for
the same. The customer may have a certain time to take up this
stock, say thirty or sixty days, but as he is still indebted to the company
for ninety per cent of the purchase, he is required to pay six
per cent interest upon the deferred payments until such time as the
stock is finally taken up and paid for.
2. It will be seen that in a multitude of transactions of this
character, a very large amount of money is required by the broker,
to carry on his business successfully. As very few of them have
the amount of capital necessary, they resort to bank loans. Banks
are very willing to loan money with listed stocks as collateral security,
and frequently do so at favorable rates for the broker. This rate
is determined by the condition of the money market, but is invariably
less than the rate of interest charged to the client.
196
3. Purchases of grain at a stipulated price differ from stock
purchases, inasmuch as the full amount of the purchase does not
have to be paid until the delivery of the goods, although there are
frequently charges, such as storage and insurance, which must be
made upon long time purchases. These charges do not accrue,
however, until after delivery. If a customer buys fifty thousand
bushels of wheat in April for September delivery, the purchase is
made by the brokers at the earliest date possible, in order to avoid
any fluctuation of the market. When the broker makes the purchase
he pays over the amount necessary to secure the same. If
the deal is carried through to maturity, the grain is delivered to the
broker who has made the purchase for his client, and is in turn delivered
to the client upon the payment of the balance due, including
all charges upon the same.
It is frequently the case, however, that before the actual delivery
takes place, the client has ordered the broker to sell a sufficient
amount to cover the deal. This may be either at an advance or a
decline from the price purchased, but in either case the broker receives
his commissions for both transactions—buying and selling.
4. Investors who are always figuring upon an advance in
prices are termed bulls, and those who are confident of lower prices
are termed bears. If a seller sells for future delivery what he does
not own, he is termed short and becomes temporarily a buyer, in
order that he may have a sufficient amount to fill his orders. If a
buyer holds stock or grain for a rise, or contracts for future delivery,
he is termed long and becomes temporarily a seller, seeking to bring
his holdings down to the normal demand.
5. It will be seen from the nature of the business that the
bookkeeping department must be very exact, careful in its dealings,
and as prompt as a bank in its action. Every precaution must be
taken to safeguard the broker and protect the customer. The
accounts must show, with each transaction, the brokerage or commission
charges and, as in active times the transactions are very
numerous, they must be quickly and accurately recorded in the
books of the company.
197
6. The percentage or commission due to the broker is included
in the amount deposited to protect the deal, which is called a margin.
If there should be a decline in price of either stock or grain, sufficient
to cause the broker to feel insecure, he always reserves the right to
call upon the customer for an additional deposit, even though the
time of delivery has not yet arrived. In case the customer fails to
make such additional deposit, the broker can sell the securities,
grain, or other purchase, at once, in order to protect himself; the
amount primarily deposited by the customer is thereby forfeited.
All orders for the purchase and sale of any article are received
and executed with the distinct understanding that actual delivery
is contemplated and that the party giving the order so understands
and agrees.
7. It is understood and agreed between the broker and his
client, that all securities carried in his account, or deposited to secure
the same, may be carried in the broker's general loans, and may
be bought or sold at public or private sale without notice, when
such sale or purchase is deemed necessary by the broker for his
protection.
It is also understood and agreed that the right is reserved by
the broker to close transactions on all accounts without notice,
when protection is exhausted, or when, in his judgment, it is near
enough exhausted as to endanger the account, and the broker reserves
the right to settle contracts with his client, in accordance with
the rules and customs of the exchange where the order is executed.
8. The class of brokerage concerns termed bucket shops are
those which do not actually carry out the orders of their customers,
who neither buy nor sell anything, but who expect quick deals, frequent
changes and, speaking plainly, merely gamble with their
clients, allowing them to take whichever side they prefer. The
large margin which this fraternity receives is a commission on deals
whether they win or lose.
198In order to maintain at least a pretense of legality, there must be
an actual transfer of all stocks and commodities speculated in. The
broker must acquire nominal possession of something which represents
stocks, grain, cotton, or other commodities. To do this he
must borrow money from the bank, or borrow stock or warehouse
receipts from those who have them to lend. In either instance he
charges interest to his speculative customers.
It is estimated that the brokers in New York City who are members
of the various exchanges, have an average amount in call loans
outstanding of about $600,000,000.00, all of which vast sum is used
to finance the orders of the brokers' customers. In dull times the
minimum falls as low as $350,000,000.00, but there have been periods
of speculative activity when $1,100,000,000.00 have been thus employed.
The interest rate charged brokers constantly varies, but
those who have had dealings with them state that their accounts
rarely show less than five per cent interest. The broker charges
the customer six per cent, thus averaging one per cent profit upon all
money borrowed.
The New York Stock Exchange was founded for a high and
honorable purpose, the same being true of the New York Produce
Exchange, The Chicago Board of Trade, and other institutions for
coöperative trading and the determination of values, in accordance
with the recognized codes of business, and in conformity with the
laws of supply and demand. Such exchanges serve admirably the
producer and the merchant. They have a valid function to the
investor in railroad and corporation securities, and are indispensable
in facilitating the massing and distribution of capital required by
large commercial enterprises.
9. Every legitimate brokerage concern has its representative
or representatives on the board of trade in the city wherein it is
located, and they are members in good standing of the board. When
an order is given by a customer, either through the wicket or by wire,
it is immediately transferred to the floor man and he proceeds to
buy or sell as the instructions are given. In an active market the
client must take the chances of slight fluctuations, which are just as
likely to be in his favor as against him. The floor man reports the
199sales or purchases as soon as made, with the price paid and from
whom purchased. The entries are immediately made to the customer's
account.
10. The boards of trade in different cities maintain a clearing
house somewhat similar to that used by the banks, to settle the deals
of each member of the board each day. The deals consummated
during the day's session are reported to the clearing house and the
amounts due from and payable to each firm or individual member
are computed. If the brokerage firm has purchased ten thousand
dollars more than it has sold, a check is given to the board for ten
thousand dollars, as there must be some other firm or firms who
have sold more than they have purchased to whom this ten thousand
dollars is due, and to whom it is paid. Deliveries of stock are made
at the time the balance is paid.
11. At the close of the day, settlements for grain purchases
are made between brokers at an agreed settlement price. If brokers
have bought and sold to each other in varying amounts, only the
difference in the price is adjusted with each other. What are called
ring settlements save considerable time, money, and labor. The
ring settlement is a settlement between three or more parties without
the necessity of margining and may be illustrated in this manner:
A has bought 50,000 bushels of wheat of B, and has sold 50,000
bushels to C. By inquiry, it is found that C has sold 50,000 bushels
to B. It is ascertained that the transactions between A, B, and C
offset each other, and instead of each party being obliged to put up
margins upon each transaction, a settlement may be effected by
paying the difference in price, as the sale from C to B may be at a
different price from the sale made by B to A, and the sale made by
A to C, may have been at a still different price. By the adjustment
between the different parties of the difference in price, the necessity
of margining by A, B, or C is rendered unnecessary.
A bought 50,000 bushels of wheat of B at $1.23; A sold 50,000 bushels
of wheat to C at $1.23½. By making up the ring it was found that C has sold
to B 50,000 bushels at $1.22½. In making the settlement it is found that C
200is indebted to B ½ cent per bushel for the amount sold, as B sold at ½ cent
advance; C is also indebted to A ½ cent per bushel as he purchased of A at a
½ cent advance on the price A bought from B. The settlement of this deal
would be made by C giving his check for the amount due to B and to A, and
there would be no necessity for any one of the three brokers putting up a
margin on the deals. The amount of grain is offset one by the other, and the
difference in price has been adjusted by payment of cash.
12. The commodities that are handled upon the board and
by brokers in general—food stuffs—are wheat, corn, oats, pork,
lard, and short ribs. The various listed stocks are also bought and
sold, a considerable business is done in bonds, and in some exchanges
mining properties are listed, bought, and sold; although the latter
is not common in the larger and more important exchanges. Cotton
is a very important factor in some exchanges, and tobacco in others.
13. To corner the market is to offer to buy and be prepared to
carry out your offer, for an amount more than is offered for sale,
thus causing the price to advance. Sometimes this is done by large
operators to their advantage and sometimes, in spite of their large
purchases, which encourage a rising market, the prices fall before
their deals are consummated, and they are left high and dry with a
considerable loss instead of a large profit. The bull who tries to
run a corner has a strong foretaste of what it means to advance
sensationally, a staple article of consumption. Stocks and bonds
may be hoisted ever so high; real estate may be boomed to far beyond
its intrinsic or even potential worth—the public has no objection;
the process is, in fact, rather pleasing to it. A lift in cereals
or cotton above the normal lines encounters many protests and the
higher the lift, the more savage the protest. This of course does not
include the farmer or planter, unless he has disposed of his output;
then he willingly enough joins the chorus of protestation.
14. The telegraph is a very important factor to the grain and
stock broker, as a large majority of their business is done by wire.
Many of their clients are distributed through the country and keep
201close watch of the fluctuations of the market, sending their orders
by wire, at what they consider an opportune time.
Most brokerage firms have a number of customers outside of
the city, and these customers as well as those in the city who are
large buyers, keep a considerable deposit on hand with the broker
at all times. This deposit is frequently augmented by advantageous
sales or decreased by losses, commissions, and interest charges. Reports
of the condition of customers' accounts are made with frequency
and any customer who finds that he has more money in the
hands of the broker than is considered necessary, can secure part
of the same by asking, or if he desires to close all transactions, the
total amount due him is paid over at once. All amounts thus deposited
are credited to customers' accounts and properly taken care
of through the bookkeeping department.
15. To quote from the rules of the Chicago Board of Trade:
In case it shall appear that the delivery of any outstanding trade or
contract between members of the association may be offset by some other
corresponding trade or contract, made by the parties with other members
of the association; and the parties to such trade or contract, or their authorized
agents, consent to such offset, such trade or contract shall be deemed to
have been settled; any balance between the current value of the property
covered by such trade or contract, and the several contract prices shall be
due and payable immediately by the party from whom such balance may be
due, to the party entitled to receive the same under his contract.
This is the rule applying to ring settlements hereinbefore described.
To quote further:
"MARKET VALUE TO BE POSTED
The current market value of the property contracted for shall be conspicuously
posted, at a stated hour each day, under the direction of the Board
of Directors, in the Exchange Hall and in the Settlement Room of the Board,
which posting shall serve as a basis for the adjustment of all contracts settled,
as herein provided on that day.
"ADJUSTMENT OF BALANCES ON SETTLEMENT
In order to facilitate the operation of this section, each member is
required to keep a settlement book, in which shall be entered the names of parties
with whom settlements have been made and the dates and terms of the trades
included in such settlement, and the terms of such settlements, and the prices
at which the commodities were originally sold or purchased, and the amounts
due to or from him or them on each separate settlement, also the net amount
due to or from him or them on all settlements.
202 "CLEARING HOUSE AND REPORTS
The Board of Directors is hereby authorized to provide a suitable office,
with the necessary employes, to which members shall be required, at stated
hours each day, to make reports, showing the net balance due to or from each
member, as shown by such settlement book, and also the general balance due
to or from him or them upon all such settlements; each report to be accompanied
with an acceptable check for the balances, if any, due from him or them
on the contracts so settled; whereupon, if said report is found to be correct, as
compared with other reports rendered him, the person in charge of said office
shall, at a stated hour each day, pay to each of the parties making such report
any balances which he may have collected, and which shall appear to be due
to them by said reports, less such charges as shall be prescribed by the Board
of Directors as compensation for the services of said office.
"CONFIRMATION OF TRANSACTIONS FOR FUTURE
DELIVERY, ETC.
It shall be the duty of each member or firm making a transaction for
future delivery of grain or flax-seed in five thousand or one thousand bushel
lots, lard and pork in two hundred and fifty or fifty package lots, and D. S.
short ribs and D. S. extra short clears in lots of fifty thousand or twenty-five
thousand pounds, under the Rules of the Association, to confirm such transaction
by sending to the clearing house a memorandum of the same by 6
o'clock P. M. of the day on which it is made; such memorandum shall be in
writing, and shall state on its face the date of the transaction, the quantity
and kind of property covered by the same, the month of delivery, the price,
and the name of the party to whom sold or of whom bought, and shall be
signed by the party or firm making the same. All transactions of the same
date made with any member or firm may be included in one memorandum,
and all such memoranda shall be sent to the clearing house by the member or
firm making the same, in unsealed envelopes addressed to the member or firm
with whom such transactions were made. It shall be the duty of the clearing
house manager to assort and have ready for delivery by 8 o'clock A. M. of
the following day, and to deliver, on application, all envelopes containing
such memoranda as are left with him in compliance with this section.
There is a fine imposed upon any member failing to comply
with the above provisions.
"FAILURE TO DELIVER OR RECEIVE ON CONTRACT
In case any property contracted for future delivery is not delivered at
maturity of contract, the purchaser may, if he shall so elect, consider the contract
forfeited; or he may purchase the property on the market for the account
of the seller, by 1:15 o'clock P. M. of the next business day, notifying him at
once of such purchase; or he may require a settlement with the seller at the
average market price on the day of maturity of contract, and any damages
or loss due to the purchaser, by reason of such purchase or declared settlement,
shall be due and payable by the seller immediately.
A SECTION IN THE GENERAL OFFICES OF THE SIMMONS HARDWARE COMPANY, ST. LOUIS, MO.
203In case any property contracted for future delivery is not received
and paid for when properly tendered, it shall be the duty of the seller, in order
to establish any claim on the purchaser, to sell it on the market at any time
during the next twenty-four hours, at his discretion, after such default shall
have been made, notifying the purchaser within one hour of such sale; and any
loss resulting to the seller shall be paid by the party in default.
Fig. 1. Memorandum of Deposit with Broker to Secure Contracts
16. The rules of the board of trade provide that on time
contracts, purchasers shall have the right to require of sellers as
security, a deposit of ten per cent, which amount is based on the
contract price of the property purchased; they are also further allowed
to demand security from time to time to the extent of any advance
in the market value above selling price. Sellers shall have the
same right on property sold, and, in addition, any difference that
may exist or occur between the estimated legitimate value of any
such property and the price of sale. It is required that all securities
shall be deposited with the treasurer of the association or with some
204bank duly authorized by the board of directors to receive such deposits.
The board requires in each instance a memorandum which
shall state the name of the depository, the date on which the deposit
is made, the name of the depositor, and also the name or names of
the party or parties in whose favor the deposit is to be made, together
with the amount of such deposit in detail and also in the
aggregate. The left-hand part of the memorandum is retained by
the depository selected, the right-hand portion thereof being taken
by the depositor after being duly signed by the person authorized
to receipt for the said deposit, and without delay this memorandum
must be placed in the office of the clearing house. A detail of this
memorandum is shown in Fig. 1.
Upon the fulfillment or settlement of any contract or upon the
closing of any contract—deposits upon which have been made—when
the full adjustment of all differences relating to the same shall
have been effected, the deposit shall be paid to the party depositing.
17. The commissions to be collected by brokers from customers
are fully prescribed by the board of trade in each city and do not
materially differ. While it will not be possible to give all the rates
of brokerage or the charges allowed for buying, selling, or accounting,
the commissions allowed on the Chicago Board of Trade for buying
or selling, or for buying and selling, are as follows:
For the purchase, or for the sale, or for the purchase and sale by grade
alone of wheat, corn, or oats, to be delivered in store, either for immediate or
for future delivery, one-eighth of one cent per bushel.
For the purchase, or for the sale, or for the purchase and sale, by grade
alone, of rye, barley, or flax-seed, to be delivered in store, either for immediate
or for future delivery, one-quarter of one cent per bushel.
For the purchase, or for the sale, or for the purchase and sale of lard,
six cents per tierce.
For the purchase, or for the sale, or for the purchase and sale of pork,
five cents per barrel.
For the purchase, or for the sale, or for the purchase and sale of D. S.
short ribs, or D. S. extra short clears, twenty-five cents per thousand pounds.
The minimum rates allowed upon the above transactions made for the
account of members of the board are one-half of the foregoing minimum rates.
18. There are a number of ordinary forms, such as checks,
drafts, receipts, requisitions, etc., that are common with most lines
205of business and used in the brokerage business, which will not be
necessary to reproduce. Most brokers have all such forms printed
or lithographed for their especial use with their name and address
prominently displayed thereon.
Fig. 2. Telegraphic Buying and Selling Orders
19. The first form of importance in connection with the accounting
department of a brokerage firm is the order of the customer.
This must invariably be in written form with the signature of the
customer and the order must be expressed in the plainest terms so
that there is no possibility of misconstruction. As these orders are
frequently received by wire, or often dispatched by wire to New
York or other branch office for execution, blanks for the purpose,
as shown in Fig. 2, are furnished to customers, those used for buying
orders being printed in black and those used for selling orders being
printed in red. These orders are made out by the purchaser or
206his authorized agent and should not only show the date of the order
but also the time of the day it was given, which is frequently of great
importance in an active market. Whatever margin is required by
the broker upon the deal must be deposited by the client at the time
the order is given, as without this protection, the broker will not
proceed to execute the order. It is sometimes the custom for brokers
to accept collateral covering a certain amount of margin, in which
case the broker gives the customer a receipt in due form, holding
the collateral as trustee until settlement of account. All orders are
executed at the earliest possible moment after their receipt. Legitimate
brokers are members of the board of trade often in various
cities and have their representatives on the floor, during the business
hours of the board, to buy or sell as ordered.
Fig. 3. Credit Slip Given to Customer by Broker
20. As soon as the transaction is accepted by the broker, he
gives to the customer a debit or credit slip showing the nature of
207the transaction, or it is sent by mail, as soon as possible after business
hours; the charge or credit depend upon whether it is a purchase
or a sale. The blanks for this purpose, as shown in Fig. 3, should be
printed on different colored paper; the debit blank is usually on white
and the credit blank on buff or yellow paper. If a client buys, the
amount of his purchase appears as a debit to his account, with the
commission added. He receives credit for whatever amount of
margin he deposits, and the account stands thus until delivery, when
the entire balance must be paid. If a sale is made by the client before
the time of delivery, the amount of the sale is credited to his
account, less the commission due for selling and any other charges.
The difference in the account, whether it is an amount due from the
broker to the client or from the client to the broker, is paid in cash
as soon as the deal is closed.
Fig. 4. Daily Sales Journal or Record of Stock Sales
208
21. As a most perfect record must be kept of every transaction,
the daily record sheets, as shown in Fig. 4, are of the greatest importance.
This book is called the daily journal as frequently as it is
designated the daily record.
Fig. 5. Daily Sales Journal or Record of Grain Sales
This book is most convenient when kept in loose-leaf form, as
a small number of leaves may be kept in the binder for current use,
and after the sheet is filled, it may be filed away for future reference.
The size of the sheet is usually 16 by 14 inches, and it is ruled and
printed to show date, remarks, shares, stock, price, charge stock
account, commission, credit account of, and folio. The purchase
blank for this record is exactly the same with the exception that it is
used to credit stock account instead of charging, and to charge customers'
accounts instead of crediting. There should also be a grain
sales sheet and a grain purchase sheet, which differ slightly in the
column headings but not necessarily in the ruling—number of bushels
209taking the place of the column headed shares, and kind of grain
taking the place of stock, as shown in Fig. 5. There should also be
a sundries sales and purchase sheet for recording orders upon other
commodities than grain or stock. Its form is the same as that shown
with the exception that amount takes the place of shares, and commodities
the place of stock in each form.
Fig. 6. Special Journal Used by a Grain Commission Company
As soon as an order is received, it is entered upon the proper
record with all of the particulars, and the postings to customers'
accounts are made daily, but the posting to the general ledger accounts
need not be made more frequently than once a month, unless
it is desired to take off a general ledger balance at more frequent
intervals.
210
Fig. 7. Daily Advice of Purchase or Sale Rendered to Customers
211
22. In this connection it is advantageous for the student to
study the journal form used by an exclusive grain commission company,
Fig. 6. This form is used for recording the sales as they are
made in a manner similar to that described in the daily record sheet.
The form is loose-leaf and may be 11 by 14 inches in size, or if
preferred could be made 16 by 14 inches, giving the advantage of
a longer page. The necessity for a long or short page is determined
altogether by the amount of business done by the house in one day,
as it is the intention with this record to use one full page or more for
each day's transactions. This journal bears the day and the date at
the top of the page, and is ruled and printed to show columns for
folio, names, number of sale, net proceeds, insurance, sack rent,
freight and charges, commission, and total. The entries in this
journal are made from the sales sheet, and the total amount is posted
to the ledger for customers from this medium.
Fig. 8. Record of Stocks in Hands of the Broker
23. A very important document used by commission merchants
and brokers is the advice or notification to customer of their
212action in filling his orders. This advice is rendered daily to each
customer and should be checked by him carefully, so that there
may be no errors in the deals and no differences in opinion between
the client and his broker. The advice would begin with the date
and read something like this: "Mr. Geo. Bronson, Milwaukee, Wis.:
We have this day bought for your account and risk, 100 shares
American Car and Foundry (preferred) at 111⅛; 200 shares Canadian
Pacific at 177; 100 shares Pullman at 187." On the lower part of
the form, as shown in Fig. 7, are printed the rules of the house in regard
to the order and it should be signed by some one in authority.
If the customer accepts the same, it is an evidence that the transaction
is according to orders.
24. Owing to the fact that a very large amount of stock of
various companies is being bought and sold continually by a brokerage
firm, no book kept in the accounting department is of greater
importance than the stock record. Not only is the broker's business
with customers but it is also very largely with other brokerage concerns
as he is buying and selling continually. Every share of stock
which is bought or sold must be recorded in the stock record. This
record shows: Record number, date, number of certificate, number
of shares, from whom received, in name of, record number, number
of shares, to whom delivered, and date of delivery, as in Fig. 8.
It is not necessary in this book, to keep a record of either the price
paid or the price at which sold, as this register is intended merely to
show the disposition of the certificates of stock and whether they are
still in the house, or if disposed of, to whom they have been delivered.
It is needless to point to the necessity for the greatest care
in keeping this record, as any errors might make it very difficult to
trace the paper and result in loss, or at least considerable trouble
for the house.
25. The general cash book for a brokerage firm in loose leaf
should be sheet size 14 by 14 inches. In a bound book, it would not
be necessary to have it more than 12 inches wide. In this particular
business, it is not desirable to carry the general cash debit on one
213sheet and the general cash credit on another, although it might
be advantageous in certain cases to run the grain in the general
cash book and to keep a subsidiary cash book for the stocks, which
might be run upon similarly ruled sheets, the total of the day's transactions
being brought into the general cash at night. By doing this
the posting clerk could be using one of the cash books while the cashier
was working on the other.
Fig. 9. Broker's General Cash Book
At the heading of the general cash sheet appears the sheet
number and either the date (providing one sheet or more is used for
each day), or the month with an extra day column, next to the margin.
The columns are ruled and printed to show stocks, grain, and general
ledger on the debit side and the same on the credit side, with
the posting columns and sufficient room for the names of customers
in center, as in Fig. 9. In this cash book should be entered all payments
for margin on purchases of either grain or stock, all deposits
by customers, which should be carried into the column indicated
214by their account—if they deal in grain their account is in the grain
ledger and if in stocks their account is in the stocks ledger. All
items of receipts or expenditures, not from or to customers, should
be entered in the general ledger column, except as shown in the subsidiary
cash sheet called office cash disbursements. Cash book sheets
should always be paged consecutively when made, and each sheet
accounted for, if loose-leaf cash books are used.
The best binder to use for a loose-leaf cash book is a flat opening
spring back holder, in which may be placed enough leaves to last
for the month, to be used for the current work, and when the new
month is started the sheets for the previous month are placed in a
reserve binder—which should be of the sectional post variety—for
reference. If the back of the binder is labeled as the front and the
leaves are reversed when placed in the transfer binder, they will
run consecutively as to pages and dates.
At the end of the month the totals of the grain ledger and stocks
ledger are brought into the general ledger column and posted to the
controlling account for that ledger.
26. As there are a number of disbursements for office help,
advertising, telegraph, etc., that should be kept separate from the
general cash, it is very desirable to establish an office cash fund. This
fund is started by charging to office cash in the general ledger a
definite amount, say $500.00, which amount is drawn from the bank
or set aside for special checking for the payment of all miscellaneous
bills or drawings of principals on account of salary, also the drawings
of salaried employes. This account may be as large as is required
for the purpose, and when the office cash becomes depleted, more is
drawn which can be added to the account. At the end of the month,
a statement is made of the totals of the different columns which should
be a duplicate of the office disbursement sheet. These totals are
entered in the general cash posted therefrom, a check given for office
cash disbursements for the amount of the interest, say $500.00, and
credit given the account for the difference in the amount spent as
shown by the statement.
215
Fig. 10. Detailed Record of Office Cash Disbursements
216The office cash disbursement sheet, shown in Fig. 10, should be
14 by 16 inches in size, with sheet number and month of, in the heading.
The box headings are as follows: Day, item, posting, general ledger,
salaries, office help, advertising, private wire, tickers, telephone and
telegraph, special commissions, rent, and sundries. The office cash
balance should be kept independent of the general cash balance and,
preferably, by another clerk.
Entries should be made as money is disbursed, with the proper
vouchers for the same, to be turned in with the report.
Fig. 11. Record of Margin Balances to Protect the Customer's Account
The totals of the different accounts, having been entered in the
general cash, are posted to the debit of their respective accounts in
the general ledger.
In localities where cotton is largely dealt in, or where tobacco
is largely dealt in, it may be necessary to add columns for the tobacco
ledger or the cotton ledger in the general cash, but in localities where
the transactions are not frequent, the accounts for such transactions
and also the deals in provisions are carried in the grain ledger.
217Any cash book sheet which should happen to be spoiled should
be marked void in red ink, and filed in its regular order with the
other cash sheets, but in no case should it be destroyed.
27. It is as necessary in the brokerage business to know the
condition of customers' accounts as it is in a bank, and perhaps a
little more so, as fluctuations in the market may wipe out his margin
without his knowledge, and while it is not absolutely obligatory on
the part of the broker to notify his customer, still it is very much to
his interest to do so.
The margin clerk has the balance of each customer every morning.
All orders to buy or sell received during the day pass through
his hands and he makes the necessary memorandum against the
customer's account. He keeps posted on the fluctuations of the
market and immediately notifies the principals of any account which
needs protection. After the trading for the day is finished, which
on the board is 1:15 o'clock P.M. on any day except Saturday, and
Saturday at 12:00 M., the margin clerk extends the balances of the
various customers' accounts, these balances are checked by the bookkeeper
from his accounts to prove their correctness, and a new list
of the balances is made for the use of the margin clerk the following
day.
This book is kept in most houses as a form of blotter, but the
best form is a short sheet with numbered lines for the names of customers
and a long sheet with similarly numbered lines divided into
inch columns, with the balance column at the beginning and at the
end, to be inserted under the short sheet, to care for the transactions
of the day. By this means the names of customers will not have to
be duplicated daily.
The sheets should be kept in a holder so that the names run
alphabetically and the initial letter of the names on one short sheet
should be penciled upon the long sheet each day. The bookkeeper
can, if desired, have a duplicate set of the short sheets, shown in Fig.
11, to use for making up the balances for the succeeding day.
Where there are a sufficient number of accounts to warrant,
they should be divided by tabbed index sheets with a leather tab
projecting, in alphabetical arrangement, so that any account may
218be turned to instantly; for instance, if the account of L. S. Tucker
& Co. is wanted, turning up the tab T will bring to light all of the
customers whose names begin with T. This index may be further
subdivided if it is deemed advisable.
The sheets for each day's work should be dated at the beginning
of the day and may be kept, if desired, for reference, although after
they have been proven by the books, they are of no practical value.
Fig. 12. Ledger Account of Each Stock Handled
28. Stock Ledger. Some brokerage firms, besides keeping the
stock record, keep a stock ledger, opening an account with each line
of stock bought or sold and posting therein daily from the orders.
This ledger account, with each class of stock, indicates at all times
just how much of each line is held by the house and is very necessary
in order to show what may be sold if occasion demands. As a large
amount of stock held by brokerage firms is usually deposited with
their bank as collateral for loans, and, as it is frequently the case that
portions of this stock must be delivered to customers or sold upon
their order, it is necessary to frequently change the collateral deposited
with the bank, substituting other stock for that taken from the bank.
BASEMENT SHIPPING PLATFORM, FARWELL, OZMUN, KIRK & CO. (WHOLESALE HARDWARE), ST. PAUL, MINN.
219
Fig. 13. This Shows a Variety of Rulings for the Customers' Ledger
220The stock ledger form in loose leaf is 13¾ by 14 inches, and the
name of the stock should be inserted in the heading. It is ruled and
printed to show: Date bought, preferred, common, extra column,
price, account, date sold, preferred, common, extra column, and
price, as shown in Fig. 12. Each sheet should have a number,
and these numbers should follow consecutively. There are two
ways of indexing these accounts. The one strictly in accordance
with the theory of loose leaf is the insertion of the sheets in their
proper alphabetical sequence. When the accounts are carried in
this manner, leather tabbed index sheets appear at intervals throughout
the ledger or ledgers. The division of the alphabet depends
entirely upon how many accounts it is necessary to run and ledgers
may be alphabetically subdivided into from twenty-five to two hundred
divisions. The better the subdivision, the easier it becomes
to turn to an account.
Since the majority of listed stocks are designated by initials or
abbreviations in order to handle them with greater ease, some firms
prefer to run the stock ledger on the numerical plan. By this plan
each account is numbered and the accounts follow consecutively.
Tabbed index sheets occur at intervals of from ten to twenty numbers,
showing the location of any numbered account. With this arrangement
it is necessary to keep a separate index of the various listed
stocks, with their respective numbers, and to find an account the number
of the stock must first be ascertained. By constant handling
and entering, the bookkeeper becomes very familiar with the numbers
and it is but little trouble for him to locate an account. The
greater difficulty would be for someone who is unfamiliar with the
books to find an account when wanted. Owing to this fact, the
alphabetical arrangement is preferred.
29. Customers' Ledger. Brokers who deal in grain and other
food products, cotton, and stocks, usually require ledger sheets
slightly differing, to keep a record of customers' accounts. The
different rulings are not frequently used for the same customer, as
those who deal in grain are not often stock manipulators. As interest
221is charged to the customer for deferred payments upon stock
deals, this item must be taken care of in the ledger. Upon grain
transactions, the balance on the purchase price is not paid until the
delivery of the goods, consequently there are no interest charges
upon these accounts until after maturity.
Fig. 13 shows rulings of six ledgers used by prominent brokerage
houses in Chicago and St. Louis, and a study of the different forms
as to the columnar arrangement will show how varied are ideas in
regard to ledger rulings. All of these forms are useful, and the choice
is merely a matter of individual preference. One thing which should
be borne in mind in regard to ledger rulings is that the information
shown in the ledger account should be exactly the same as that which
it is necessary to convey to the customer in his monthly or weekly
statement. The reason for this is that it should never be necessary
to refer to any book except the ledger in preparing customers' statements,
and it will be noticed in the statement of Logan & Bryan,
shown later, that it is not only a reproduction of the ledger account
as to matter contained therein, but also follows it exactly in form and
ruling.
This book is used the same as any other loose-leaf ledger with
the exception that there is much more detail entered in these ledger
accounts than is usual in a mercantile business.
Not more than one account should be entered on one leaf, for
the reason that it is impossible to maintain a perfect alphabetical
arrangement unless each account is absolutely independent.
After the names have been entered, the ledger sheets should
be arranged alphabetically under each leather tabbed indexed subdivision.
This arrangement should be carried, if necessary, to the
fifth or sixth letter and when names are the same, like Smith, they
are indexed alphabetically by initials. The brokerage business is
one where there should be no loss of time in referring to accounts,
hence the more perfect the indexing the more easily the account is
located. Ledgers can be balanced daily by the aid of an adding
machine without writing off the amounts of the balances.
The binders to use for this ledger are a current binder for active
accounts and a transfer binder for closed accounts.
Postings should be made from the daily record sheet to the ledger
as soon as possible after the consummation of the deal, and the postings
222from the cash book must also necessarily be kept up to date.
At any moment the statement of the customer may be required, and
it would be quite inconvenient for the broker if, on account of delayed
posting, the statement were incomplete or incorrect. The number
of customers' ledgers that should be kept depends entirely upon the
number of customers. One loose-leaf ledger binder will accommodate
at least five hundred accounts, and if the number exceeds this, two
current binders should be used. By keeping the ledgers well gleaned
and transferring closed accounts to a transfer ledger, the active
accounts only remain in the current binder, which facilitates posting,
statement making, and reference.
Fig. 14. Conventional Balance Form for General Ledger
Some firms use the vertical filing drawer for transferred accounts
instead of placing them in another binder, as it is much easier to
secure these accounts for replacement in the current binder in case
the account is reopened.
30. General Ledger. A general ledger should be kept for the
personal accounts of members of the firm, controlling accounts of subsidiary
223ledgers,
controlling account
of bills
receivable and
bills payable, and
all impersonal
accounts. This
book may be in
loose leaf if desired,
although
many firms prefer
to use a
bound ledger for
this purpose.
The best form is
the regular four-column
ledger,
debit, credit,
debit balance,
and credit balance,
as in Fig.
14.
The periodical
statement of the
condition of the
firm is taken
from the general
ledger, and all
subsidiary books
controlled
through its accounts
must balance
with the
amounts shown
therein.
Fig. 15. Broker's Statement to a Customer, Which is a Duplicate of his Ledger Account
Most large
brokerage houses
have branches in
224different cities and it is necessary to keep accounts in the general
ledger with each of these branches showing the expense of the branch
and the receipts therefrom, taken from the regular statements furnished
at whatever period required. It is very necessary that the
profits or losses from these branches be readily computed as it might
be deemed expedient, if it were known that the branch was not doing
well, to discontinue it. Frequent statements, complete in their
nature as to receipts and expenditures, should be demanded.
The principal expense accounts of a brokerage firm are salaries,
rent, private telegraph wires, telephone booths, tickers, advertising,
special commissions, and sundry expenses. As before stated, the
receipts are from commissions and interest. Commissions accruing
to brokers from the sale of stock are twenty-five cents per share—twelve
and one-half cents for sales, and the same amount for purchases.
31. In a brokerage and commission business, customers are
very likely to demand a statement at any time, and even should they
not do so, it is deemed expedient to make statements to customers
often enough to keep them fully posted regarding the condition of
their accounts. The best form of statement to use for this purpose
is shown in Fig. 15, and is an exact reproduction of the ledger account.
As these statements are made very frequently it is unnecessary to
provide blanks with more than nine or ten lines.
32. Taking into consideration the large amount of money
borrowed in this business, and the constant fluctuation of the amount
due to banks, it will be seen that a careful, complete, and simple bills
payable record is a prime necessity. This usual record shows date
of loan, call or time, from whom borrowed, to whose account, rate
of interest, securities—amount, when paid; securities—when released.
A more simple form of this record is shown in Fig. 16.
225
Fig. 16. A Detailed Record of Loans Payable During Each Month
226Loans made should be reported immediately to the cashier in
writing, and the data concerning them should be entered at once in
the cash book and the bills payable record. In some cases, banks
arrange with the brokerage firm for what is called a blanket loan
varying in amount—from $100,000.00 upward—according to the requirements
of the firm. In increasing a loan of this character it is
always necessary to keep upon deposit with the bank, collateral
amply sufficient to cover the highest amount required, and any part
of this collateral may be withdrawn by the substitution of other
collateral satisfactory to the bank. In such a case there should be
a blanket loan account kept in the general ledger showing, specifically,
the collateral in the hands of the bank, and by the system of debit
and credit, the record of that withdrawn and that substituted should
be kept.
In case there is sufficient fluctuation in values to warrant, a
bank can demand additional security at any time or the withdrawal
of that held by them and the substitution of something more acceptable,
or they may, upon call loans, demand a part or full payment at
any time, in which case it is necessary for the broker to make arrangements
to take up the loan at once.
33. All orders received are copied from the order blank into
the journal, as the order blank used is not of a character to allow its
being numbered and filed consecutively, nor can it be readily adapted
to the division of the buying and selling accounts.
The journal sheet should have debit and credit columns for
each ledger used for customers, and a general ledger column as shown
in Fig. 17. Entries from the orders are carried into the proper ledger
column. If a man buys stock, he is debited in the stock ledger column;
if he buys grain he is debited in the grain ledger column; and
if he sells either, he is credited in the proper column.
In making a statement to the customer of purchase and sale,
the profit or loss together with the commission charged is shown.
227
34. Most brokers
have accounts
with several
banks; it is
therefore necessary
that a check
register be kept
with each bank,
showing the
date, number, to
whom issued,
amount of each
check drawn, the
deposits, and the
daily balance, as
in Fig. 18.
Fig. 17. General Journal in Which All Orders are Entered
By using this
register the account
with each
bank may be
kept separately,
and the necessity
for filling out
stubs in a check
book entirely
avoided. Many
houses have
given up the use
of check books
altogether, having
their checks
padded in numerical
sequence
and as the numbers
follow consecutively
on the
228check register, each numbered check must be accounted for. In
case a check is spoiled, the line should be voided in red ink, and the
spoiled check filed with returned checks.
In case the office cash carries an account for itself from which
checks are made, a separate check register should be kept for this
account, as its balance does not enter into the general cash balance
of the firm.
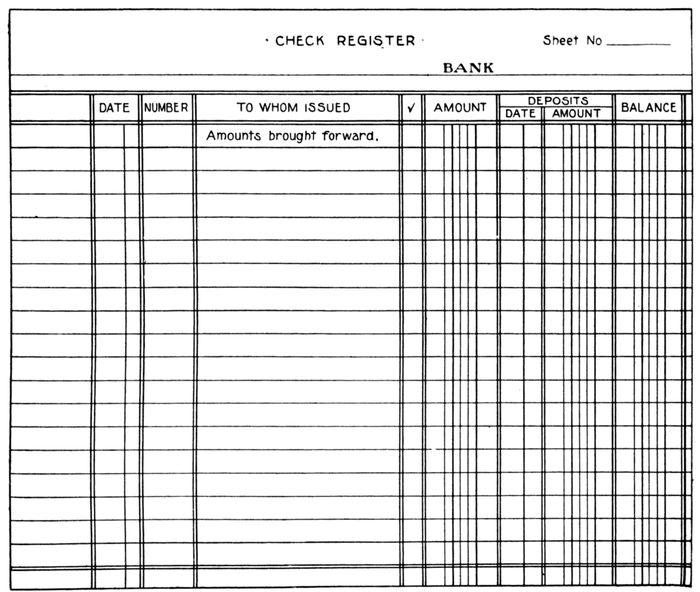
Fig. 18. Check Register Showing Condition of Bank Account
In no just sense can a broker be held to be the owner of shares
of stock which he purchases and carries for a customer, and it is a
breach of trust to use this collateral to his own advantage. The
certificate of shares of stock is not considered, according to the decision
of the Supreme Court of the United States, property itself; it is
but the evidence of the property in the shares.
To sum up, the accounting work in connection with the brokerage
business is in taking care of the orders received from customers,
being sure that they are correctly interpreted and promptly filled,
229noting the loans necessary to complete the contract, keeping a careful
record of commissions and interest due the house, being watchful
in regard to the margins of customers, and arranging all accounts
with customers so that they may be kept up to date and instantly
available.
BEAR: One who believes the conditions are ripe for a decline in prices, or
one who desires such an event. One may believe that the price of a
certain security is about to decline and therefore is said to be a bear
on that particular security, whereas he may not be so on others. The
natural attitude of a bear is that of a seller but he may be so for the
sake of buying at a lower price later.
BEARING THE MARKET: An artificial lowering or forcing down of prices.
BID PRICE: The price offered or bid for any security or commodity.
BORROWING STOCK: A broker borrows stock when he has made a contract
to deliver and the stock which he has sold, for any one of various
reasons cannot be delivered at the time agreed.
BREAK IN THE MARKET: A sudden and considerable decline in price.
BROKEN LOT: Same as odd lot in reference to stocks and less than ten
thousand dollars par value in bonds.
BUCKET SHOPS: Offices run by irresponsible brokers not members of any
stock exchange and who do a marginal business upon one dollar per
share and upwards. As a matter of fact the stock itself is neither
purchased nor sold for the customer by these operators. If the order
is actually executed upon a bonâ fide exchange then the bucket shop
puts in a contrary order for a like amount. For example: This kind of
a dealer would sell an amount equivalent to a customer's purchase or
purchase an amount equivalent to a customer's sale, thus, in no event
carrying stocks.
BULL: One who believes that conditions are ripe for an advance in prices
or one who desires such an advance and talks bullish in consequence.
One writer defines a bull as a man who has something to sell, consequently
he is anxiously waiting for prices to go up that he may sell at
a good price.
BUY AT MARKET: An order to buy at the lowest prices at which the
security can be obtained without any price limit being set by the one
giving the order.
BUYER'S OPTION: A contract under the terms of which the buyer of a
security need not receive delivery until the end of a specified time, but
he has the right to demand delivery at any time within the period covered
by the contract by giving the seller one day's notice. The understanding
is briefly expressed as "buyer 4," "buyer 10," the figures indicating the
number of days provided for in the agreement.
230BUYING ORDER: An order given to a broker to buy a certain security
with or without limit as to price as the case may be. An order to buy
is good for the date for which it was given only, unless otherwise specified.
Sometimes an order is given "until countermanded" or "until cancelled"
by which the broker understands that there is no definite limit as to time;
but brokers usually remind their customers regarding orders to be sure
that they still desire them to be kept in force.
CABLES: Telegrams from foreign countries on the conditions of the market.
Large brokers receive cables each morning from London, Paris, and other
points giving closing prices of grain and provision in that market.
CALL: A privilege which one party buys of another to call (receive) from
him a certain amount of stocks, grain, etc., at a certain price and date.
CARRYING CHARGES: The interest charged by brokers for the amount
of money advanced by them to customers in marginal transactions;
also used by a Chicago firm to indicate storage rates, interest, and
insurance on grain or provisions.
CASH GRAIN: Grain for delivery at once. Spot grain has the same meaning.
COMMISSIONS: The charge made by any broker for buying or selling
securities for someone else.
CURB: Securities which are not traded in upon the large stock exchanges
or new securities which have not yet been listed upon such exchanges
are handled in what is known as the curb market. The reason for the
existence of "curb market" in the open rather than in some building is
that if the latter plan were pursued there would, in truth, exist another
exchange, and it would not be permissible for a member of the regular
exchange of the same city to be represented thereon as he frequently
now is upon the curb.
CURBSTONE BROKER: One who usually, not being a member of the
stock exchange, goes from office to office or transacts his business on the
curb.
DELIVERY: The actual turning over to the buyer of the thing bought. If
delivery is offered after hours, the buyer may refuse it until the following
business day, but the seller has no right to demand interest for extended
time.
DIVIDEND: A portion of the profit of a corporation authorized by the board
of directors to be paid to the stockholders.
DUMP: An amount of stock that is forced upon the market for the purpose
of getting rid of it. It does not mean so much the disposing of an undesirable
investment but in offering any investment in large amounts.
EVEN: A broker is even on stock when he has contracted to receive and
deliver equal amounts of the same stock with another broker. A settlement
of the difference in prices is the only thing called for.
FLURRY: A small panic. An excitement caused by a rapidly falling market
and advancing money rates.
231FUTURES: Buying or selling grain for future delivery. Literally speaking
when you buy grain in February which is known as May grain you contract
for delivery in May at prices then existing.
IN SIGHT: The amount of grain, coffee, cotton, tobacco, or any commodity
available for immediate use.
LIMIT: A price which a broker must not exceed in executing an order for
his customers. It may also be a restriction of the amount to be purchased
or sold.
LISTED SECURITIES: Securities before they can be listed upon any board
of trade or stock exchange must have complied with certain rules of the
exchange. This does not imply that listed stock has any greater intrinsic
merit than unlisted stock but it merely shows that certain facts and
figures in relation to the security have been given more or less publicity.
LONG: One who holds stock or grain for a rise in price, or, one who has a
contract under which he can demand such stock or grain on or before
a certain day. The opposite of short.
MARGIN: An amount of money deposited with the broker to insure him
against loss; a part of the purchase or selling price.
O: The "Ticker" abbreviation for offered when accompanied by figures; for
instance, "G. N. O. 76" would mean that Great Northern Common
Stock was offered at $76.00 per share.
OPEN MARKET: A market where any or all may buy or sell.
OPEN ORDER: An order which is good until cancelled.
OPTION: An agreement of purchase or sale, good only for a certain time.
PIT: The portion of the board of trade where floor trades are made. This
term is particularly applied to Chicago. Other stock exchanges set
aside certain places signified by posts set in the floor for trading and
in these exchanges the trading points are called posts instead of pits.
POOL: A combination of buyers who work together and invest their joint
capital as one. (The different boards of trade have enacted strict rules
against pooling.)
PUT: A privilege which one party buys of another to put (deliver) to him
a certain amount of stock, grain, etc., at a certain price and date.
PUT AND CALL: A put and a call may be combined in one instrument,
the holder of which may either buy or sell as he chooses at a fixed price
and date.
REMARGIN: To give more margin.
RING: A combination of brokers to offset and settle trades with each other;
also an exclusive combination of persons for a selfish purpose as, to
control the market. (Rings have the same standing in the board of
trade as pooling, if of the same character.)
SELL AT MARKET: An order to one's broker giving authority to sell stock
or grain at market price.
SELL AT OPENING: An order to sell immediately after the opening of
the stock exchange at the best price obtainable.
232SELLING ORDER: An order given to a broker to sell a certain security
with or without limit as to price, as the case may be. A selling order is
good for the day for which it is given only unless otherwise specified.
SETTLEMENT: The payment of differences in trades between brokers.
SHORT: One who has sold for future delivery what he does not own, but
hopes to buy at a lower rate.
SKYROCKETING: Pushing the prices of securities up to unnatural levels
or forcing the price up with startling rapidity.
SLUMP: A sudden and a considerable fall in prices.
SPREAD: A "put and call" at differing prices.
STOP LOSS ORDER: This is a method of limiting losses by giving a stop
order to the broker to sell if stock declines below a certain point. These
are sometimes called stock orders.
STRADDLE: A "put and a call."
SWEETEN: To give more collateral or margin.
TICKER: A small printing machine operated by telegraph by which the
outside world obtains the reliable information as to the prices of securities
and commodities dealt in upon the principal exchanges of the world.
It is a never failing source of information to the broker. The results
are printed on a strip of paper like a ribbon which automatically unwinds
and after passing under the printing device runs into a basket. The
ribbon is called the tape. All fluctuations in prices are thus wired to the
principal exchanges immediately.
WASH SALE: An illegitimate or fictitious transaction.
THE WHOLESALE HOUSE OF MARSHALL FIELD & CO., CHICAGO, ILL.
BILLING AND ORDER RECORDING [5] — MACHINES FOR MANIFOLDING — LOOSE-LEAF SALES SHEETS AND INVOICES — ORDER WORK OF WHOLESALE GROCERS — STATIONERY — HOW TO HANDLE ORDERS AND BILLS ON BILLING MACHINES — COLORED SHEETS — COMPOUND FORMS — RETAIL DRY GOODS BILLING — DEVICES OF THE FUTURE
235
Introduction. The survival of the fittest applies most forcefully
to business men and their methods. The success of the men
depends upon their methods; the efficiency of the methods, upon the
men. Large corporations of to-day would be impossible without
method. They plan their work, and method tells them daily
whether they are working their plan successfully or unsuccessfully.
It is commonly supposed by the smaller business men that
method is a result of business growth. Sometimes it is. If a business
grows fast, better methods become a necessity. Without method
any business must remain small—with few exceptions, just as small
as the capacity of the man at the helm. "To the extent which
system is intelligently used, it multiplies one's powers of achievement
in all directions."
The importance of the order billing and shipping departments,
the amount of waste effort therein, and the relation of each to all
other branches of the business, make them a most interesting and
profitable study for the progressive business student, whether he be
a beginner, an executive, or an owner. To attain quick results
and to eliminate useless head, hand, and leg work, learn the
capacity, capability, and usefulness of office machinery and the
short-cut methods made possible thereby.
During the last eight years there has been a tremendous amount
of improvement made both in this country and abroad in handling
office work, changing from hand to machine methods. Most of
these improvements have been literally forced upon the business
men of the country by specialty companies having labor-saving
devices for sale. Wide-awake merchants have in some cases left
the installation of such devices to office people who feared the loss
of their positions through the use of them.
236One of the pioneers in the development of the class of work
above mentioned is Hiram J. Halle, who overcame all obstacles,
and gave the impetus to modern billing methods which has been such
a help to our economic results in office practice. The typewriter
companies have followed his lead and equipped cylinder machines
with the necessary attachments for accomplishing almost any desired
result, except writing in a bound book. In order to overcome this
obstacle, the McMillan and the Empire and some other loose-leaf
books have been invented. These books are loose-leaf only while
they are being written upon; after completion they are permanently
bound by a simple device, and become as secure as a sewed book.
In any book of this character, the student must consider the
text as a series of problems, with explanations of how each has been
solved. If the student does not learn to exercise his own powers of
originality as a result of a study of this volume, he will fail to secure
the result intended. Rarely, if ever, will two problems be met in
two commercial establishments which will be alike. The judgment
of the person installing the system will determine the best
method to be used under certain conditions.
Before starting in on the regular work, it will not be out of place
to give a comparison of the methods of business in various foreign
countries.
The rush in the business life of the United States is accounted
for by our fast growth and national desire to accumulate wealth.
Commercial concerns have grown both fast and slowly to undreamed
proportions. Strenuous efforts have been made to secure business,
and then a corresponding effort has been made to effect the small
economies which in a large business aggregate large sums. As a
nation, we are rushing at headlong speed, seeking all the means which
will give us results. In transportation we advance from steam to
electricity; in social life we turn from horses and carriages to automobiles;
in commercial life we use every known device to short-cut
the work and effect economies—adding machines, typewriters, cash
registers, envelope openers, envelope sealers, multigraphs, etc.
A distinct surprise awaits the person visiting Europe on a mission
of introducing "short-cut" methods. While we are in business to
make all the money we can, most of the Europeans are in business
to make a living, or reasonable earnings.
237Imagine the surprise of the writer when told by the managing
director of one of the largest department stores in London that they
did not care to save the services of thirty-five clerks (which was
possible by modern methods) as they were making a certain amount
of money each year, and did not care to make any more; besides,
they did not wish to put these people out of positions. It is not an
easy matter to secure positions in England. Employes are very
diligent and pay strict attention to business. A manager of one of
the large banks in London said that once a clerk is hired he is discharged
for gross misconduct only—not even for incompetency.
There are young men clerks (pronounced clarks) in the Bank of
England who are doing the same work for the bank as done by their
grandfathers. There are old men in the Bank of England to-day
who still use quill pens and the sand box instead of a blotter. There
are, however, adding machines being used there by the younger
generation, and they are of more use to them than to us in a way, as
their currency is so much more difficult to add.
Each year, more improved methods are being introduced into
England. Typewriters have been used for a number of years, and
of late years adding machines have made headway. It is more
difficult there to introduce new methods, but, once installed, it is
difficult to dislodge them for other ones.
Some of the wholesale houses have very old methods. In one
house in London, an order was copied twenty-nine times from the
time it was received until it was finally charged. The concern was
over two hundred years old and had never made any effort to improve
its methods. It had four boys whose duty it was to hunt orders lost
about the warerooms. A system of manifolding was installed, which
eliminated so much waste of time in copying and recopying orders
that it was difficult to convince the firm that something had not been
overlooked. After four weeks they were delighted.
An American going abroad is much impressed by the deliberation
of Europeans and is inclined to criticise them for it. After a
time, they can point out enough Americans who have worn out at
forty years of age, and are in Europe seeking health, to convince
them that perhaps the Europeans are not wholly wrong.
In Germany, the railroads are controlled by the government.
When one attempts to introduce short-cut methods, he is confronted
238by the fact that work is needed to keep busy old soldiers for whom
the government has to care. In asking an agent of an American
firm dealing in labor-saving devices why he did not use any of the
devices, the answer was given that in Germany the young men work
three years for nothing; he did not feel the necessity of doing away
with any of them. At the end of three years' work in an office, a
young man receives a diploma for efficiency, if he has attained it.
The government exercises a strict supervision over all commercial
concerns, and inspects their books at periodic intervals. Commercial
failures are therefore more rare there than at home. Fraudulent
schemes are dealt with severely.
There are many large firms in Germany, both jobbers and
manufacturers, that are striving to be progressive. The Siemens-Halske
Electric Co. are just as progressive in their order and billing
methods as any American firm in the same line. To show the attention
to details given by the Germans—a managing director of one
of the large department stores in Berlin, when asked how long he
had lived in the United States, said he had never been there. Upon
being complimented upon his American accent, he replied that when
talking to an American he always used the American accent, slang,
intonation, etc., and when talking to an Englishman he changed
his accent, etc., to correspond. He had all the American devices
in his accounting department which one would find in any department
store in the United States, and sent out monthly typewritten
bills the same as John Wanamaker, Altman, and others of New York,
and the same as all large department stores do in all American cities.
In France, the commercial houses are very conservative and
are subject to the same government supervision as practiced in Germany.
In one of the railroad companies, the Chemin de fer du Nord,
they use the manibill system of billing (whereby each shipment is
billed separately and manifolded on a form of seven sheets) which
is the shortest form of billing known, but which has never been
adopted by American railroads on account of the bulk of papers
increasing too rapidly. The present American method is to put several
shipments on a way bill for shipments to any given town, and when
the goods arrive at the given town, the receiving stations make out
separate freight bills for each shipment, copying the information
from the blanket way bill made out at the forwarding station. Some
239of the American railroads are now adopting the special roll machine
for car accountants' work, as shown in Fig. 1.
Fig. 1. Underwood Special Roll Machine for Car Accountants' Work
The French people do not, as a rule, form large companies like
the Americans and Germans and English. There are a large number
of small manufacturers and jobbers in France. The large department
stores, like the Louvre, in Paris, are run on a strictly cash
basis.
Neither the billing machines (book-writing machines) nor typewriters
were originally intended for heavy manifolding work. The
flat-bed billing machines were originally invented to write in books
used for court records, sales books, etc. The book was to remain
240stationary and the machine was to travel over the books. The
flat-bed machines are the only machines made for writing in bound
books—the latter are being gradually replaced by loose-leaf books.
A flat-bed machine for bound books is shown in Fig. 2.
Fig. 2. Flat-Bed Typewriter for Bound Books. Elliott-Fisher Co.
The typewriter was originally intended to write on one sheet of
paper only. If extra copies were needed, a copying ribbon was used,
and a wet copy taken in a letter-press book. In the evolution from
bound books (official record and commercial) to loose sheets, the
book typewriter was equipped with devices for holding loose sheets
of paper—used alone or in connection with books. In the evolution
from letter-press copies to carbon copies, the typewriter was equipped
with hard-rubber and brass platens for taking from one to twenty-five
copies, and in some cases even more, with extremely thin paper
and carbon paper.
241The flat-bed billing machines are equipped with heavier type-bar
springs than the cylinder machines. The operator in depressing
the keys overcomes the additional resistance to the touch, due to the
heavier type-bar springs, and strikes a heavy blow on the paper,
making a good manifold copy in all cases. The operator on a cylinder
billing machine strikes a heavier blow than usual to secure the heavy
manifolding results. The heavier the blow, the clearer the result
on a billing machine. The Underwood billing machine is shown
in Fig. 3.
Fig. 3. Underwood Billing Machine
All typewriters equipped with special attachments for holding
the sales sheets, invoices, and orders are called cylinder billing machines.
The paper upon which the machine writes is held by, and
passes over and around, a round rubber roll, the cylinder.
This is in contrast to the flat-bed billing machines (or book
242typewriters) on which the paper lies flat on a rubber plate while the
machine moves over the paper.
Development of Billing Machines. This text has been prepared
by taking the simplest forms of billing and order work, and leading up
gradually to the more complicated forms. This is actually what took
place in the improvement of office and factory work.
A bill and a copy were first made—an extra sheet was made
for some additional purpose. The advantages of doing two or three
things at once led to further investigation. This resulted in still
additional sheets being used for other purposes. Every time an
additional sheet was added, the labor of typewriting that sheet
separately was eliminated.
Gradually it developed that it would be useful to copy a part
only of the typewritten information on some of the under sheets.
Means were found for accomplishing this. For instance, on an
order form, it was desirable to have the prices show on the office
copy, but not on the copy which was intended for the warehouse
or factory.
In some cases it was desirable to write all the information on
the top copies and split up the information thereon on the sheets
underneath. The final development of all the above ideas is embodied
in the compound form, in which all sheets for the office, customer,
warehouse, factory, shipping room, and loading platform are
typewritten at one operation, and the invoice and duplicate finished
as a separate operation.
Wholesale and manufacturing lines are used mostly in this
text to illustrate the evolution and improvement of billing and order
work. Some of the conditions which have to be considered in installing
office systems are as follows:
Whether the orders are received from customers or salesmen or both, and which are in the majority.
Whether the goods are carried in stock or manufactured or bought outside, or all of these.
Whether the orders can be filled completely, or nearly so.
Whether or not the factory may know the prices.
Whether the goods are shipped by freight, mail, express, or all of these.
243Whether copies of the bills have to be made for any other purpose.
Whether a copy of the sales sheet has to be sent to the home office, or made for any department.
If additional copies of either are necessary, what colors to use for readily distinguishing them.
How many ledger clerks, and how to sort their work to the best advantage so that each clerk handles his work only.
How to file office and factory copies for quick reference.
How to plan all the above so that improper filing of sheets does not destroy the chain of record.
The reasons for these considerations will be better appreciated
after further progress is made.
If the business student learns the capabilities of office machinery,
the advantage of manifolding, the use of colored papers, and the
important feature of correctly grouping statistics (which is almost
an art in itself), he will have accomplished much. He should learn
also to develop his own power of originality and suggestion.
The natural order in which order billing and shipping ought to
be presented is the way in which the transactions occur. Methods
of billing (making out invoices) in many businesses govern the manner
in which the orders are made up, and therefore will be considered
first.
In order to more clearly bring out the advantages of new
methods, it is deemed advisable to consider old-style methods and
contrast them with the newer ideas. By showing the weak points in
the older methods and why the new are better, the gradual evolution
and improvements can be traced.
Old-Style Method of Billing and Making Wet Copy in Tissue
Book. There are enough firms who still follow this plan of billing
to resent the term "old-style." The best that can be said for this
plan is that it is shorter than writing the bill-and-sales book, or sales
journal, separately. The wet copy takes the place of rewriting
the bill. One objection to this method of copying bills is that
if all the bills are copied some of them are either blurred or are too
light when the copy has dried on the tissue leaf. This is a difficulty
which can be corrected by careful attention.
The worst feature is that one never knows whether all the
244bills have been copied, and there is no way of knowing this unless
the copies in the tissue book are checked back with the orders from
which the bills were made. Many firms spend thousands of dollars
in advertising, traveling expense, labor, etc., ship out and bill large
invoices of goods, "double check"
the invoices, and leave the copying
of the invoices in tissue books
to a young office boy. They never
think to check back the invoices
with the orders to be absolutely
certain that the goods have been
charged as well as invoiced
(billed out).
Fig. 4. Old-Style Cloth Bath. Underwood Typewriter Co.
If one should ask them how
they know that all invoices are
charged (or copied into the tissue books) the invariable answer would
be, "Oh! we never lose any bills before they are copied." Ask them
how they know none are lost and, after thinking a while, they will
admit that they really do not
know for sure. They begin to
check back the tissue book after
some customer brings in a bill
for payment which has never
been copied into the tissue book,
and hence has not been posted
to the customer's account.
Fig. 5. Old-Style Copy Press. Underwood Typewriter Co.
Fig. 4 shows the old-style
cloth bath, Fig. 5 the old-style
copy press, and Fig. 6 the old-style
sales book (tissue paper leaves).
This style of billing was the
first variation from the plan of
using copying ink, or pencil, on invoices and then transferring the
ink to tissue paper books, by wetting the leaves with water and then
absorbing the surplus water with paper blotters. Or this was
done by placing damp cloths on the under side of the leaf and covering
245it with a leaf, placing the invoice downward on the tissue leaf,
closing the book, and placing it in a copying press. The ink from the
invoice was sufficiently transferred to the tissue paper to make an
impression thereon.
Fig. 6. Old-Style Sales Book. Underwood Typewriter Co.
If the person who did the copying did not use due care, the paper
would be too wet and the ink would run and blur the copy and the
invoice. If two invoices were accidently picked up by the person
copying, the top invoice would not be copied on the tissue sheet.
This is a most serious objection, for the reason that the copy in the
tissue was used as record of the invoice for the purpose of posting into
the ledger.
Another difficulty was the usual one experienced through the
use of bound books in office work. Only one person can use a book
at one time. If Fayette Henry, the accountant, was using the
tissue-copy book, and Dave Pike, the order clerk, wanted to use it
to see if all invoices had been copied by the office boy, he had to wait
on Fayette Henry. The loose-leaf sales sheet shown in Fig. 7, with
the pages serially numbered and placed in proper binders after
each sheet has been filed, overcomes all of the difficulties mentioned—with
many additional benefits.
246
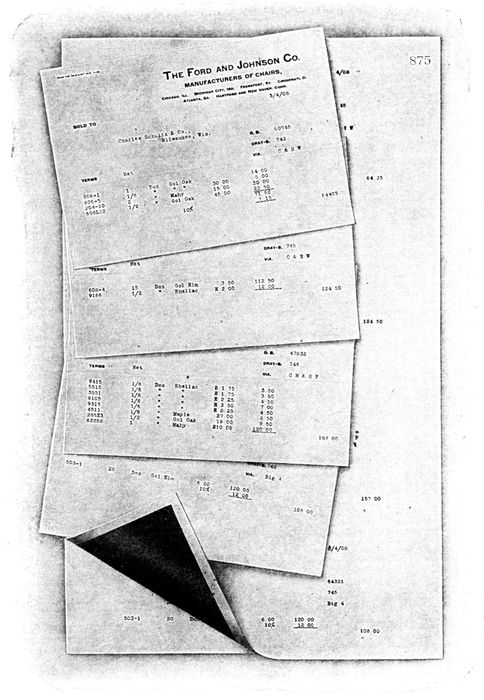
Fig. 7. Loose-Leaf Sales Sheet and Invoices. No Ruling on Sales Sheet. Remington Typewriter Co.
247The loose-leaf sales sheet and invoice were first used with the
flat-bed billing machine, the sales sheet being held in position by
being placed over studs (round metal posts), which fitted into the
punched holes in the edge of the paper. These punched holes were
used ultimately for fitting over the metal binder posts in the loose-leaf
binders. The invoices were wider than the regular-size invoice
and were perforated about 1 inch or 1½ inches from the left side,
as shown in Fig. 8. To the left of the perforated edge were two
small holes about 2¾ inches apart, which fitted over two small studs
on a sliding bill-holder device. This plan provided a means of holding
the large sheet and invoice in proper relation to each other. A
piece of carbon paper the same size as the sales sheet was placed
between the invoice and the sales sheet. This ruling of the sales
sheet is shown in Fig. 9.
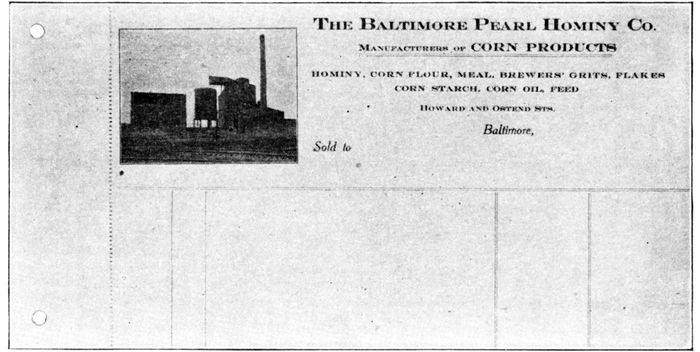
Fig. 8. Invoice for Use on Billing Machine
When an invoice was written on the billing machine, it was
manifolded on the sales sheet beneath. When the invoice was
finished it was ready to mail—no delay in copying invoices, no blurred
invoices through careless copying. No fading of the manifolded
copy where black carbon paper was used. Inks are not made of
indestructible carbons as black carbon paper is made. A condensed
billing or invoicing loose-leaf sales book for this purpose
is shown in Fig. 10.
The following are some of the many good features of the condensed
system, as it is in use to-day, briefly stated:
248
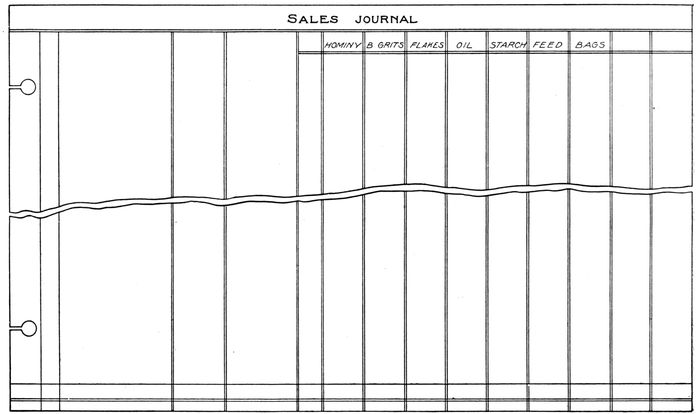
Fig. 9. Loose-Leaf Sales Sheet
249Bill and entry in sales book are obtained at one operation.
Entries upon sales book agree absolutely with bill rendered.
The bill clerk becomes bill and entry clerk combined.
There is no danger of a bill being rendered without the proper
charge being made.
Entries under this system occupy but one-fourth the space required
for those written with the pen.
There is no waste space upon sales sheet.
Both sides of the sales sheet may be utilized.
The saving in vault space alone is worthy of special consideration.
Fig. 10. Condensed Billing or Invoicing Loose-Leaf Sales Book.
Underwood Typewriter Co.
In recent years, the typewriter companies have placed devices
on their typewriters which permit of the sales sheet being held independently
of the invoices. This permits one to hold the large sales
sheet in the machine until enough invoices have been manifolded
thereon to cover the page, at which time the sales sheet is reversed.
The invoices can be placed in the machine and removed therefrom
after being written, without interfering with the sales sheet. No
250extra width of invoice is required, which permits of old stationery
being used in the form of invoices. The flat-bed machines can use
old stationery, but not quite so well. However, when billing by
machinery, it is false economy to use stationery designed for pen
work. The reasons for this will be touched upon later.
The use of two ledgers necessitates the use of two columns at
the right side of the page. All names from A to L are placed in the
first column; all names from M to Z are placed in the second. For
instance, an invoice reading as shown in the sales journal, Fig. 11,
illustrates the idea of writing the totals in the two columns at the
right side of sheet according to the initials of the last name of the
firm or the individual, as the respective ledgers are arranged in that
manner. If at the end of the month the first column shows a total
of $3,000.00 the bookkeeper knows that he has posted that amount
into Ledger A-L, etc.
The above plan enables the bookkeeper to add separately the
totals which are posted to the respective ledgers. The desire to
separate the charges to a country ledger and a city ledger can be
accomplished by using two columns in the same way.
The desire to place all credit memoranda in the sales book can
be accomplished by using two columns in the sales book as noted
above. The first column is used for the charges, and the second one
for entering the credits. One difficulty arises in connection with
this plan. Credits are liable to be entered in the debit column.
To obviate this, the invoices are made just wide enough to reach over
the first column, the credit memoranda are made wider to reach over
the last column. When an amount is written in the last column of the
invoice, it manifolds in the proper column of the sales sheet. The
same is true of an amount written in the last column of a credit memo.
This subdivision of columns is carried a step further to permit
of the analyzation of sales in several ways.
According to classes of goods, as follows:
LAMSON FOUR-INCH PNEUMATIC TUBE ORDER CARRYING SYSTEM FOR A LARGE WHOLESALE ESTABLISHMENT OR A FACTORY
Lamson Consolidated Store Service Co.
251
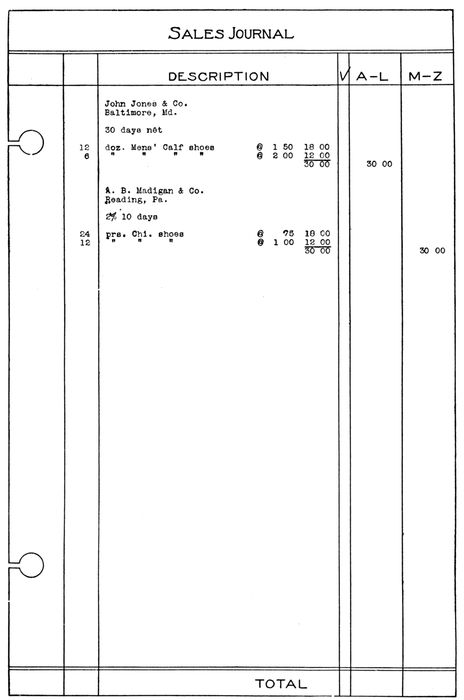
Fig. 11. Sales Journal Arranged for Distribution to Two Ledgers
252According to territory, as follows:
According to salesmen, as follows:
To separate the sale of regular goods from goods which are being
sold on consignment, as follows:
Generally the invoice is wide enough to reach over the total
column only, as shown in Fig. 12. Therefore, a total amount written
in the total column of the invoice will manifold onto the sales sheet,
and in the column marked Total.
A wide-carriage billing machine, if used, can be adjusted with
tabulator stops to jump to any column desired. The total amount
is then written therein a second time. The amount of the total
column should always equal the total of all the columns placed to the
right of the total column. This plan eliminates the old way of waiting
until the end of the month, and then laboriously going over the
253sales book with one total column only, and picking out the various
items according to the classification wanted.
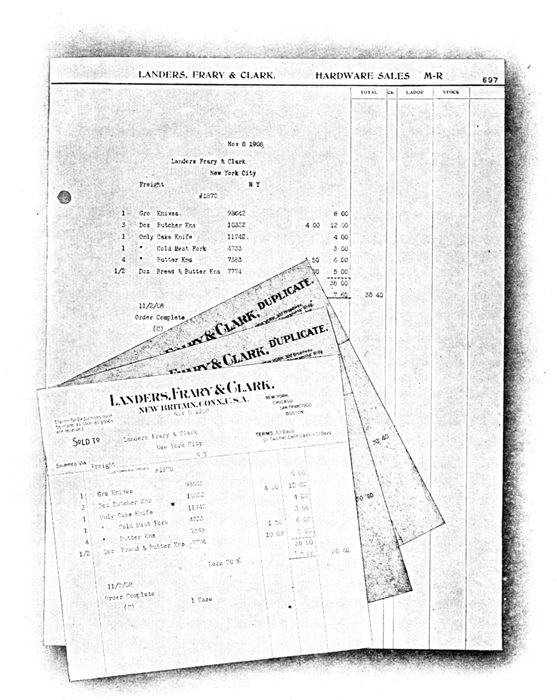
Fig. 12. Loose-Leaf Sales Sheet and Invoices with Columns for Distribution of Labor and Stock
The work should be planned in a manner which permits of
each day's work being finished each day—leaving nothing to accumulate
until the end of the month, necessitating the retracing of steps
to secure certain statistical information.
In certain lines of business it is desirable to make two sales sheets,
254one of which is retained in a binder for an office record and the other
is used for various purposes. It can be used as record of sales from
a branch to a home office, each page being numbered in duplicate,
and of a distinctive color. This is the plan used all over the world by
the Standard Oil Company. As the sales sheets arrive at the home
office, they are placed in their respective binders and are gradually
made into a built-up book. The loss of a sheet would be instantly
detected by the missing page number.
A large French perfumery firm in New York pursues this plan,
and sends to Paris the duplicate sales sheet on thin paper. It gives
the home office a fine record of every invoice sent out to any customer
by the branch office or warehouse. As several invoices can be manifolded
on each page, and on both sides of the sheet, it is the most
economical method of billing as far as stationery is involved. The
name condensed billing indicates this fact.
In other instances, the duplicate sales sheet is wide enough
only to allow quantity and description of goods to be manifolded
thereon, prices and extensions not showing. This narrow sheet can
be used for posting to the stock records without disclosing to that
department the prices at which the particular goods have been sold.
This form of the sales sheet is shown in Fig 13.
Duplicate Invoices. There are many reasons, in various lines,
why duplicate invoices are desirable and even necessary. Some
customers request invoices rendered in duplicate with one copy
complete, the other minus the prices and extensions. To accomplish
this, it is either necessary to place a piece of paper between the
carbon and duplicate invoice in such a manner that the prices and
extensions will not copy, or to use a short invoice cut off at the left of
the price column, or to use a short piece of carbon paper between
the original and second, or duplicate, invoice.
It is desirable to make extra copies of invoices or duplicates for
the use of various departments of a business, for instance, analysis
of sales by salesmen. Where a company employs a large number
of salesmen, it is very convenient to file in binders a duplicate copy of
all invoices sold by each salesman, using a binder for each salesman.
This is preferable to having separate columns in the sales book (sales
sheets in binders). The latter method permits each salesman to see
what every other salesman is doing.
255
Fig. 13. Sales Sheet for Condensed Billing
256Department Records. A separate binder allows each man to
consult his record without inconvenience to any other one. In large
companies having a traffic department, it is necessary to provide a
duplicate copy of each invoice for the record, showing complete
details of every charge.
A distinction should be made between those firms who make
their invoices before the goods are shipped, and those who make the
invoices after the goods have been shipped. In the cloak business,
for instance, the goods are generally billed before the goods are
shipped, the invoice being placed in an envelope and packed with
the goods.
Ofttimes the goods are manufactured in proper quantities,
properly checked from the order to the packers' table, and then
packed improperly—some customer receiving too many garments, another,
too few. Yet the order will be properly checked. To obviate
this difficulty, a scheme was devised whereby the packer received a
duplicate typewritten copy of the bill (or invoice) showing everything
but the quantities. This makes it necessary for the packer to
count all the garments and mark down in pencil on this copy of the
bill the quantity of each style and kind to be shipped. Before the
goods are shipped, the packer's copy of the invoice, with his quantities
marked in lead pencil, is compared with the quantities charged on
the sales sheet. This scheme forces the packer to count all garments
instead of double checking someone else's figures in an absent-minded,
or even neglectful, way.
This is accomplished by placing a narrow strip of paper over
the quantity column of the duplicate invoice, but under the carbon
paper. The quantity figures manifold onto the strip of paper instead
of onto the duplicate invoice. This plan is termed using a blind.
The narrow strip of paper between the invoice and duplicate is the
blind described a little further on.
The next step in short cutting work is the printing of a label
in connection with the invoice and sales sheet. In the book business,
where it is generally possible to fill orders from stock, and where the
invoice can be made before the goods are shipped, it is possible to place
a small piece of paper (the label) between a folded invoice in such a
manner that when the name is written on the invoice it manifolds
onto the label as well as onto the duplicate invoice and sales sheet.
257Analysis of Quantities and Amounts. In certain lines of business
which sell three or four varieties of goods, it is desirable to analyze
the weights or quantities in the proper columns, which in turn manifold
onto the sales sheets, as shown in Fig. 14.
Fig. 14. Sales Sheet for Analyzing Quantities and Amounts of Goods
This saves a great deal of time as compared with making out
the same invoice in the following way:
| 3000 # Brass Rods |
@20 $60.00 |
| 2500 # Brass Bars |
@21 $52.50 |
| 1000 # Zinc Bars |
@15 $15.00 |
By following the first plan, all of the weights for the respective
classes of goods will be manifolded into the proper columns, and it is
therefore an easy matter to total each column, and at the end of the
month the classification of sales will be totaled according to weights
as well as according to dollars and cents. The invoice is ruled to
match the sales sheet.
Information on Sales Sheet Not on Invoice. In certain lines of
business, such as wire-screen manufacture, it is desirable at times
to substitute the next size of wire in order to fill orders promptly.
In such cases, it is necessary to have the invoice show the size of wire
ordered, but to have the sales sheet show the size really sent. It
would seem impossible therefore to write No. 8 wire on the invoice
and have No. 9 wire manifold on the sales sheet.
258The idea used to accomplish the desired result is to place the
invoice in such a position with relation to the sales sheet that a margin
is left on the left-hand side of the sales sheet, which would permit
the operator typewriting directly on the sales sheet, and placing
thereon the actual size of the wire shipped. The size ordered would
be written on the invoice in the regular manner, and of course would
manifold onto the sales sheet.
There are other cases where it is desirable to use this idea.
For instance, wholesale dry goods firms when purchasing dry goods
from eastern manufacturers request the latter when billing to use
lot numbers furnished by the purchaser. It is also necessary for
the manufacturers to bill the goods according to their own lot numbers.
Hence it becomes necessary to have both the customer's lot
number and their own on the sales sheet. This is accomplished
by writing their own lot numbers directly upon the sales sheets at
the left of the invoice and then making the invoice out in the regular
way. This idea carries out the customer's wishes, and always gives
a comparison of lot numbers to the manufacturers on their sales
sheets. Flat-bed machines require wider invoice, Fig. 15.
Goods Purchased Outside. It is possible to make a short cut in
some lines of business where the goods sold are not kept in stock but
are purchased from other firms in the same city. When placing the
invoice in the billing machine over the sales sheet, requisition blanks
in duplicate or triplicate can also be placed in the machine with the
invoice, and the items which have to be ordered outside written first
on the invoice. When all of these items have been entered on the
invoice, the requisition blanks may be removed, and the invoice
and sales sheet left in the billing machine, putting the remaining
items which are to be shipped and charged on the invoice (sales
sheet). This occurs where orders can be shipped complete.
This plan can also be used when writing up the order, where the
billing is done after the goods are shipped. It is to be remembered
that there is a great distinction to be made in handling the billing
work of firms who are able to fill their own orders complete, as contrasted
with those firms who have to wait until goods are shipped
in order to determine which items to bill. Some firms who always
carry a complete stock are able to make up an invoice and order
blank, a label for the express package, and a charge on sales sheet,
simultaneously, because they know that they can ship every item
called for, and consequently do not have to wait to see what items
are shipped before billing them.
259
Fig. 15. Form to Provide on Sales Sheet Information not on Invoice
260Unit Billing. The unit idea in billing has grown considerably
in the last few years, notwithstanding that the size of the bills have
to be uniform, and as large an invoice has to be used for one item
as for a large bill. Many firms prefer the unit idea to the condensed
sales sheet idea.
This is due chiefly to the elasticity of the scheme. The duplicate,
triplicate, or quadruplicate of the invoice can be sorted in any desirable
way. It is especially convenient for bookkeepers to sort duplicates
of the invoices alphabetically, and save a great deal of time in
posting to loose-leaf ledgers arranged alphabetically, in the same
manner. (In mentioning loose-leaf ledgers, card-ledgers are always
included, as the same principles are applied to one as to the other, as
far as accounting methods are concerned.) It is easier to handle
unit billing forms on the typewriters with billing attachments, which
is an added reason that many firms prefer to use them. Some of
these forms are shown in Fig. 16.
Another idea to be recommended is the color scheme, whereby
each copy of the invoice is manifolded onto a different-colored piece
of paper. In sorting the various copies for different departments,
different colors will greatly facilitate the recognition of various sheets,
and the uses or departments for which each is intended.
There are hardly two firms who handle their order work alike.
The first consideration in treating order methods is to distinguish
the classes of business in which the orders are made up ready for execution
by the salesman, from those which are received from customers
and transcribed on typewriters. The first class will be discussed
separately from the second.
Wholesale grocers, druggists, and similar lines receive the great
majority of their orders from the salesmen in the field. After the
orders are opened, the first step is to stamp on each order a number
with an automatic numbering machine. After this is done they are
copied into an order register as follows:
261
Fig. 16. Samples of Unit Billing. Remington Typewriter Co.
| 262 |
| 1012 |
John Smith & Co., |
Plainfield, N. J. |
| 1013 |
A. B. Jones & Bro., |
Providence, R. I. |
| 1014 |
U. J. Benedict, |
Elmira, N. Y. |
| 1015 |
Grace Barnes & Co., |
Alliance, Ohio. |
After the orders are filled and charged, they are checked on the
order register. About once a week all of the unchecked numbers
on the order register are compared with the unfilled orders. If an
order should become lost, the fact would not remain unknown longer
than one week's time.
It should always be remembered that in case an order is not
completely filled and is "back ordered," the back order should
always show the original order number in order to prevent confusion.
A little practical experience will quickly show how wrong it is
to use a new number for a back order.
Back Orders. In the problem of systematizing any kind of
business, the question of back orders and the proper method of
handling them is one of the most troublesome. Some firms do not
wish an order blank returned to the warerooms after it has once
been there, because they do not wish the wareroom or factory to
know the prices which are placed on order blanks in the office after
they have been received there for pricing, extending, and billing.
Many firms therefore make an entirely new order to be returned
to the factory or wareroom with the letter A used in connection
with the order number, as follows: 1013A. This of course delays the
filling of the order until the back order is typewritten. If it is
necessary to make a second back order, the same would read 1013B.
Other firms use the color scheme. This is a very good idea, as it
indicates clearly to the order fillers old orders which should receive
attention first.
Many important improvements in the order and billing methods
have been inaugurated in recent years in the business of wholesale
grocers. Formerly it was the custom, after the order had been numbered
and recorded in the order register, to pass the orders out into
the warehouse with the general understanding that they were to
be filled as quickly as possible. The order fillers would generally
start at the top floor and pick all of the items which were to be shipped,
place them on a truck and take them to the next lower floor, and
follow this plan until the order was entirely filled. In stores above a
certain size this resulted in considerable delay.
263The first improvement was to send the orders to the shipping
department, where they were split up by clerks known as Slippers,
who wrote on slips the items which were to be taken out of stock,
each slip representing the goods to be gotten out on a certain order
from a certain floor. This idea allowed the order fillers on all
floors to work simultaneously, and resulted in considerable saving
of time.
Another favorable result obtained through this system is that
the shipping clerk retains an original copy of the order (the copy sent
in by the salesman) and is enabled therefore to follow up all departments
and hurry up any department which may be delinquent in
the filling of a certain order. In planning work, it is always advisable
to have one department act as a follow-up on some other department.
In the grocery business, it is much more satisfactory for the shipping
clerk to have a complete record of all the orders to be shipped that
day, than to hand the original orders into the warehouse to be sent
down to the shipping department after the order has been entirely
filled, and then have the shipping clerk rushed at the last minute
to plan his loads and do all of the clerical work, such as making up
bills of lading, etc.
The next improvement was necessitated by a desire on the part of
those wholesale groceries which are located in cities having an efficient
interurban electric car service to fill orders at different hours of
the day. One western firm transcribed all of its orders on
cylinder billing machines, giving the shipping clerk a full copy of
the order, and each department a copy of the items which are to be
filled from that department only. On the shipping clerk's copy, the
notation 11 A.M., is marked, also on all of the department order
slips. This indicates that the order is to be shipped on the 11 o'clock
car. Other stationery is printed with the 1 P.M., 2 P.M., 3 P.M.,
4 P.M., 5 P.M. to indicate the hours at which the orders
are to be shipped. Many small retail merchants delay ordering
until the last minute, and the wholesale house which can give the
promptest service gets the business. The above plan advises the
shipping department the time that the goods are to be delivered,
and makes it responsible for results. All delays are noted, and a
daily report made of the causes, which are promptly investigated
and removed.
264Split Orders. Some wholesale drug houses have their stock
arranged on different floors, of which their salesmen are fully advised.
If the salesman takes an order for goods which are held in
stock on four different floors, he sends in the order on four sheets
of paper with the items for each floor written on the respective
sheets which indicate the respective floors. Different-colored sheets
of paper are used for the various floors. This scheme puts more
clerical work on the salesmen, but it enables the office to quickly
hand each department its part of the order without the delay of
transcribing the department slips on the typewriter at the office.
In all order schemes where an order is split up and written on several
sheets of paper in order that each department may fill the order
without delay, the term split orders is used. In all split-order schemes,
the number of sheets in which the order has been divided is written
on each sheet. For instance, if there are departmental order sheets
for three different floors, the figure 3 is marked on each slip. In
this way the biller, by counting the number of sheets attached to the
complete order, will know that all of the split-order sheets have been
returned to the office. Fig. 17 illustrates this system of orders. The
three blank sheets at the top are departmental order sheets, and each
contains only a part of the whole order. This is accomplished by
removing one departmental sheet at a time from the billing machine,
but allowing the three top sheets to remain in the machine until the
entire order is written.
Some firms are willing to make four copies of an order, each
copy containing all of the items of an order. Other firms do not
wish the employes to know what a customer is buying outside of
the goods relating to the department in which the employe is working.
Further, sometimes two departments in the same factory are
equipped to make the same class of goods, and if each department
received a complete copy of the order there might be some confusion
and duplication in the filling of the order.
Some firms, instead of making split orders, make a summary
of the goods to be delivered from each floor, giving each floor several
of these summaries in the course of a day. The goods are delivered
to the shipping department in large quantities, and are separated
by the shipping clerk according to the quantities wanted for each
order. Concerns which are using this idea claim that it takes less
time for the shipper to separate goods than it does for the order department
to make split orders for each individual.
265
Fig. 17. Forms for Split-Order Schemes
266In planning the clerical work in order billing and shipping
methods, the volume of business being handled must be taken into
consideration. A plan which is necessary with a large business would
be considered as red tape in a smaller one. The larger a business
grows, the more it is possible to "specialize" the work.
In a very small business, one man could fill all the orders and
make out all of the bills. In a little larger business it would be
necessary to devote one person's entire time to filling orders, another's
to making out the bills. In a business twice as large as the one just
mentioned, it would be necessary for one person to devote his entire
time to filling the orders from one floor only. In an exceptionally
large business, it might be necessary for one person to devote his
entire time to filling orders for some particular class of goods on one
floor. These examples are given to illustrate the meaning of the
word specializing.
Simple Order Form. The majority of firms transcribe their
customers' orders onto their own order forms from letters or requisitions.
The simplest form of order is one containing an original
for use of the warehouse or factory, a duplicate to be mailed to the
customer as an acknowledgment of the order, and a third copy
which is held in the office as a record of unfilled orders. The requisition
form illustrated in Fig. 18 conveys the idea.
The practice of sending an exact copy of the order to the customer
eliminates the necessity of acknowledging the order by letter,
and gives the customer an opportunity of checking over the order
as entered. It is customary to print on acknowledgment of order
forms the sentence: This is an exact copy of the order as entered—if
any errors are noted kindly advise us at once. One firm in
Buffalo saved $300.00 the first week they installed this scheme,
through the detection of an error by the customer.
A YACHT STORAGE BASIN AT THE SHIPBUILDING PLANT OF THE GAS ENGINE & POWER CO. AND CHARLES L. SEABURY & CO., CONSOLIDATED.
267
Fig. 18. Simple Requisition Forms for Order Handling. Remington Typewriter Co.
268It is imperative that before a remedy or short-cut methods
can be prescribed, it is necessary to thoroughly diagnose all of the
conditions incident to the business. It should also be remembered
that clerks and even department heads will see all of the imaginary
difficulties of a new idea and overlook all of the benefits to be derived
therefrom. It should be further remembered that if a new method
shortens nine-tenths of any particular class of work and slightly increases
one-tenth, the party involved will many times fail to see the
net advantages accruing through the introduction of the new idea.
If objections are raised to a suggested short-cut method it is always
well to ascertain whether the objections apply to a majority of the
work or a portion of it only. Most people in clerical positions rather
resent new ideas, and seem to take a pleasure in trying to find some
reason why a new idea will not succeed. This is one phase of human
nature which requires the utmost tact and diplomacy to handle
successfully. In advancing or suggesting new methods, it should
be assumed as far as possible, that the idea has been suggested by
the person to whom one is talking, for the reason that most people
are willing to "father" their own ideas.
Simple Order Form with Copy for Shipping Department. The
second short cut which was instituted in connection with order forms
was the addition of a sheet on which was manifolded a copy of the
order for the shipping department.
The idea is to give the shipper information in advance, in order
that he may prepare his bills of lading and plan his work for his
teams, order cars in advance from the railroad, call up express companies,
and such other work as might be necessary to the proper
shipment and delivery of the goods manufactured and sold, and to
file the copy as his permanent record, in some cases.
Some firms desire to prevent the shipper from knowing the
prices at which their goods are sold. This is accomplished by using
for the shipping department a short sheet of paper which reaches
from the left edge of the order-blank to the price column only. Another
method is to use a narrow sheet of carbon paper with a full-size
sheet of paper. This plan is not as satisfactory as the former
one, as the carbon paper sometimes slips to the right and allows the
prices to manifold.
Acknowledgment of Order to Salesman. In some lines of business,
it is desirable to add an additional sheet which is termed acknowledgment
of order to salesman. This plan enables the salesman to
know that the order has been received and properly entered for
execution (in manufacturing lines it is necessary to transcribe orders
on order forms which contain too many copies for a salesman to
manifold by pencil), and gives him the opportunity of checking the
269order as entered. It should be remembered that in some lines of
business there is such an enormous amount of detailed information
in connection with an order that neither the customer nor a salesman
would check over an exact copy of the order as entered. This should
always be taken into consideration when considering the addition
of this sheet.
The various styles of loose-leaf sheets and binders should be
fully understood in order to appreciate their importance in order and
billing work.
Loose-Leaf Sheets. The first loose-leaf sheets were punched
with closed holes, as shown in the illustration of Kilby Mfg. Company
forms in Fig. 18. The trouble with the closed-hole punching is that,
when placed over the metal posts of the binder, it is impossible to
remove a sheet in the center of the binder without removing all of
the sheets immediately above the one desired.
To obviate this difficulty, the slotted hole was devised. This is
illustrated in the forms of the Commercial Sash & Door Company,
in Fig. 19. The slot from the edge of the paper to the punched hole
permits the paper to be placed over the posts of the binder between
any two sheets. Holes are punched in both the closed and slotted
styles in various sizes, ranging generally from a ¼ to 5/16 of an inch
in diameter. In late years, manufacturers have introduced punched
holes of different shapes from that of a circle.
For permanent records where the sheets are filed serially according
to page number, order number, etc., the closed-hole loose-leaf
sheet is perfectly satisfactory. For records which are to be removed
from any given part of the binder and reinserted in another part,
the slotted-hole loose-leaf sheet is the most satisfactory style to use.
Binders. Binders are generally made of two covers and a set
of posts, which ordinarily are attached to one of the covers. The
other cover is movable in order to accommodate the increased thickness
of the binder as loose-leaf sheets are added. Great strides have
been made in the manufacture of improved binders. There are so
many styles of posts and other ingenious arrangements, where the
two covers are held together and closed or opened by the use of a
key, that only reference to catalogs of manufacturers will supply
detailed information.
270
Fig. 19. Two Styles of Punching for Loose-Leaf Sheets. Remington Typewriter Co.
271In buying binders and loose-leaf sheets, it is well to buy both of
the same firm. Heretofore, trouble has been experienced where
the punched holes of the loose-leaf sheets were probably 1/64 inch
further apart or closer together than the metal posts in the binder
in which they were to be used. The manufacturer of the binders
will always claim that the sheets were punched incorrectly by the
printer, and vice versâ.
It is pretty generally understood now that all punched holes
should be placed with the center of the hole ½ in. from the edge of
the paper. This allows enough margin to permit of the paper being
held firmly over the posts. In all cases where the holes are punched
too near the edge of the paper, the narrow margin between the edge
of the paper and the hole becomes torn very quickly.
Stationery Printed for Typewritten Work. Very few people
recognize the great value of properly designed stationery for typewritten
work. The law of usage and custom is so strong that
invariably invoices and order forms are printed the same as if they
were to be hand-written. The headings are printed with the first
letter of each word lined up vertically. This plan causes great
waste of time on the part of an operator.
All billing and order work should be done on machines equipped
either with a column stop or a decimal tabulator. A column stop
is a device on a writing machine which automatically stops the carriage
at any one of several predetermined points. A decimal tabulator
is a device on a writing machine which automatically stops
the carriage at the units, tens, hundreds, etc. place in any predetermined
column.
It should also be understood that all typewriters and billing
machines are equipped with marginal stops. These stops are adjustable,
and can be arranged on either side of the machine in such
a manner that the carriage will always stop at any given point at
either edge of the paper.
It is vitally important that either a column stop or a decimal
tabulator should be used in connection with marginal stops on writing
machines, and these three points should be taken into consideration
when designing stationery for use with a machine. The following
illustrations show poorly designed and correct invoice
headings.
| 272 |
| J. B. WILLIAMS & BRO. |
| NASSAU, N. Y. |
| |
| NAME |
SALESMAN |
| SHIPPING ADDRESS |
ORDER NUMBER |
| P. O. ADDRESS |
REQUISITION NUMBER |
| VIA |
|
This blank form has purposely been shown in order to contrast
it with an invoice printed in the same way with the headings
properly filled in.
| J. B. WILLIAMS & BRO. |
| NASSAU, N. Y. |
| |
| NAME, Geo. Brown & Co. |
SALESMAN, Jenkins |
| SHIPPING ADDRESS, Flat Rock, W. Va. |
ORDER NUMBER 2246 |
| P. O. ADDRESS, Wenonah, W. Va. |
REQUISITION NUMBER A341 |
| VIA N. & W. R. R. Co. |
OUR ORDER NUMBER 9422 |
Contrast this heading with that of an invoice which has the last
letters of each line lined up vertically. This makes it possible for the
operator of the billing machine to draw the carriage to the extreme
right, as the first letter to be written in every line of the heading
starts at the same point.
| NAME Geo. Brown & Co. |
SALESMAN Jenkins |
| SHIPPING ADDRESS Flat Rock, W. Va. |
ORDER NUMBER 2246 |
| P. O. ADDRESS Wenonah, W. Va. |
REQUISITION NUMBER A341 |
| VIA N. & W. R. R. Co. |
OUR ORDER NUMBER 9422 |
The latter form does not have as good appearance before being
typewritten as afterwards. However the change is made for the
sake of utility and speed. In the first form it is necessary for the
operator to position the carriage at a different starting point for each
line, whereas in the last illustration it can be readily seen that all the
operator has to do is to draw the carriage to the right to the marginal
stop, and write without any loss of time.
At one time a speed contest between pen billers and machine
billers was held on one of the large railroads of this country, and
permission was given the machine people to change the position of
the headings of the freight bills. The salesman in charge of the test
studied to eliminate certain wasted movements of the typewriter
carriage. He succeeded in arranging the printed matter on the bill
in a manner which permitted of three starting points in the heading
and body of the bill. By pressing his tabulator stop after writing
273a name or figure, the machine would immediately jump to the next
printing point on the line. This arrangement greatly facilitated the
work, and enabled him to prove the superiority of machine over pen
work. If he had endeavored to use the old stationery with its irregular
headings, he would have made a failure of the test.
Designing Stationery. In designing invoices, order forms, and
statistical forms, it should be always borne in mind that the ordinary
typewriter or billing machine spaces ten letters to the inch, sometimes
twelve spaces to the inch with elite type, and sometimes eight spaces
to the inch with large Roman type. Therefore, all vertical lines
separating various columns of the form should be ruled in multiples
of tenths, twelfths, or eighths of inches, according to the spacing
(escapement) of the machine to be used. The different styles of
type are shown in Fig. 20.
In estimating the distance between lines, it should be borne in
mind that all typewriters and billing machines are arranged for spacing
one line, two lines, and three lines. By adjusting the spacing
device, the paper can be advanced the width of one, two, or three lines.
All headings on the invoice should be arranged so that the next
writing point below, on the invoice or order, will be one, two, or three
spaces, and the beginning of the body of the bill should be arranged
for in the same manner. This prevents any waste of time, and
eliminates the necessity of throwing off the ratchet spacing device
of the machine and turning the carriage by hand.
The first printing point on an order or billing form should be
placed in such a manner that the marginal stop of the typewriter
carriage, instead of a tabulator stop, will be available for use. The
second writing point on the form should be the first column stop
(the column finder on the billing machine is the device which automatically
stops the carriage at certain given points). The third
writing point on the line should be the second column stop, or decimal
tabulator stop, according to the one which is on the machine.
In Fig. 21 is shown an illustration showing the top sheets of
an order form designed to facilitate the work of the billing machine.
In addition to having all of the printed headings aligned vertically
on the last letter of each word, each line is either one space or two
spaces of the billing machine platen (rubber roll). This eliminates
any waste of time in spacing the order form through the machine.
274
Fig. 20. Styles of Typewriter and Billing Machine Type
275The last sheet of the form of the McCaskey Register Co. is
cardboard, with the numbers 1 to 31 printed along the top. A movable
metal "spud," or tip, is used to show the due dates of each invoice,
and to enable the collection clerks to quickly find the desired copies
of charges for the purpose of sending out statements from three to
five days ahead of due dates.
Styles of Type. The size and style of type is a very important
factor in all classes of work where legible manifolding results are
wanted. There are several classes of type used in connection with
billing machines. Different companies use different names in describing
them. The four sizes of type used are as follows:
- ELITE
- PICA
- MEDIUM ROMAN
- LARGE (or full) ROMAN
Elite. This style has come into general use in connection with
correspondence. It gives a dignified style to a letter. It is the
hardest type to keep clean—the most destructive to the rubber roll
and typewriter ribbon of any type made. It also manifolds very
poorly where a number of copies are used, as the type is so small
that the sixth or seventh copy, and many times the third and fourth,
are so blurred that it is impossible to tell an e from an a or an o.
This style of type is sometimes used for making up tabulated
statements where it is desired to crowd a large number of figures
to the inch.
Pica. This is the most generally used type of any. It manifolds
quite well up to six and seven copies. It is possible to write
only ten figures of this size to the inch.
Medium Roman. This is the next larger size type than the
pica and, on account of it being larger, it gives better manifolding
results. It also writes ten letters to an inch.
Large Roman. This is the size type which is used by railroad
and steamship companies for typewriting their way-bills. It is
possible to write only eight letters to an inch.
276
Fig. 21. Forms Showing Properly Designed Stationery
277Gothic Type. The term Gothic indicates the style, and not the
size of the type. If the small points at the top and bottom of the
Roman type were removed (these points are called serifs) the effect
would be that of Gothic type. A very pleasing combination on a
billing machine is two different sizes of Gothic type, the larger size
to be used for capital letters, the smaller size for the small (or lower
case) letters. Recent practice has demonstrated the value of using
capital Gothic letters of one size, as it increases the legibility of an
order or an invoice.
In manifolding, numerals should always be of the "open" kind,
that is, 1 2 3 4 5 6 7 8 9 0, and not 1 2 3 4 5 6 7 8 9 0, as the
former are much the more legible.
Carbon Paper. There is no article which is so generally misused
in the commercial world and which is so little understood as carbon
paper. In order that the correct usage may be clearly understood
a brief description of its manufacture is given.
The chief ingredients of carbon paper are oil, wax, paper, and
color. Oils and waxes are used to give wearing surface, elasticity,
and body to the color mixture. Tissue paper—generally of imported
quality—with a fine, strong fiber is used. The quality must be first
class in order to insure absence of holes and other imperfections in
the sheets. Generally the sheets are cut 20 x 30 inches. A ream is
regarded as containing 500 sheets. Three weights of paper are
used, 4lb., 7lb., 10lb., respectively, meaning that 500 sheets of the
above size of paper will weigh the number of pounds named,
according to the thickness of the paper.
Color. The only really indelible color is black; that is because
carbon is the basis of the color. The colors which are used are
powders which have been ground as fine as possible. They are
mixed in proper proportions with oils and waxes. Formerly the
mixture was applied by hand, but great strides have been made in
machinery for automatically applying the color evenly to the paper.
It is important that the color or pigment be applied evenly to the
paper and that it penetrates the fiber. Unless the paper retains
the pigment, the carbon paper will not wear properly. The longer
the color adheres to the paper, the longer it can be used.
Finish. The finish of carbon paper is the factor which is so
little understood by the public. Carbon papers are finished with
soft, medium, and hard finishes. The first will hardly rub off on
the hand under pressure, the next will rub some, and the soft finish
will smudge if pressed against the hand. Each finish is intended for
278a definite use, which will be explained later. The manifolding
power of carbon paper depends absolutely on the typewriter itself,
the hardness of the rubber roll, the touch of the operator, and the
weight of paper, and lastly, the finish of coating on the paper. Two
operators on the same typewriter can secure totally different results
because one will have light, and the other heavy, touch. The regular
rubber rolls which are furnished with typewriters are medium hard—in
six months or a year they gradually grow harder, eventually becoming
as hard as slate. If a typewriter is to be used for regular
work as well as heavy manifolding, it should have two different rolls,
one for each kind of work. There is no reason for using a medium
hard rubber roll on the machine, getting poor results, and then
blaming the carbon paper. Use a hard rubber roll on the machine
and there will be no difficulty. Some makes of machines have
interchangeable rolls (known as platens) which are very useful. It
is the work of a minute only, to remove one and place the other on
the machine.
Four-Pound Paper. This class of carbon paper has a heavy,
sensitive coating, and is intended for heavy manifolding—for making
from five to twenty copies. Soft-finish carbon papers are always used
where heavy manifolding is to be done. The finish of the paper which
is being written upon is also a factor. Papers with a hard finish—that
is, a shiny surface—do not allow the color of the carbon paper
to take hold, and yet a paper with the soft finish will allow the color
to spread, and make a poor copy. This class of paper is also used
for making a few copies on very light-stroke machines like the Hammond.
Seven-Pound Paper. This weight of paper is adapted for making
from one to five copies. Being heavier than the four-pound, it
will wear longer. If coated heavily it will give more impressions
than if lightly coated, but the impressions will not be as clear and
clean.
Ten-Pound Paper. This weight of paper is intended for use
where one or two copies are wanted. Its weight enables it to stand
the hard usage to which it is put. On one or two copies, the additional
weight or thickness of the carbon paper does not affect the
imprint. This class of paper is used with billing machines of all
kinds.
279Full Carbon Papers. This is a paper which is coated on both
sides for making a multiplicity of copies on tissue. The pieces of
carbon paper are placed between every other piece of tissue paper
and manifold on the top of one sheet and the bottom of the next.
This carbon paper is used to reduce the bulk of paper in the typewriter—one-half
as much carbon paper being required. It is
sometimes called double carbon paper, and is mostly used by railroads
in making up way bills on yellow (dandelion grade) tissue paper.
Copy Carbon Papers. This paper is for use where it is necessary
or desirable to make a carbon copy from which to make a letter-press
copy. Hektograph carbons are for making carbon copies to
be used in a hektograph.
Pencil Carbons. This class of carbon paper is made in the
heavy grades of paper from seven-pound to twenty-pound and is
made full carbon in the seven-pound weight.
Pen Carbon. This class of carbon paper is made in the seven-pound
and ten-pound weights.
Troubles and Remedies. Carbon papers made in summer have
different treatment in the matter of color mixture than those made
in winter. Users should always remember that carbon paper which
has lain unused all year has gradually dried out and depreciated
in efficiency. The fresher a carbon paper the better—therefore it
is not economy to buy too large a supply if it is liable to stand
for more than six months. Never store carbon paper near heat,
nor in the direct rays of the sun.
The one great difficulty experienced with carbon paper is the
streaked effect called "treeing." This is caused by the carbon paper
being inserted unevenly between the sheets of paper used with it.
Once wrinkled, it remains so, and gives the streaked result as long as
it lasts. To guard against this trouble, the operator should watch
that the carbon paper is not wrinkled when inserting it between the
sheets of paper, and should press the release lever on the typewriter
to release the paper-feed rolls on the machine, after the paper is
inserted in it, so that the unequal tension of the paper and carbon
paper may adjust itself.
Durability of Color. Black paper made of carbon pigment
is indelible and most durable. Blue or purple papers are next in
the order of durability of color, and are made of aniline dyes. Green
280next, and red next. The fact is that red and green carbon papers
should not be used for permanent records, as they will fade quickly.
Wearing Quality of Paper. Many times a typewriter will
have a rubber roll (platen) which has become pitted and worn from
age and the use of periods, commas, hyphens, and ditto marks.
This is very destructive to carbon paper. New rubber rolls should
be placed on the machine. It is not economy to use the cheap
variety which can be purchased for 75 cents and which is nothing
more than rubber hose drawn over a wooden core. The latter is not
cylindrical and will give trouble. The type will print unevenly and
cause bad alignment, for which the machine will be blamed.
Blinds. Blind is the name given to a sheet of paper used in
connection with manifold work for preventing all of the information
on the top sheets from being manifolded on certain of the sheets
underneath.
For instance, in describing the scheme for providing the packing
department with a description of the goods to be shipped, but
with the quantity column blank, it will be remembered how a strip
of paper of proper size wide enough to cover the quantity column
was placed over the left side of the invoice from top to bottom.
Therefore all quantities, instead of manifolding onto the packer's
sheet, manifolded onto the strip of paper known as the blind.
A blind may be of any given shape, and cut away at the top,
side, or bottom; or, in some cases, irregular-shaped cuts are made
in the middle of the sheet or near the edges. The cuts are made in
order to allow certain information to be manifolded on the next
sheet under the blind. The balance of the information on the top
sheet is manifolded onto the blind, which is thrown away. It is reasoned
that it is cheaper to use a sheet of paper for this purpose than
it is to stop and make a separate sheet with part of the information
only, typewritten thereon.
Loose-Leaf Sheets with Invoices in Blanket Form. In some
lines of business it is possible to use invoices of equal size. Some
firms therefore have the invoices and sales sheets of equal size. The
281top sheet is perforated horizontally at equal distances, which permits
the invoices to be torn apart so that one blanket of form invoices
may be separated into three or four separate invoices. This plan
can be used where the work is done on an ordinary letter-writing
machine. In preparing the papers for billing, a sheet of carbon
equal in size to the sales sheet is used. A heavy-weight carbon (10lb.)
with hard finish is the best kind of carbon to use for this work.
If an extra sales sheet is needed for any purpose, a duplicate sheet of
paper, preferably of another color, can be used with another sheet
of carbon interleaved between the two sales sheets. This method
is wasteful of space as far as the sales sheet is concerned. If each
invoice were loose and placed in the machine in such a manner that
the first written line on the invoice would be two or three spaces only
below the last item of the previous invoice manifolded on the sales
sheet, generally one more invoice of average size could be manifolded
onto the sales sheet.
Loose-Leaf Sales Sheet with Separate Invoices. This combination
is made possible by the billing machine, the flat-bed and the
cylinder style. Cylinder billing machines are equipped with special
carriages having special feed rolls which hold the sales sheet
until it is fed entirely through the machine. Cylinder machines
also have an independent feed roll which can be released by a special
lever. This permits an invoice to be inserted in the machine, and
then clamped into position by the intermediate feed roll and
fed through the machine with the sales sheet until the invoice is
completed. The intermediate feed roll is then released, and the
invoice removed without disturbing the sales sheet. The next invoice
is then placed in position, and the same operation is repeated. This
allows one invoice to be manifolded very nearly under the previous
invoice. Some firms having invoices of one or two items only, which
permits of from seven to nine invoices being manifolded on each page,
have the invoices made up in blanket form; that is, seven or eight
invoices to a strip. After each invoice is manifolded they advance
the next invoice into position and then tear the invoices apart as
previously described.
Carbon Paper Cut for this Class of Work. Some operators
doing condensed billing work prefer to use carbon paper the same
size as the invoice, and to remove the carbon paper each time an invoice
282is completed. This necessitates a great deal of handling of
carbon paper. It is preferable to use a large sheet of carbon paper
the same size as the sales sheet, feeding it through the billing machine
with the sales sheets. This eliminates the necessity of picking up a
piece of carbon paper each time an invoice is placed in the machine.
With the former method, if one had four invoices to one page of a
sales sheet, it required one to pick up the same piece of carbon paper
four times, or once with each invoice. The latter plan necessitates
handling the carbon paper once only, when the sales sheet is placed in
the machine. The operator positions the second or third invoice
on a sales sheet, in order to avoid writing over the previous invoice,
by spacing the carriage three times after an invoice is completed.
Using the Sheets Serially. All sales sheets should be serially
numbered, in order that when placed in a binder the loss of any
sheet may be detected by a missing number. Some firms prefer to
use one side of a sales sheet only. In this case, a sales binder holding
375 sheets would have 375 pages. Where the sheets are numbered
on both sides, the sales binder would have 750 pages. If the
appearance of a page is marred by an invoice being spoiled, that
sheet is not thrown away, and the fact that it is not is an incentive
for the operator to do good work.
Handling Credit Memoranda. Some firms prefer to handle
their credit memoranda on different-colored paper (generally pink)
for both invoices and the large sheets which correspond to sales
sheets. All of the rules which govern the making of invoices and
loose-leaf sales sheets apply to the execution of credit memoranda.
General Remarks Regarding Billing Machines. The flat-bed
billing machine enlarged somewhat upon the idea of using special
characters for certain abbreviations peculiar to various lines of trade.
For instance, in the shoe business, the following abbreviations are
some of those used:
| WOM |
means |
Women's |
| CHI |
" |
Child's |
| BOYS' |
" |
Boys' |
| BAL |
" |
Balmorals |
| BLU |
" |
Bluchers |
| PR |
" |
Pair |
| PRS |
" |
Pairs |
| DOZ |
" |
Dozens |
283The cylinder machines have adopted the same plan. In the
cylinder machines there are two distinct classes—those having two
type to a type-bar, such as the Remington and the Underwood, and
those having one type to a type-bar, with double the number of bars,
such as the Smith-Premier. Both classes of machines can use
special characters, but the machines having one type only to a bar
have a preference in that they have more room in which to place
special characters.
There is considerable saving in the use of special characters, as
evidenced by the following example:
OCT 14 09.
This necessitates nine strokes where each letter is written
separately. Had this been written by three special characters,
it would have necessitated five strokes only. The
special characters would be used as follows: OCT.-space-14-space-09.
To the uninitiated, it would seem that a special character of
three letters, such as the abbreviation OCT., would occupy three spaces
on the machine, and consequently would overlap on the word at the
right. This is obviated by placing the type on the type-bar in such
a manner that the letter T of the abbreviation is in the printing point
of the paper. The following illustration will show how the type are
placed or aligned in order to secure the desired results:
As the month always precedes the next word, the abbreviation
OCT is aligned so that the two first letters are to the left of the printing
point. In case a machine were equipped with numbers for all
the days of the month, the character 14 would be aligned to print
either side of the printing point. As the abbreviation 09 would
always follow and never precede, it would be aligned with the 0 in
the printing point, with the 9 printing to the right of it. It is very
important to have special characters properly aligned so that the
abbreviations which always precede are aligned to print on the last
letter, and the abbreviations which follow are aligned to print on the
first letter.
It is impossible to print abbreviations in solid matter such as a
letter. They are only to be used in connection with dates of invoices
284or orders, in connection with names of firms. For instance, the
abbreviation Messrs., at the beginning of a firm name where such a
term is desired, or the abbreviation Co. at the end of a firm name or
the abbreviations Pr., Doz., Gro., and similar abbreviations, come in
the body of a bill and, preferably, in the first column after the quantity.
It should be remembered that when the rubber platen of a billing
machine becomes worn and cut with holes incident to the use of periods,
commas, hyphens, etc., the special character type will sometimes
print heavy at the top and light at the bottom of the letter, or vice
versâ. This is remedied to some extent by placing a new rubber
roll on a cylinder billing machine, or a new rubber covering on a flat-bed
billing machine.
Special characters are used to a better advantage on the under-stroke
(or blind machine) than on the visible machine. In the latter,
the type-bars are all grouped in less than a half circle, which necessarily
crowds the type-bars a little closer together, and therefore does
not permit of special characters of a large size.
Tabulators on Billing Machines. It is absolutely essential that
every billing machine be furnished with either a single-stop (known
as a column-stop) tabulator or a decimal tabulator, preferably the
latter. A single-stop tabulator is used as follows:
On the billing machine frame rests a bar on which metal stops
or pegs are placed at predetermined intervals. By pressing the
column stop, the carriage holding the paper is released, and jumps
automatically to the first stop. After the information is written,
the stop is again pressed, and the machine jumps automatically to
the next printing point. The following example shows the use of
the column stop:
| John Jones |
Marion, Ind. |
XXV |
| A. B. Smith |
Washington, D. C. |
XXX |
| G. Barnes |
Seattle, Wash. |
XXX |
The following example shows the use of the decimal tabulator:
10.50
.50
150.25
15560.65
With the decimal tabulator, the operator would press the tens
key, which automatically places the carriage in a position to begin
285writing the amount 10.50. If the column stop were used for this
purpose, it would have stopped the machine at the period point, and
necessitated the operator pushing the carriage two points to the right
in order to begin printing two points to the left of the decimal points.
Some operators place the column stop so that the machine always
stops at the tens point, and if an amount of 1.00 or less is to be written,
they use the space key. This is quicker than to always stop at the
decimal point and then position the carriage properly by hand.
However, where any tabulated work involving figures which vary
greatly is to be done, it is decided economy to use a decimal tabulator.
Most operators do not see the advantage of using tabulators, and in
many instances will continue to waste time spacing the machine with
the space bar. If they would avail themselves of the tabulator device
they would jump from one part of the line to the next desired point
instantaneously. It should be remembered that billing work is a
constant repetition of certain manual movements. If one movement
in ten can be eliminated, it is equivalent to saving one hour in ten.
To show the great advantage of, and it might be said, necessity for, time
saving and short cuts in large establishments, a device used by
Butler Bros., a large mail-order house with warehouses in several of
the large cities, is an excellent illustration. This particular scheme
is used in Jersey City, N. J. It consists of two rows of billing
machine operators (sixty-five in number) placed in parallel
positions with an endless belt running between them, and two checking
clerks at the end of the row. As fast as the operators transcribe
the orders onto the order forms, the original and typewritten order
(with departmental copies) are placed on the belt and carried automatically
to the checker's desk.
The rubber belt passes over a pulley at the edge of the checker's
desk, which allows the orders to fall from the belt to the desk. The
belt returns to the end of the line, where it revolves around another
pulley. The power is furnished by a small electric motor.
Arrangement of Billing Machines in Large Business Houses.
In large businesses in the wholesale dry goods, wholesale notions, and
kindred lines, special arrangement enables a few billing machines
to accomplish a large amount of billing. In these classes of business,
it is the custom to call the lot number, class of goods, and the number
of yards to the bill-clerk, who in turn enters it on the bill and duplicate.
286The system used will be described elsewhere. Here it is
desired to touch upon the movable-platform idea only. The operator
is seated on an elevated platform on which is placed the billing machine
and the chair. This platform has rollers, and can be moved in
the aisle between two rows of counters on which the goods to be
shipped are placed. As soon as the callers call off the lot numbers,
description, and quantities of one shipment, the billing machine
operator moves the platform to the next lot of goods, which enables
him to hear the caller clearly wherever the caller may be. If the
bill clerk were permanently located in one portion of the room, he
would be liable to make errors through misunderstanding the caller.
A scheme which is largely used in those classes of business which
demand the "call off system" or, as they term it, "billing from call"
is to call off the word sixty-five as if it were sixity-five, and the word
fifty-five as if it were fifity-five. This prevents confusion between
these amounts which sound so much alike. Some firms for sixty-five
use the term sticky-five.
Use of Computing Machines in Connection with Billing. Many
firms use computing machines such as the comptometer for proving
the extensions on invoices. With a machine of this character, it is
possible to figure all of the extensions. The machine at the same
time automatically adds the totals, and, if there are discounts to be
taken off the bill, this operation can be performed without clearing
the machine. For instance, in the following example:
| 12 yards lace |
|
50 |
$6.00 |
|
| 15 yards ruching |
|
10 |
1.50 |
|
| 24 doz. hdchfs. |
|
12.00 |
288.00 |
|
| |
|
|
|
|
| |
|
|
$295.5 |
|
| |
25% |
|
|
221.63 |
By clearing the machine, is meant pulling the handle which
returns all of the wheels to 0 for the beginning of a new computation.
Without desiring to enter into the mechanical merits of adding
machines, either listing or non-listing machines, it is important to
touch upon the various arguments used in favor of billing machines
with adding attachments and without them.
The flat-bed machines were the first to use the combined machines.
The plan in use was to place two recording registers on the billing
machine and prove the total of each bill separately with one register,
and accumulate the totals of all the bills for the day on the other
287register. Certain firms used extra recording registers for recording
the totals of extra columns on the sales sheets in which they analyzed
the sales according to classes of goods or some other classification.
Some firms did not add the bills when making the extensions of the
prices and quantities, but left the additions for the adding machine.
The only draw-back to this plan was that if the operator copied a
wrong total from the register dial it caused trouble. This fault,
if fault it may be called, as it is not the fault of the machine, but of
the operator, has been corrected by placing a subtracting device on
the late models of combined billing and adding machines, whereby
the subtracting device is thrown into action when the total of the
bill is being written. If the correct amount of the bill is written on
the invoice, the dial figures all turn to ciphers, which indicates that
the amount has been correctly transcribed by the operator. Other
improvements will likely follow in the many machines which are
being placed upon the market. See Fig. 29 on Page 67.
Some firms prefer to do all the billing as one operation, and use
a separate or computing machine, as the case may be, for proving
the additions at the end of the day. The reason is that by having
two separate machines they can be used by different people during
the day for different work.
If computing machines are needed for adding, multiplying, and
taking off discounts, the non-listing machines are recommended, as
they are key-driven. If adding machines are needed when printed
lists are wanted of all additions, then listing machines are recommended.
The general public has recognized that each class of
machine has its separate use. Some firms check the totals of listing
machines with non-listing machines, in order to save time and paper.
Non-listing machines are used for taking a record of rolls and yards
of cloth during inventory time, and later are used to multiply the
extensions. Some dry goods firms hire expert operators at a dollar
an hour to do this class of work, as it can be done in one-fifth the time
that it would otherwise take. For instance, an example in multiplication,
such as 432 × 235, would take approximately ten seconds to
write down, multiply, and set down the figures. With a multiplying
machine mentioned above, it can be done in two seconds.
With listing adding machines, equally valuable results can be
obtained. In certain classes of work, such as collection letters in
288banks where there are rows of figures representing the various checks,
and typewritten information, such as description of endorsements,
it is much faster to place the sheets in the adding machine and list
the amounts thereon and automatically print the total with the
adding machine. This avoids the trouble due to operators printing
wrong totals on the billing machine. The typewritten information
is then put in on the typewriter or billing machine. There
is this to be said, however, if an operator prints a wrong amount on
a listing adding machine, the answer will be incorrect, but the machine
will print a correct total of the figures printed by the machine. A
listing machine can be equipped with a wide carriage and used for
printing lists of figures just the same as a typewriter. Time should
never be wasted printing a statement covering rows of tabulated
figures on any typewriter, and then taking the statement to an adding
machine and adding the columns to prove them, if it can possibly
be arranged to make up the entire statement on the listing machine.
Listing machines are now prepared to manifold at least two extra
copies, and are equipped with column tabulators.
For adding a number of columns, with or without a grand total
column at either the right or left side of the book or sheet, and where
the items are written one at a time in different columns, the combined
typewriter and adding machine is recommended. One such is
shown in Fig. 22.
The "colored sheet system" indicated below makes it unnecessary
to refer to the written matter for distribution. A glance indicates the
department or service for which every slip is intended. The distribution
may be as follows:
- The office record (register) may be filed numerically;
- The order book copies alphabetically;
- The requisitions by departments;
- The shipping instructions, chronologically;
- The salesman's records, territorially;
- The cost sheets, according to classification.
One copy may also be filed geographically for comparison of
results. This furnishes a complete record and makes reference easy.[6]
289This summary illustrates the use of the color scheme, and gives
a brief hint of the plan usually followed in filing order sheets for
various departments. It should be remembered that the best billing
and order plan in the world can be made the most abject failure, if
proper attention is not given to the proper filing of sheets.
Fig. 22. Combined Typewriter and Adding Machine. Elliott-Fisher Co.
For example, if clerks in looking for a certain order could always
give the order number, but not the name of the customer, it would
be wrong to file the orders alphabetically; in such cases, file the orders
numerically. Always file papers according to the information which
the clerk or executive will have at hand when looking up the same.
Sometimes, papers will be just as easily found when filed numerically
as alphabetically.
Reference Information. One very important feature to remember
in designing forms is to place all reference information on the
right-hand side of the sheet. In leafing loose sheets held in binders,
it will be easy to find the desired sheet if this plan is followed; but,
if the reference numbers are placed on the left side of the sheet, it
will be necessary to open the binder relatively wide to see each number.
In the illustration, Fig. 23, it will be noted that the order number
is properly placed, and that the printed headings are aligned
290horizontally at the back, which permits all typewritten matter to
be started evenly. The value of this point was touched upon in a
previous chapter, as to saving of time in the execution of the work.
In this particular form, however, there is typewritten matter to the
left of the headings, such as account of, ship to, etc. The marginal
stop on the billing machine should be set for the first typewritten matter,
and tabulator stops used for all matter to the right on each line.
One of the most effective means of short-cutting work, where
the nature of the business will permit, is through the use of compound
forms. These forms derived their name from the combination of
order and billing work on one set of sheets and accomplish in one
operation, sometimes in two, all the clerical work incident to the
receipt, registering, acknowledgment, billing, charging, and shipping
of an order.
It can be readily seen that if a firm can fill its orders completely,
or almost so, that there is no use to wait until the order is filled before
billing it. It is a great deal easier to place another sheet along with
the order forms and use it for an invoice. It is generally placed as
the top sheet of the set, and therefore it is the original.
Goods Shipped for Entire Order. If the nature of the business
is such that the firm can always fill its orders completely, it is perfectly
safe to enter prices, make the extensions, and complete the
invoice, with the possible exception of the date when the goods are
finally shipped, if they cannot be sent out the same day. In such
cases, a printed heading is provided on the invoice, opposite which
the shipping date is typewritten. This then becomes the date of
invoice.
291
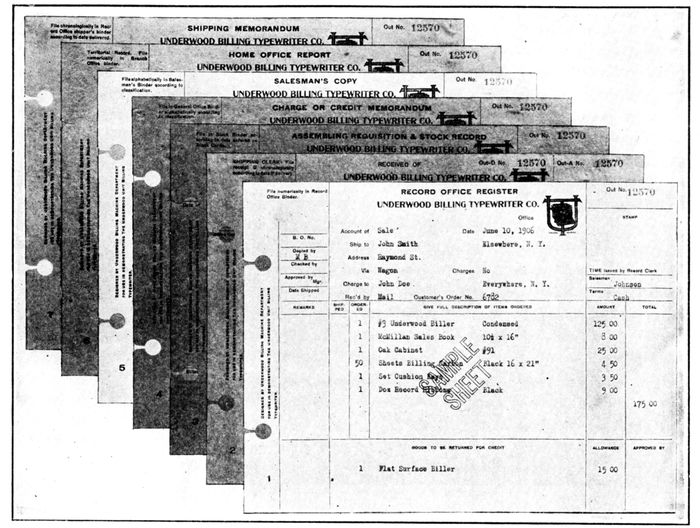
Fig. 23. The Colored-Sheet System. A Different-colored Sheet is Used for Each Department
Underwood Typewriter Co.
Goods Almost Completely Shipped. If it is possible that one,
two, or three items cannot be shipped at all, or in part only, it is the
custom to hold the invoice (and copy, or copies, when there are any)
in the office, arranged alphabetically according to customers, pending
receipt of information from the shipping department as to quantities,
weights, etc., of goods shipped. This invoice is an exact typewritten
duplicate of the balance of the order forms, and has the heading for
quantities to be shipped and, usually, prices for each article. Neither
the extensions of the items nor the footing of the bill have been made.
Generally, a copy of the order showing the quantities, weights, or
measures marked thereon is handed to the office. The copy of the
invoice is then placed in the machine, and the prices, extensions, and
footings made to correspond with the items which have been shipped.
The question arises in regard to the items which have not been shipped.
Some firms print on the bottom of each invoice the sentence: All
items which are not priced nor extended have been "back-ordered" and
will be shipped later. Other firms typewrite an X in the price column,
292or number the items which have not been shipped. They then make
a written explanation on the bottom of the invoice regarding the date
at which the balance of the goods will be shipped. In some lines
of business this plan tells the customer not only what he ordered, but
what has been shipped and when the balance will be shipped. The
memo on the bottom of the invoice also saves the writing of letters to
customers.
In other lines of business, this plan would be absolutely unfit—for
the reason that certain firms do not wish to call the customer's
attention to the items which have been omitted.
Compound forms generally have two columns at the left—one
for the goods ordered, the other for the goods shipped. If this were
not provided, it would be necessary to erase quantities in all instances
where a different quantity were shipped from the quantity ordered.
Fig. 24 is a good illustration of forms for a line of business which
always has the goods in stock. The various brands of goods are
printed in the body of the invoice. All that is necessary is to write
the quantities, prices, extensions, and footings. Four copies are
manifolded—invoice, warehouse order, house record, and collection
record.
The retail dry goods houses and department stores use a form
of billing which is different from any other, in that the bills are
rendered to the customer once a month only. There are other lines
of business which render their bills monthly, and which use the same
style of billing.
A folded form is used, the top sheet when completed at the end
of the month is mailed to the customer. The second or duplicate is
retained for the record of purchases.
When a customer makes a purchase, the saleslady makes the
charge in her sales book. One copy goes with the goods to the
wrapping desk, the other goes to the cashier's desk. The wrapper
cannot handle a package without a duplicate sales slip. The packer
removes from his duplicate slip a stub bearing the same number as
the slip. This is to prevent goods being removed from the house
without proper authority. The cashier retains the slip if cash has
been paid, but passes the slip on to the auditing department, if the
slip is marked by the saleslady charge.
293
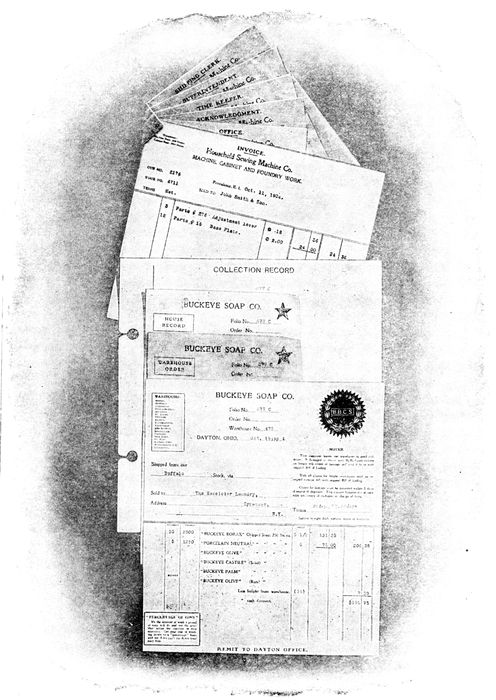
Fig. 24. Compound Forms, Showing Invoice and Office Records
Remington Typewriter Co.
294In large stores like John Wanamaker's, the customers are given
by the credit man a brass check with their number marked thereon.
This shows each clerk with whom they deal that they are entitled to
credit, without having them identified each time they make a purchase.
In smaller cities, the clerks become familiar with all the
charge customers, and any plan of this character is not needed.
The sales slips are all numbered from 1 to 50, and the auditing
department checks back each day all the slips of the different sales-people
to see if all the slips have been accounted for. Some stores
have a chart on the cashier's desk with the clerk's number at the top of
each column, and the check numbers listed serially in each column, as
shown in Table I.
Table I
CHART FOR CHECKING RETAIL SALES SLIPS
| 1 |
2 |
3 |
4 |
5 |
6 |
7 |
8 |
9 |
10 |
11 |
12 |
13 |
14 |
15 |
| 1 |
1 |
1 |
1 |
1 |
1 |
1 |
1 |
1 |
1 |
1 |
1 |
1 |
1 |
1 |
| 2 |
2 |
2 |
2 |
2 |
2 |
2 |
2 |
2 |
2 |
2 |
2 |
2 |
2 |
2 |
| 3 |
3 |
3 |
3 |
3 |
3 |
3 |
3 |
3 |
3 |
3 |
3 |
3 |
3 |
3 |
| 4 |
4 |
4 |
4 |
4 |
4 |
4 |
4 |
4 |
4 |
4 |
4 |
4 |
4 |
4 |
| 5 |
5 |
5 |
5 |
5 |
5 |
5 |
5 |
5 |
5 |
5 |
5 |
5 |
5 |
5 |
| 6 |
6 |
6 |
6 |
6 |
6 |
6 |
6 |
6 |
6 |
6 |
6 |
6 |
6 |
6 |
| 7 |
7 |
7 |
7 |
7 |
7 |
7 |
7 |
7 |
7 |
7 |
7 |
7 |
7 |
7 |
| 8 |
8 |
8 |
8 |
8 |
8 |
8 |
8 |
8 |
8 |
8 |
8 |
8 |
8 |
8 |
| 9 |
9 |
9 |
9 |
9 |
9 |
9 |
9 |
9 |
9 |
9 |
9 |
9 |
9 |
9 |
| 10 |
10 |
10 |
10 |
10 |
10 |
10 |
10 |
10 |
10 |
10 |
10 |
10 |
10 |
10 |
As fast as the checks are received at the cashier's desk they
are checked. If one of the clerks should sell goods to a friend,
and send one slip to the packer, but destroy the cashier's copy, the
fraud would be detected, as the next slip which would be sent in
would show by the number that the previous one was missing. The
matter could be investigated immediately. The auditing departments
of different stores handle the detail of the work in various ways—which,
however, are about the same. Some stores, after they prove
that there are no slips missing by checking the slips by the serial
numbers, add them up on adding machines. As some stores do not
care for a list of the slips, they use a non-listing machine, such as the
comptometer. Other stores add the sales of each clerk separately,
and add the totals of all the clerks to secure the total sales. The
295total sales of each clerk are then entered on a statistical sheet which
shows a comparison of the total daily sales of each clerk for the
month, as shown in Table II.
The slips are then sorted according to departments, then added
again, and similar information written on statistical sheets with the
department numbers at the top, instead of the clerk numbers. The
grand totals must agree to prove the work.
The slips are then sorted according to customers. If Mrs.
J. B. Jackson has bought goods in three different departments, the
auditing department will pin the three slips together and mark the
total of the slips to be charged to her account on the back of the
under slip. If there are twelve bill clerks and twelve billing machines,
all the slips will then be assorted into twelve lots, each lot
representing the number of accounts taken care of by each bill clerk.
TABLE II
COMPARISON OF DAILY SALES OF CLERKS
|
Clerk No. |
1 |
2 |
3 |
4 |
5 |
6 |
7 |
8 |
| Total |
Days |
|
|
|
|
|
|
|
|
| 335 38 |
1 |
30 50 |
55 45 |
47 70 |
35 35 |
56 78 |
34 25 |
40 56 |
34 79 |
| 492 53 |
2 |
56 74 |
87 55 |
9 76 |
87 23 |
54 09 |
19 89 |
86 75 |
90 52 |
| etc. |
etc. |
etc. |
etc. |
etc. |
etc. |
etc. |
etc. |
etc. |
etc. |
| |
|
|
|
|
|
|
|
|
|
Each bill clerk receives the slips in alphabetical order. The
monthly folded bills are arranged in the same order. These are held
in binders—a special kind, such as the Tengwall, being used—from
which the bills can be easily and quickly removed. Some firms
prefer to file daily in vertical files the current monthly bills, upon
which the charges are being made.
Some machines, such as the Smith Premier and the Elliott-Fisher,
have a carbon roll on their machines for manifolding these duplicate
folded bills without handling the carbon paper. These attachments
were especially designed for this particular work.
After the operator has entered the charges of the three slips for
Mrs. J. B. Jackson, or any other customer having more than one
296slip for the previous day's purchases, she compares the total she
has placed on the bill with the total marked on the back of the slips
by the auditing department.
Fig. 25 shows samples of folded monthly retail bills. The black
showing under the top sheet, which is turned over, is the carbon paper
used with the bills when made on machines not equipped with the
carbon-roll attachment. Some firms place the carbon paper between
the sheets at the beginning of the month, and leave it there; others
place the carbon paper between the sheets for every charge which
is made to the bill.
After all the charges have been made, the operator adds up on
the adding machine the totals of all the last charges on the various
bills to which charges have been made that day. This total must
agree with the amount which the auditing department handed over
to each bill clerk to be entered upon these bills. The Smith Premier
and Elliott-Fisher have tally-strip devices which automatically record
the total of each charge made to all the various bills each day. This
paper strip, when added up, must agree with the total of the auditing
department figures.
At the end of the month, about the 26th, most firms begin to
total the columns of the bill. The final total of each bill added to
the total of every other bill must give a grand total equal to all the
charges for the month. This proves that each bill has been correctly
added. The balance due from the previous bills is then brought
forward, and any payments made during the month deducted, and the
bill footed. All credits for returned goods are entered during the
month the same as the charges, excepting that they are placed in a
separate column provided for that purpose, and deducted at the
end of the month from the charges.
Some firms post the total charges and credits for the month
to the ledger in two lump sums. Other firms prefer to post the total
of each day's charges to the ledger daily, instead of letting the posting
go until the end of the month. This is a matter to be decided from
a bookkeeping standpoint. If the bookkeepers have the current
month's charges in the ledger, it saves referring to the bills at the
bill clerk's desk for information or the current month's charges.
297
Fig. 25. Monthly Statements of Retail Dry Goods Houses
Remington Typewriter Co.
298
Fig. 26. Smith Premier Device for Inserting Dry Goods Billing Forms Evenly
299After the bills have been sent out, the duplicates are filed away.
The best known way to file them is alphabetically; each customer's
bill for the various months together. This is in contrast to the plan
of filing each month's bills away separately. If it is wished to refer
to any one person's charges for a given number of months it is necessary,
under the latter plan, to refer to several binders.
Fig. 27. Remington Billing Machines
One of the devices which did more to permit cylinder machines
to do billing successfully is shown in Fig. 26. Formerly, when two
or more sheets of paper were inserted in a cylinder machine, the
small feed roll which rests against the large rubber platen, fed the
under papers at a different speed than those sheets which rested
against the large roll. The result was that the papers were fed unevenly
into the machine. When removed, it was impossible to replace
them in the same relation in which they were before.
The device illustrated furnishes a resting place for evenly placing
all the sheets in the machine by pressing a release lever which draws
the feed rolls away from the large roll until the papers or sheets are
300properly placed in the machine. Started evenly, they will invariably
feed evenly.
Fig. 28. Smith Premier Dry Goods Billing Machine
This is of particular advantage in retail dry goods billing, where
a sheet is placed in and out of a machine as many as thirty times a
month. If the top of the bill is each time started from the same
starting point, namely, the top of the statement, it will feed correctly
to the next writing point on the statement without any adjustment.
The Remington, Fig. 27, and Underwood machines are
equipped with devices for the same purpose. The Smith Premier,
Fig. 28, and the Elliott-Fisher machines are equipped with rolls
of carbon which automatically manifold folded monthly bill forms.
One of the successful devices which is being perfected at this
time is a combination of an adding machine and a cylinder billing
machine which can be operated as a combined machine or separately
as two machines, and may be actually removed, one from
another. The idea is to have a platen or roll which can act as
shuttle between the typewriter and the adding machine. By pressing
a button, the roll travels from the typewriter to the adding
machine. This scheme has the same advantage as has the farmer
who can operate his horses singly or in pairs.
The adding machine people have been experimenting and gradually
increasing the printing capacity of their machines. They are
now able to print the different months of the year and some other
301abbreviations for monthly statement work. Further developments
can be expected along this line. Adding machines which list are a
very important factor in office work and their capacity is so large for
certain classes of work that space does not permit of detailed treatment
here.
Fig. 29. Adding and Subtracting Machine Combined with Cylinder Billing Machine
Remington Typewriter Co.
While marvelous improvements have been made in the last decade,
the next one promises equally well, especially in the adding-machine
line.
REVIEW QUESTIONS. PRACTICAL TEST QUESTIONS. — REVIEW QUESTIONS ON THE SUBJECT OF COMMISSION AND STORAGE — REVIEW QUESTIONS ON THE SUBJECT OF SINGLE ENTRY—COMPARATIVE STATEMENTS — REVIEW QUESTIONS ON THE SUBJECT OF TRUSTEES' ACCOUNTS; STOCK BROKERS' ACCOUNTS — REVIEW QUESTIONS ON THE SUBJECT OF BILLING AND ORDER RECORDING
303
In the foregoing sections of this Cyclopedia numerous
illustrative examples are worked out in
detail in order to show the application of the
various methods and principles. Accompanying
these are examples for practice which will aid the
reader in fixing the principles in mind.
In the following pages are given a large number
of test questions and problems which afford a
valuable means of testing the reader's knowledge
of the subjects treated. They will be found excellent
practice for those preparing for Civil Service
Examinations. In some cases numerical answers
are given as a further aid in this work.
305
1. What advantages are derived from a division of the ledger?
Name the three most common subdivisions of the ledger.
2. What accounts are kept in the purchase ledger; in the sales
ledger; in the general ledger? Under what circumstances should
accounts with an individual be kept in both purchase and sales
ledgers?
3. What is a controlling account? What do the balances of
sales and purchase controlling accounts represent? From what
sources are the debits and credits to these accounts derived?
4. When loose-leaf order blanks are used, what is the customary
routine followed in filling and charging orders?
5. For what purposes are special distribution columns in a
sales book used?
6. To what accounts in the general ledger are total purchases,
as shown by the invoice register, posted? In what way are these
two accounts distinguished?
7. Describe briefly the cash journal, and explain how it is
used? What, if any, objection can be raised to making entries which
do not involve an exchange of cash, or its equivalent, in the cash journal?
8. Why is the expense account divided? Name some of the
accounts representing different classes of expense.
9. What is meant by petty cash, and how should the account
with petty cash be handled?
30610. The check of Martin Mason for $164.20 went to protest,
and was returned by our bank with a protest fee of $2.50. What
entry is necessary to record this on our books?
11. Prepare trading and profit and loss accounts representing
the transactions listed in Art. 16, Pages 28 to 31, inclusive.
12. How can an order record be used as a sales record? Why
is an abstract of sales used in connection with such sales records?
Explain how this abstract is made up.
13. If goods are sold at f. o. b. prices, but the freight is prepaid
as an accommodation to the customer, how should it be treated on
the books? Why?
14. Name three or more subdivisions of sales expense, and
explain what items are properly included in each.
15. Why are check registers taking the place of the old style
check book? When a check register is used, how are the checks
kept?
16. What is a cash received book, and for what purpose is it
used?
17. Complete the exercise given at the end of Art. 29, Page 42.
18. What is your understanding of the meaning of the terms
commission and brokerage? What is the distinction between a commission
merchant and a merchandise broker?
19. What is a manufacturer's agent, and how does his business
differ from that of a commission merchant or broker?
20. By what term is a consignment of goods to a broker known
on the books of the shipper? In what name is an account opened
to represent the consignment?
21. How is the above account made up? When is the account
closed, and to what account is the balance transferred?
22. What is an account sales? When an account sales is
received without a remittance, what account should be opened,
and what does it represent?
23. When a broker receives a shipment of goods to be sold on
commission, by what name is it known on his books? In what name
is an account opened?
24. If a broker renders an account sales without a remittance,
to what account should he credit the net proceeds? Why?
30725. If a broker has on hand any unsold consignments when
his books are closed, do the accounts represent assets or liabilities?
How would you determine the broker's liabilities on account of consignments?
26. Name the books used by a produce shipper, and explain
how each is used.
27. What is a shipment ledger account, and how is it made up?
What is a profit and loss on shipments account?
28. In what way does the journal used by a shipper differ from
the one used by the average merchant?
29. How is the trading account of a shipper made up?
30. Prepare trading and profit and loss accounts called for in
Art. 48.
31. Name and describe the uses of the books used by a commission
merchant.
32. Prepare trading and profit and loss accounts, and balance
sheet called for in Art. 57.
33. What is a storage business, and for what purpose is it
conducted?
34. What is a warehouse receipt, and what does it represent?
35. Explain what is meant by simple storage, and average
storage.
308
1. What is the distinctive feature of single entry bookkeeping?
In what respect does single entry fail to fulfil the functions of bookkeeping?
2. What books are usually used in single entry? How does
the single entry cash book differ from that used in double entry?
3. In posting, what features distinguish single entry from
double entry?
4. How can the accuracy of single entry books be proved?
5. To determine the profits of a business whose books are
kept by single entry, what steps are necessary? What are the steps
in closing single entry books?
6. On a certain date the assets and liabilities of Henry Lamson
are as follows:
| ASSETS |
| |
| Cash |
$452.00 |
| Due from sundry debtors |
77.20 |
| Merchandise per inventory |
764.50 |
| |
| LIABILITIES |
| |
| Due sundry creditors |
142.00 |
The following transactions are recorded:
| Sales to sundry persons on account |
$46.71 |
| Bought from sundry persons on account |
339.54 |
| Sales for cash |
96.90 |
| Received cash on account |
64.00 |
| Paid cash on account |
133.50 |
| Paid cash for rent |
37.50 |
| Paid cash for clerk hire |
8.00 |
309Record these transactions in single entry books; prepare proof of
ledger and statements of assets and liabilities, the merchandise inventory
at end of period being $983.75. Do the books show a profit or
a loss, and how does it affect the account of the proprietor?
7. Explain, briefly, the necessary routine followed in changing
single entry books to double entry.
8. H. P. Hayes established a small factory upon a borrowed
capital of $10,000. The undertaking was a success, and at the close
of the first year his financial condition was disclosed by the following
particulars:
| Bills payable |
$4,000.00 |
| Accounts payable |
6,574.50 |
| Cash |
1,752.50 |
| Accounts receivable |
12,694.18 |
| Inventory |
4,765.90 |
| Salaries |
3,500.00 |
| Sundry expenses |
435.50 |
| Manufacturing expenses |
11,759.50 |
Mr. Hayes kept his own books during his first year in business,
but did not keep them by double entry. His sales for the year
amounted to $35,643.25, and his total purchases amounted to $16,076.07.
At this point Mr. Hayes admitted as a partner, A. B.
Andrews, who contributed $10,000.00 to the partnership upon the
agreement that the partners should share equally in the business.
A bookkeeper was engaged to keep the books by the double entry
system. From the particulars given, make a trial balance and the
necessary journal entries to complete the change to the double entry
method. Ascertain the interest of Mr. Hayes in the business, and
credit his account with the same.
9. Foster, Harvey, and Morton—a copartnership—wish to
change their method of bookkeeping from single to double entry.
The partnership agreement provides that each partner shall share
in the profits in proportion to his investment. Separate investment
and withdrawal accounts have been kept with each partner. In the
following statement of ledger accounts, partners' investment accounts
show the same balances as at the last adjustment, no additional
investments having been made:
| 310 |
| Foster, Investment |
Credit Balance |
$1,600.00 |
| Harvey, Investment |
Credit Balance |
1,200.00 |
| Morton, Investment |
Credit Balance |
1,200.00 |
| Personal Accounts |
Credit Balance |
900.00 |
| Personal Accounts |
Debit Balance |
1,900.00 |
| Foster, Withdrawals |
Debit Balance |
315.00 |
| Harvey, Withdrawals |
Debit Balance |
240.00 |
| Morton, Withdrawals |
Debit Balance |
155.00 |
| Bank |
Debit Balance |
2,050.00 |
| Cash in Office |
|
45.00 |
An inventory shows merchandise $1,775.00, fixtures $300.00.
Show all entries necessary to make the partnership adjustment
and change the books to double entry, indicating by check √ the
accounts to be posted.
10. The books of the Star Coal Company, a corporation with a
paid-up capital of $10,000.00, have been kept by single entry. The
following facts are gathered from the books:
| Cash in Bank |
|
$3,500.00 |
| Personal Accounts |
Debit Balances |
6,500.00 |
| Cash in Office |
|
200.00 |
| Personal Accounts |
Credit Balances |
2,500.00 |
An inventory results as follows:
| Coal |
3,750.00 |
| Horses and Wagons |
800.00 |
| Furniture and Fixtures |
300.00 |
Make necessary journal entries to change to double entry.
Provide a reserve of 5% for uncollectible accounts, 10% for depreciation
of horses and wagons, 10% for depreciation of furniture and
fixtures. Declare a dividend of 10% and transfer balance of profits
to surplus, making all journal entries to record these transactions.
11. Prepare a model trial balance of an imaginary business, or
one with which you are familiar, giving special attention to the proper
grouping of the accounts. Explain the benefits of your grouping of
the accounts.
12. What is a working balance sheet? From the trial balance,
which you have prepared, make up a working balance sheet, supplying
such additional figures as may be necessary.
13. What are the fundamental advantages of comparative
statements? On what basis should percentages be figured in on
analysis of the manufacturing account? of the trading account?
31114. To prove the accuracy of the ledger without a trial balance,
what steps are necessary? What test is applied to determine whether
the ledger balances?
15. What is meant by a book inventory? How can the receipts
be determined? the disbursements or quantities sold?
16. What is the reverse or slip posting system? How is it
operated?
17. Describe, briefly, the loose-leaf ledger. Describe the principal
methods of indexing. Name some of the advantages of the
loose-leaf ledger.
18. For what classes of accounts is the card ledger specially
desirable? What are the principal methods of indexing the card
ledger?
19. What is a tabular ledger? Describe the Boston Bank
Ledger. Is a tabular ledger well adapted for commercial accounts?
20. What is meant by a balance ledger? What are its advantages?
21. Prepare a form of cash journal segregating administrative,
selling, and manufacturing expense for an imaginary business, or
one with which you are familiar.
22. Prepare a form of sales journal for a business having five
departments.
312
1. From an accounting standpoint, into what two classes can
business be divided? What is the position of the trustee of an estate,
as against the public?
2. Describe the essential features of the accounting of an
executor.
3. In what two forms may an executor's accounts be kept?
By what term are his accounts with properties known?
4. What are the proper classifications of an executor's
accounts?
5. Two trustees collect in one year an income of $50,000.00
for a beneficiary, at an expense of $3,100.00. If each trustee receives
an equal share, what commission should each receive, and what
amount will be paid to the beneficiary, under the New York law?
Prepare a complete solution of this problem.
6. Prepare a solution of the following: Four trustees collect
and pay out of an estate the sum of $416,000.00, the total debts of
the estate being $201,000.00. What commission will each trustee
receive?
7. Prepare a statement of the executor's accounts—from the
particulars given on Pages 17 and 18—showing the balance due
each legatee.
8. What is a realization and liquidation account? How is it
made up?
9. What is a statement of affairs? In what respect does it
differ from a balance sheet?
31310. How does a statement of affairs of a bankrupt differ from
that of a going concern?
11. What is the purpose of a deficiency account?
12. Wm. Andrews, finding himself on July 1st unable to meet
his obligations, asks you to make up his statement of affairs for submission
to his creditors, and a deficiency account for his own information.
You find from his books and other sources the following
facts regarding his business:
| Unsecured creditors |
$9,000.00 |
| Fully secured creditors |
2,300.00 |
| Holding securities of the value of $3,000.00 |
|
| Partly secured creditors |
35,000.00 |
| Holding securities of the value of $20,000.00 |
|
| Preferred claims |
800.00 |
| Bills payable |
20,000.00 |
| Accounts receivable, home office (good) |
1,000.00 |
| " " (doubtful) $200.00, estimated to |
|
| realize |
75.00 |
| " " (bad) $300.00 |
|
| Stock, Home Office, cost $1,500.00, estimated to |
|
| realize |
1,200.00 |
| Stock and accounts receivable, less sundry liabilities, |
|
| at branches |
36,000.00 |
| Of which it is estimated there will be a loss |
|
| on realization of stock $6,000.00, of accounts |
|
| receivable $9,000.00. |
|
| Buildings and equipment at branches, cost $40,000.00, |
|
| estimated to realize |
20,000.00 |
| Office furniture $300.00, estimated to realize |
200.00 |
| Cash in office |
4.00 |
| Cash in bank |
80.00 |
| Bonds held by fully secured creditors |
3,000.00 |
| Stocks held by partly secured creditors |
20,000.00 |
Six years ago Andrews' capital was $42,000.00. The profits
for the first three years appear to have been $3,000.00, $4,000.00,
and $5,284.00, and the losses for the three subsequent years $1,500.00,
314$2,500.00, and $3,000.00, after allowing $2,000.00 a year for interest
on capital. His withdrawals have been at the rate of $4,000.00 a
year. From these particulars, prepare a statement of affairs and a
deficiency account.
13. What differences exist between a transaction for the purchase
or sale of stock, and the purchase or sale of grain?
14. Explain a ring settlement.
15. What is necessary to post to the customer's ledger account,
and from what sources do you post?
16. Show form of margin book and explain how it is kept.
17. In what cases should interest be charged? What is it
charged for?
18. What should be entered in the general cash book?
19. Explain fully the handling of office cash.
20. If A bought 5,000 bushels of wheat at $1.20, and sold 12,000
bushels at $1.21, how much cash would he be obliged to deposit to
secure the fulfillment of his orders?
21. What is the cash which he deposits called?
22. Write an order form for the sale of 25,000 bushels of corn
@ 76¼c made upon the orders of Mr. D.
23. Show what acknowledgment must be made to Mr. D.
24. What is the daily record sheet? For what purpose is it
used? Explain the entries in this book.
25. Explain how stock purchases should be handled, what
records should be kept, and what information in regard to them is
necessary.
26. What is the difference between a bull and a bear?
27. Explain the meaning of a buying order and state how it
should be treated in the accounting department.
28. On July 5th James Robinson sold 25,000 bushels of September
wheat at 1.04½; on July 10th he purchased 10,000 bushels
wheat at 1.02¼, and on July 11th he purchased 15,000 bushels of
wheat at 1.02. Make a statement of this account for Mr.
Robinson.
29. What is the difference between listed and unlisted stock?
30. What is a debit or credit slip and for what purpose is it used?
31. Show the ruling of the stock ledger and explain the necessity
of each column. Rule a sample page.
31532. For what purpose is the journal used in connection with
the brokerage business?
33. Explain the meaning of buyer's option.
34. Explain the meaning of carrying charges.
35. Explain the meaning of a put and a call.
316
1. Explain the difference in principle between the cylinder
billing machine and the flat-bed billing machine.
2. Explain the meaning of manifolding.
3. Explain in your own language why the plan of copying
invoices in tissue books with a letter press is inferior to the billing-machine
method of typewriting the invoice and sales sheet simultaneously.
4. If an office boy mailed a pen-written invoice without copying
same in the tissue book, what method would enable the firm to
detect such oversight?
5. What is the difference between the style of invoice used
on flat-bed machines and on cylinder machines?
6. When a concern uses two ledgers on account of having
too many customers to be conveniently held in one ledger, what
change is advisable in ruling the columns of the sales sheet?
7. What plan is used in classifying sales according to territory,
salesmen, etc.; and what means is used to prove the footings
of each page?
8. How much of the left side of the sales sheet do you understand
is covered by the invoice when they are both in the machine
for the purpose of making the bill and charge?
9. How do you classify with the machine the amounts of the
bills in the columns to the right of the total column?
10. Name all of the reasons you can, whether included in the
textbook or not, for making duplicate invoices.
11. Explain why some firms are enabled to make their invoices
(and, of course, sales sheets) before the goods are shipped, and give
317reasons why other firms are forced to wait until after the order has
been shipped, or at least partially shipped, before making invoices.
12. Explain what plan you would use to inform the packer of
the description of the goods to be shipped, but prevent him from
knowing the quantities, in order to further prevent him from double-checking
the figures showing quantities and at the same time neglecting
to count the articles.
13. Where the firm sells three or four classes of goods and
wishes to keep a continuous record of the tonnage sold, that is,
weight of the various classes of goods, how would you rule the invoice
and sales sheet in order to shorten the billing?
14. If you were forced to substitute one size of an article in
place of another size ordered (without injury to the customer),
how would you design your forms in order to enable you to typewrite
the size shipped and size ordered on the sales sheet, and size ordered,
only, on the invoice?
15. If you wish to typewrite a requisition for goods ordered
at the time the invoice and sales sheet are written, how would you
arrange it?
16. What is the difference between the terms unit billing and
condensed billing? Under what conditions would you recommend
unit billing and when condensed billing?
17. What is the best plan of facilitating the filling of orders
where there are a large number of floors or departments and where
each day's orders are supposed to be filled upon the day the orders
are received?
18. Why should a plan which is highly satisfactory in a small
concern prove to be an absolute failure in a large one?
19. What is meant by split orders?
20. Describe the different forms of punched holes of loose-leaf
sheets and why the closed-hole punching is not adapted for use
with records which are to be removed and replaced in binders from
time to time.
21. Describe the different forms of binders with which you are
familiar.
22. In printing invoices what is the best plan of designing
the headings in order to facilitate the execution of the invoice on billing
machines? Would you pay any attention to the space between the
318lines of the heading and to the distance between the last line to be
typewritten on the heading and the first line to be typewritten on the
invoice?
23. Explain the mistakes made in using carbon paper, and
under what conditions you would use the various weights of carbon
paper.
24. Explain what is meant by a blind.
25. Explain what is meant by credit memoranda, and tell how
to use them in connection with a sales book instead of having to
use a separate credit sheet.
26. Explain the use of special characters on the billing machine,
and what is meant by aligning them in order to prevent one abbreviation
being printed over the top of another.
27. Explain the difference between a single-stop tabulator
and a decimal-stop tabulator.
28. What is the advantage of having a billing operator on a
platform on wheels in a wholesale dry goods house?
29. Under what conditions would you recommend the use of
the separate billing machine and separate computing machine for
the same work?
30. Explain the benefits to be derived from the use of the color
scheme.
31. What is meant by compound forms, and under what conditions
can they be used?
32. In what general way does retail dry goods billing differ
from condensed billing and what is the difference in the general style
of stationery used?
33. What is the best plan of filing the duplicate monthly retail
dry goods bill?
34. What is the plan used in retail dry goods billing to prevent
goods from being shipped out of the store without a charge
being made?
35. What is the advantage of a subtracting device on the billing
machine with adding attachment?